



PW Consulting: Global Wood Pallet Market to Reach $19.99 Billion by 2032 at 4.58% CAGR

Strategic Intelligence for the Wood Pallet Market: Navigating Growth and Complexity in 2026 and Beyond
The global supply chain ecosystem relies heavily on the humble yet critical wood pallet. As we move through 2026, industry stakeholders face a landscape defined by steady expansion, regulatory evolution, and intense competitive consolidation. PW Consulting is proud to introduce our latest comprehensive market research on the Wood Pallet Market, a study designed to equip decision-makers with the foresight needed to thrive in a maturing industry. This report serves as more than a static snapshot; it is a dynamic strategic tool built to clarify investment paths, operational risks, and long-term growth opportunities across the forecast horizon.
Wood Pallets Boxes Packaging Market
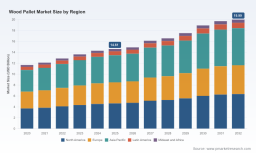
Our analysis covers the historical trajectory from 2020 through 2025 and projects performance through 2032. The overarching story is one of reliable, compounded growth. The market has demonstrated consistent revenue expansion over the past half-decade, reaching a valuation of approximately 14.61 billion USD in 2025. Looking ahead, the forecast period indicates a continued upward trend, with the market expected to grow to 14.91 billion USD in 2026 and further accelerate toward a 19.99 billion USD valuation by 2032. This trajectory is underpinned by a forecasted CAGR of 4.58 percent, signaling a healthy demand environment driven by foundational logistics needs and evolving supply chain configurations. Such macroeconomic indicators provide the baseline for strategic planning, yet understanding the nuances behind the aggregate numbers is where true competitive advantage lies.
Navigating the Competitive Arena
The market structure reveals a landscape dotted with both dominant integrated players and specialized niche operators. Concentration metrics indicate that the top three competitors hold 42.0 percent of the market share, while the top five entities command 55.0 percent. This level of concentration suggests that while scale advantages are significant, there remains substantial room for specialized providers to capture value through customization, service quality, and regional expertise.
Leading the charge among major manufacturers is PalletOne Inc., based in Bartow, Florida. As the largest new wood pallet manufacturer in the United States, PalletOne offers a comprehensive suite of services spanning lumber sourcing to finished products, including new and recycled pallets, custom crates, and repair services. A recent development underscores the aggressive consolidation shaping the sector: in April 2026, UFP Industries acquired John Rock to expand PalletOne's footprint in the northeast. This move highlights a strategic push to deepen regional density and logistical efficiency, a trend that enterprises must monitor closely when evaluating supplier stability and market entry barriers.
On the other side of the operational spectrum, Millwood Inc. exemplifies the scale of processing and distribution. With an annual throughput of 200 million pallets, Millwood supplies new and recycled pallets to national accounts, leveraging over 40 years of engineering and manufacturing experience. Such scale allows for significant cost efficiencies and reliability, making it a critical benchmark for assessing operational standards in the industry.
International players are also redefining the competitive boundaries. Falkenhahn AG continues to innovate within the EPAL and wooden pallet solutions space, while PGS Group in France provides standard and custom wooden pallets and packaging solutions, emphasizing versatility in European markets. Meanwhile, Challenger Pallet focuses on sustainability-driven offerings, including custom and heat-treated pallets, alongside repaired and remanufactured options. Their commitment to new tree planting partnerships reflects a broader industry shift toward environmental stewardship that is increasingly influencing procurement criteria.
Regional specialization remains a potent strategy. Wooden Pallets LTD, operating out of Silsbee, Texas, produces over 15,000 pallets daily across facilities in Texas and Louisiana, demonstrating the enduring importance of localized production to meet demand fluctuations. Troymill Wood Products in Ohio serves the wholesale pallet and lumber market with a strong emphasis on compliance, offering in-house heat-treated pallets that meet ISPM-15 standards for export shipments. Similarly, Kamps Pallets distinguishes itself through enterprise-wide sustainability initiatives, including Zero Waste Certification, highlighting how environmental credentials are becoming a core component of brand value and operational efficiency.
Regulatory and Sustainability Dynamics
The strategic landscape for 2026 is heavily influenced by a complex web of regulations and sustainability imperatives. Compliance is no longer merely a checkbox; it is a market access requirement and a driver of innovation. A pivotal regulatory development is the entry into force of the EU Deforestation Regulation (EUDR). For large companies, compliance is required by December 30, 2025, with small companies following by June 30, 2026. New pallets, classified under HS code 4415, now require a due diligence statement proving deforestation-free origin. This regulation introduces new layers of traceability and documentation that will reshape sourcing strategies and cross-border trade flows.
Simultaneously, ISPM-15 compliance remains mandatory for export pallets. Manufacturers and exporters must ensure that wooden pallets are heat-treated and stamped to meet international phytosanitary requirements. Companies like Troymill Wood Products have built their value proposition around this compliance, offering in-house treatment capabilities that streamline the export process. As global trade volumes recover and reconfigure, the ability to navigate phytosanitary standards efficiently becomes a critical differentiator for logistics providers and pallet suppliers alike.
Advocacy and industry collaboration are yielding tangible results. In May 2026, the National Wooden Pallet and Container Association secured a significant victory by obtaining an exclusion for wooden pallets from California's new Extended Producer Responsibility (EPR) scheme. This outcome demonstrates the power of collective industry action in shaping regulatory frameworks to ensure that wood pallets, which are inherently reusable and recyclable, are not unfairly burdened by waste management policies designed for other materials. Furthermore, in February 2025, the Pallet Foundation awarded a historic grant to the National Wooden Pallet and Container Association to advance U.S. softwoods research. This investment in material science underscores the industry's commitment to optimizing raw material utilization and enhancing performance characteristics.
Segmentation and Structural Insights
Understanding the structural composition of the market is essential for targeted strategy. While specific regional and application breakdowns are detailed in the full report, the broader segmentation patterns reveal clear areas of focus. The market is divided across distinct product types, including softwood pallets, hardwood pallets, and a growing segment of recycled and engineered wood pallets. Each category presents unique value propositions, cost structures, and application suitability.
Softwood continues to dominate as a raw material backbone. Historical data indicates that softwood lumber accounted for a substantial majority of the lumber used in U.S. wooden pallet and container production. This reliance reinforces the importance of sustainable forestry management and supply chain resilience for softwood suppliers. In terms of dimensions, the 48 x 40 pallet size held a dominant new pallet market share historically, reflecting standardization benefits and compatibility with existing logistics infrastructure. However, the demand for custom sizes and specialized configurations persists in specific industrial and manufacturing contexts.
The application landscape spans diverse sectors, including logistics and transportation, manufacturing, retail and e-commerce, food and beverages, and other specialized uses. Each vertical imposes distinct requirements regarding durability, hygiene, load capacity, and handling cycles. For example, the retail and e-commerce segment often demands high volumes of standardized pallets to support rapid distribution, while manufacturing may require tailored solutions for specific machinery or production line constraints. The report delves deeply into these application dynamics, helping clients identify high-growth niches and understand the competitive intensity within each segment.
Operational Resilience and Waste Management
Sustainability metrics and waste management data provide critical context for the circular economy narrative. Contrary to perceptions of high waste generation, industry data reveals that only a small fraction of wood landfilled by municipal solid waste landfills and construction and demolition landfills consists of wood pallets. This statistic speaks to the high recovery, reuse, and recycling rates inherent in the pallet ecosystem. Companies with robust repair and remanufacturing capabilities, such as Challenger Pallet and Kamps Pallets, are well-positioned to capitalize on these circular flows, reducing material costs and enhancing environmental profiles. The shift toward recycled and engineered wood pallets is not just a sustainability trend; it is an economic opportunity to leverage alternative material streams and extend asset lifecycles.
Why This Report is Essential for 2026 Decision-Making
The Wood Pallet Market research from PW Consulting is designed to translate these complex dynamics into actionable intelligence. The report provides a granular examination of market size, growth trajectories, and segmentation structures that enable precise market sizing and forecasting for corporate planning teams. Beyond the numbers, we analyze the competitive profiles of key players, their strategic moves, and the implications of recent developments such as the UFP Industries acquisitions and the regulatory victories by industry associations.
Wood Pallet Market
Stakeholders will gain access to detailed assessments of regulatory risks, including the implications of EUDR and ISPM-15, along with guidance on compliance pathways. The study also explores raw material dynamics, regional demand drivers, and the evolving role of sustainability in procurement decisions. By mapping the competitive concentration and identifying the strategic positioning of leaders like PalletOne, Millwood, Falkenhahn, and others, the report offers a clear view of the barriers to entry, partnership opportunities, and potential threats.
We invite industry executives, investors, and supply chain leaders to leverage this comprehensive intelligence to sharpen their strategic focus. The full report contains the complete segmentation data, deep-dive regional analysis, detailed company profiles, and comprehensive forecasts that are essential for making informed decisions in 2026 and preparing for the years ahead. Access the full market research to unlock the detailed insights and secure a competitive edge in the evolving wood pallet landscape.
For detailed analysis of this topic, please visit the official page: Wood Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


