



PW Consulting: Paraffin Wax Market Hits $9.65B in 2025, Forecasts 5.6% CAGR to $14.13B by 2032

Paraffin Wax Market Intelligence Report: Strategic Forecasts and Competitive Dynamics 2026–2032
The global paraffin wax market stands at a pivotal inflection point as industries navigate shifting regulatory frameworks, evolving material specifications, and intensifying competitive pressures. Our latest market research deliverable provides executives, procurement leaders, and strategic planners with a comprehensive, data-anchored foundation for navigating the 2026 landscape and beyond. This introduction outlines how the study translates macro trajectories into actionable intelligence, positioning decision-makers to capture growth while mitigating structural risks across supply chains, product development, and geographic expansion.
Market Trajectory and Long-Term Growth Architecture
Historical performance across the 2020–2025 cycle demonstrates consistent demand expansion, with revenue progressing from roughly 7.35 billion USD at the start of the period to 9.65 billion USD by the 2025 baseline. This steady ascent reflects sustained utilization across traditional and specialized channels, underpinned by incremental capacity adjustments and broadening downstream adoption. Our forward-looking model extends through 2032, projecting a compound annual growth rate of 5.6 percent that lifts market revenue toward 14.13 billion USD by the final forecast year.
Forecast intervals for 2026 through 2030 illustrate a measured but uninterrupted climb, with each successive period capturing incremental value creation driven by refined manufacturing outputs, medical and laboratory-grade adoption, and packaging-related consumption. The trajectory is neither linear nor uniform across categories, which is precisely why our analytical framework isolates the structural drivers that will determine which participants secure margin resilience and which face compression from commoditization or compliance overhead.
Structural Segmentation: Where Value and Complexity Intersect
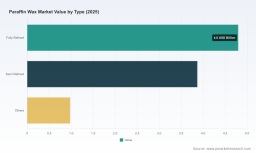
The market’s composition is shaped by three interlocking dimensions—product refinement thresholds, geographic distribution networks, and end-use deployment patterns. Fully refined and semi refined variants each command substantial share, yet their operational implications diverge sharply when evaluated against purification standards, melting-point stability, and downstream processing requirements. The residual category further reflects niche utilization pathways that often depend on specialized formulation parameters.
Geographic revenue concentration reveals mature demand centers alongside emerging corridors that are gradually scaling procurement volumes. Advanced industrial ecosystems continue to anchor baseline consumption, while regions in early-stage capacity building and import-dependent supply structures present differentiated growth risks and partnership opportunities. Application demand inherits this same structural complexity, with traditional usage streams maintaining broad volume presence, packaging-related requirements expanding through regulatory and sustainability mandates, and cosmetics and personal care segments leveraging refined waxes for formulation stability and user experience enhancements.
Our segmentation analysis deliberately avoids superficial percentage breakdowns in favor of a systematic evaluation of substitution thresholds, compliance friction points, and regional procurement behaviors. These outputs equip leadership teams with the granularity necessary to prioritize resource allocation, calibrate capacity commitments, and identify the applications or locations where competitive moats can be constructed before saturation accelerates.
Competitive Landscape and Strategic Positioning
The market’s competitive architecture reflects a blend of specialized medical-grade suppliers, histology-focused consumables manufacturers, and broader industrial producers that influence pricing, availability, and technical standard-setting across the value chain. A set of established entities illustrates the bifurcated nature of current competition. Companies such as WR Medical Electronics Co., Epredia, Polysciences Inc., CellPath Ltd., Poth Hille & Co. Ltd., Citotest Scientific Co. Ltd., and Biosharp each occupy distinct nodes within the ecosystem, balancing formulation precision, laboratory compatibility, and distribution reach.
The medical and laboratory-focused segment demonstrates particular intensity as procurement teams increasingly prioritize traceability, standardized documentation, and adherence to quality management expectations. Suppliers in this space differentiate not merely through volume, but through grade consistency, application compatibility, and the ability to support regulated workflows without introducing contamination risk or processing delays. Meanwhile, broader refining and chemical enterprises continue to shape availability dynamics by aligning upstream process modernization with specialty wax output, effectively influencing both cost structures and supply reliability for downstream converters and end manufacturers.
Our competitive analysis maps product portfolio breadth, geographic servicing capabilities, and strategic realignment activities to expose where consolidation pressure is likely to intensify. The report details how firms are positioning their refinement capabilities, laboratory-grade portfolios, and compliance documentation against buyer expectations, and identifies the structural advantages that separate market leaders from price-takers in multi-source procurement environments.
Recent Industry Developments Reshaping Market Momentum
Recent operational and product-level moves underscore the market’s transition toward higher specification demands and more disciplined supply practices. Product delivery activity in the medical-grade space has highlighted the importance of reliable cross-border fulfillment for hospital pathology departments and third-party testing laboratories, reinforcing the need for logistics consistency and batch traceability. Concurrently, major refining and petrochemical organizations have advanced facility upgrades and modernization initiatives designed to expand specialty wax output, signaling supply-side investment in higher-value production streams rather than bulk commodity routing alone.
Product portfolio expansions have also targeted low-carbon and specialized application pathways, reflecting buyer sensitivity to sustainability considerations in packaging and medical device contexts. Parallel catalog and specification updates within the therapeutic and professional-use segment demonstrate continued alignment with recognized quality and regulatory expectations, ensuring that refill options and device-compatible inputs maintain compatibility with established compliance standards. These developments collectively illustrate a market in which technical differentiation, documentation rigor, and capacity alignment increasingly determine commercial outcomes.
Paraffin Wax Market
Worldwide Paraffin Phase Change Material (PCM) Market
Regulatory, Material, and Operational Dynamics
Market behavior cannot be separated from the compliance environment and operating cost structures that shape procurement decisions. Paraffin wax applications used in occupational therapy and related therapeutic settings operate within defined classification frameworks that distinguish first-aid heat treatments from procedures requiring formal medical recordkeeping, influencing how providers structure procurement and usage protocols. At the same time, any paraffin wax destined for medical device consumables or histology workflows must satisfy international quality and traceability expectations, with ISO 13485 serving as a critical benchmark for documentation, quality control, and supply chain accountability.
Material cost and operational considerations further complicate segment economics. Facilities engaged in medical-grade or histology-related utilization must account for sanitization protocols, disposable liner requirements, and routine replacement cycles, all of which contribute to total cost of ownership beyond base material pricing. Medical-grade paraffin wax itself is characterized by elevated purity, stable melting behavior, and favorable permeability, attributes that directly support tissue embedding, slide preparation, and cellular pathology workflows. These technical and compliance factors interact with procurement strategy, making specification clarity and supplier qualification decisive variables in vendor selection and long-term contracting.
Strategic Decision Framework for 2026 and Beyond
Translating market intelligence into competitive advantage requires a structured approach that aligns market trajectory with internal capability and risk tolerance. Our report is designed to support that translation across three core planning dimensions. First, it delivers a decision-grade forecast architecture that connects baseline momentum to multi-year projections, enabling leadership teams to evaluate capacity timing, inventory positioning, and regional prioritization with greater confidence. Second, it breaks down segmentation complexity in a way that reveals substitution pathways, specification sensitivity, and demand concentration patterns without relying on superficial splits that obscure operational realities.
Third, the study incorporates competitive and developmental intelligence to help organizations anticipate supplier behavior, gauge consolidation risk, and identify partnership or sourcing opportunities before shift patterns become fully priced into the market. Combined with regulatory and operating-cost context, this provides a practical basis for scenario planning across procurement, product development, and market-entry decisions. In an environment where quality documentation, traceability, and application compatibility increasingly determine commercial viability, the ability to distinguish structural growth from temporary fluctuation is a strategic necessity.
Report Scope and Analytical Coverage
This research deliverable is structured to support both executive briefing and operational planning. It integrates historical performance, forward projections, segmentation logic, competitive profiling, and recent development tracking into a single analytical framework that can be applied across strategy, procurement, and business development functions. The study includes detailed examination of refinement categories, application pathways, and regional demand dynamics, along with supplier positioning that highlights differentiation drivers, compliance alignment, and distribution reach.
It also incorporates development tracking across facility modernization, portfolio expansion, product delivery activity, and specification updates, allowing readers to connect discrete events with broader market momentum. Operational and regulatory context is embedded throughout, ensuring that market sizing and competitive assessment are interpreted within the practical constraints that shape end-use requirements and total cost considerations. The result is a comprehensive reference document designed to support high-stakes decisions in a market where precision, traceability, and strategic timing increasingly define competitive outcomes.
Organizations seeking to align near-term sourcing and product decisions with longer-horizon growth trajectories will find the full dataset, segmentation architecture, and competitive mapping essential to disciplined planning. This report provides the analytical foundation required to convert market momentum into defensible strategy throughout the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


