



PW Consulting Report: Food Service Equipment Market Hits $41.47B in 2025, Poised for 7% CAGR Through 2032

The Strategic Value of the 2026 Food Service Equipment Market Intelligence Report
As the global foodservice industry navigates a period of structural transformation, equipment procurement has evolved from a tactical expense to a strategic lever. The latest comprehensive study by PW Consulting on the Food Service Equipment Market offers decision-makers a rare, data-grounded compass for navigating the forecast window from 2026 through 2032. Built on a rigorous historical baseline spanning 2020 to 2025 and calibrated to forward-looking demand indicators, this research translates macroeconomic momentum, competitive realignments, and operational cost pressures into actionable intelligence tailored for executives, supply chain planners, and capital allocation teams.
For 2026 enterprise strategy, the market conversation has shifted decisively toward resilience, efficiency, and capital optimization. The industry is operating under a dual narrative: sustained revenue expansion coexisting with intensifying margin scrutiny, labor cost escalation, and raw material volatility. Our report captures this complexity without oversimplifying it, providing the structural clarity required to time investments, prioritize categories, and anticipate competitor moves. Rather than presenting a static snapshot, the analysis maps the trajectory of market growth, identifies concentration patterns, and outlines the operational and regulatory forces that will dictate procurement velocity over the next seven years.
Macro Trajectory: Mapping the Growth Arc and Capital Allocation Window
The historical record demonstrates a clear and accelerating expansion pattern. Between 2020 and 2025, the global market for foodservice equipment advanced from approximately 29.6 billion USD to 41.5 billion USD, reflecting consistent demand recovery, channel stabilization, and an expanding base of commercial kitchen operators. More importantly, the forecast period from 2026 to 2032 positions the market on a sustained upward trajectory, with projected revenue reaching 44.5 billion USD in 2026 and continuing to climb toward the mid-60 billion USD range by 2032.
This growth curve is not merely a function of volume recovery; it reflects structural demand drivers that favor deliberate, phased investment. The forecast period coincides with a phase in which labor economics, energy compliance expectations, and operational throughput requirements increasingly influence equipment specification decisions. For 2026 decision-makers, this trajectory carries two immediate implications. First, it validates a medium-to-long-term capital planning horizon rather than opportunistic purchasing. Second, it signals that the most consequential procurement decisions will be those that balance upfront cost with downstream efficiency, maintenance predictability, and regulatory alignment.
The compounding annual growth rate embedded in the forecast underscores a market that continues to expand at a meaningful pace even as operators tighten capital discipline. That combination creates a strategic tension that the report addresses directly: how to capture growth opportunities without overextending operational budgets or misreading regional and segment-level demand signals. The analysis is structured to help executives differentiate between broad market momentum and the narrower pockets of acceleration that should drive category-specific investment.
Competitive Architecture: Concentration, Positioning, and Strategic Implications
One of the most valuable elements of the report is its dissection of the competitive landscape. The market is not fragmented in a way that rewards undifferentiated pricing competitions; instead, it exhibits meaningful concentration among manufacturers that combine scale, brand breadth, and category specialization. The data indicates that the top three players collectively account for 38.5 percent of the market, while the top five represent 52.6 percent. Such concentration shapes channel dynamics, pricing agency, and the strategic weight of partnerships, service networks, and product roadmaps.
The competitive field includes organizations with distinctly different strategic postures. Some manufacturers compete on broad portfolio coverage and multi-brand architecture, spanning ranges, ovens, refrigeration, dishwashing systems, and ancillary kitchen infrastructure. Others differentiate through category leadership, leveraging deep engineering focus on specific equipment classes such as combi-steam ovens, ice production systems, beverage equipment, or heavy-duty mixing and cooking platforms. A third competitive vector is corporate ownership and consolidation activity, which influences product integration, regional distribution reach, and strategic prioritization across North America, Europe, and Asia Pacific.
Food Service Equipment Market
Recent developments highlight the pace and direction of competitive maneuvering. Mid-2025 product launches have targeted cost-conscious operators with refreshed refrigeration offerings, while facility expansions and experiential customer centers have reinforced service, demonstration, and specification support capabilities. Partnerships with institutional bodies have opened grant-assisted upgrading pathways for school meal kitchens, reflecting a broader pattern in which manufacturers increasingly align product strategy with public-sector and community nutrition programs. Leadership transitions in major multinational operations point to renewed focus on North American execution and portfolio alignment. Meanwhile, trade show demonstrations of energy-recovery systems illustrate the growing prominence of operational efficiency as a competitive differentiator rather than a compliance afterthought.
For 2026 strategy teams, this competitive architecture matters because it determines the realistic set of procurement alternatives, negotiation leverage, and vendor dependency risks. The report does not simply list competitors; it evaluates how portfolio scope, ownership structures, and recent strategic moves influence market behavior. That perspective allows buyers and investors to interpret supplier announcements with greater contextual accuracy and to anticipate which firms are likely to expand capacity, reprice offerings, or redirect innovation investment.
Operational and Regulatory Forces Reshaping Procurement Logic
Market size and competitive structure tell only part of the story. The real strategic value of the report emerges in its treatment of the forces that alter equipment selection criteria, total cost of ownership, and deployment timing. One of the most prominent is the labor cost trajectory in food services and drinking places. Rising average hourly earnings between 2025 and early 2026 have intensified the operational case for labor-saving equipment, automated food preparation, and holding solutions that reduce hands-on station time. In this environment, equipment is increasingly evaluated not only for throughput and durability but also for its contribution to workforce productivity and shift scalability.
Food Processing Equipment Market
Parallel to this, raw material dynamics continue to influence manufacturing economics. Volatility in steel and aluminum markets affects the cost structure of equipment components and, by extension, the pricing stability and lead-time predictability that operators rely on when planning capital projects. The report situates these material pressures within a broader procurement rhythm, helping organizations anticipate where cost variability may be absorbed by manufacturers, passed through to buyers, or mitigated through design engineering and supply chain adjustments.
Regulatory expectations also form a critical layer of the strategic landscape. ENERGY STAR certification and similar energy-efficiency frameworks have become practical gateways to utility incentives and compliance with evolving efficiency standards for dishwashers, ice machines, fryers, and other commercial kitchen assets. At the same time, equipment must satisfy electrical safety, gas safety, pressure vessel, and food contact material requirements to secure market access. These requirements are not static checkboxes; they shape product roadmaps, specification guidelines, and the cost-benefit calculus of choosing one equipment category over another.
The report also addresses reimbursement pathways that affect institutional demand. In the school nutrition segment, for example, equipment grants tied to USDA meal program upgrades can meaningfully offset capital costs for kitchen modernization projects. Recognizing where grant mechanisms, incentive structures, and compliance requirements intersect enables operators and contractors to design procurement plans that align with available financial support and regulatory timelines. For 2026 planning, this is especially relevant because public-sector and institutional budgets often move on different calendar cycles than commercial operators, and misreading those cycles can lead to missed windows or suboptimal specification choices.
What the Report Delivers: Operational Content for 2026 Decision-Making
This study is engineered for practical use rather than abstract commentary. It integrates historical performance, forward forecasts, competitive context, and market dynamics into a single framework that can be directly applied to budgeting, sourcing, and investment planning. The report content is organized to support several high-value decisions.
First, it provides a structured view of the market by type, application, and geography, allowing readers to identify where demand is concentrated and how segment-level priorities differ. Rather than presenting uncontextualized splits, the analysis interprets these dimensions in relation to operational realities, such as the differing equipment intensity of full-service restaurant environments versus quick-service formats, and the implications of institutional, catering, and hospitality use cases for equipment specification and replacement cycles.
Second, the report examines the competitive set with enough granularity to inform vendor selection and partnership strategy. It profiles leading manufacturers across multiple categories and geographies, noting their core product competencies, brand footprints, and recent strategic actions. This enables readers to map competitors not as isolated names but as participants in a competitive system defined by portfolio breadth, specialization, regional execution, and corporate ownership.
Third, the study incorporates the latest industry developments and regulatory signals that influence near-term planning. Product launches, facility investments, partnership activity, leadership transitions, and trade show initiatives are evaluated for their strategic relevance, while regulatory, material, and labor-market facts are integrated into the broader demand narrative. The goal is to equip decision-makers with the context needed to distinguish transient noise from durable trend shifts.
Fourth, the report addresses total cost of ownership considerations that often get overlooked in category-level discussions. Energy efficiency eligibility, labor productivity impact, maintenance expectations, and compliance readiness all have implications for long-term operating expense. By connecting these factors to market structure and procurement behavior, the analysis helps organizations evaluate equipment decisions with a fuller financial lens. For 2026 strategy, that lens is essential because capital availability, operational efficiency, and regulatory alignment increasingly converge in the same purchasing decision.
Finally, the report is designed to be referenced, not merely read. Its structure supports scenario planning, category prioritization, and procurement scheduling. Whether an organization is evaluating a kitchen modernization program, planning a multi-site rollout, assessing vendor consolidation opportunities, or modeling category growth under different labor and energy assumptions, the research provides the framing necessary to reduce uncertainty and improve decision quality.
How to Use This Intelligence for 2026 Planning
The most effective use of this report is to align market intelligence with an organization's procurement calendar, capital constraints, and operational goals. For manufacturers and distributors, the analysis supports product portfolio prioritization, geographic focus, and competitive positioning. For operators and contractors, it informs specification strategy, replacement-cycle timing, and energy-efficiency investment decisions. For investors and market entrants, it clarifies concentration dynamics, growth concentration, and the practical barriers created by regulatory and supply-chain requirements.
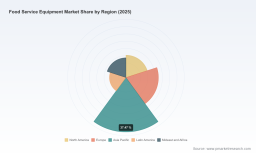
Because the study deliberately abstracts away segment-level percentage detail and specific regional or application amounts in this overview, the complete dataset remains essential for precise planning. The published version provides the granular breakdowns, comparative context, and working-level detail required to translate strategic direction into operational execution. Decision-makers who rely only on summary-level figures risk missing the segment-specific signals that determine where and when capital should be deployed.
Conclusion: A Deliberate Framework for a Changing Market
The Food Service Equipment Market in 2026 is not simply expanding; it is being reshaped by labor economics, energy compliance, raw material variability, and a competitive landscape in which concentration and specialization both matter. The PW Consulting market research is designed to help organizations navigate that environment with confidence by combining historical rigor, forward forecast discipline, and practical competitive analysis into a single decision-support resource.
The report offers the breadth and depth needed to inform capital allocation, procurement strategy, and competitive positioning without overloading readers with uncontextualized data. Its true value lies in helping organizations distinguish durable growth from temporary momentum and to align equipment strategy with the operational realities that will define the next several years. For those preparing for 2026 and beyond, the complete report provides the detailed segment and regional intelligence required to move from strategic direction to informed execution.
For detailed analysis of this topic, please visit the official page: Food Service Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


