



PW Consulting Report: Cs Beam and Hydrogen Maser Clocks Market Hits USD 40M in 2025, Projects 6.98% CAGR

Navigating the Precision Timing Revolution: Strategic Insights into the Cs Beam and Hydrogen Maser Atomic Clocks Market (2026–2032)
In an era where nanosecond precision dictates the reliability of global navigation, telecommunications, financial trading, and critical infrastructure, atomic clock technology has evolved from a specialized scientific instrument into a strategic asset class. The Cs beam and hydrogen maser atomic clocks market stands at a pivotal inflection point as nations, defense contractors, and telecommunications operators confront mounting threats from GNSS disruptions, space-based timing degradation, and escalating cybersecurity vulnerabilities. This comprehensive market intelligence study, anchored in historical performance from 2020 through 2025 and projecting forward to 2032, provides decision-makers with the analytical rigor required to navigate a highly concentrated yet rapidly commercializing landscape. By examining macro trajectory, competitive dynamics, technological substitution patterns, and regulatory catalysts, this report equips strategic planners, procurement leaders, and investment committees with actionable foresight for 2026 and beyond.
Market Trajectory and Structural Foundations
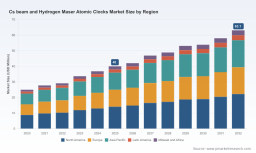
The market has demonstrated consistent expansion over the historical review period, climbing from 25.0 million USD in 2020 to an estimated 40.0 million USD in 2025. This growth trajectory reflects a compound annual growth rate of approximately 6.98 percent across the forecast window extending through 2032, with revenue projections indicating a continued upward arc driven by next-generation timing infrastructure, sovereign GNSS resilience initiatives, and the proliferation of precision-dependent applications in telecommunications and space exploration. The forecast period reveals a market that is scaling steadily rather than experiencing volatile spikes, underscoring the deliberate, engineering-intensive nature of atomic clock deployment and the long lifecycle characteristics of primary reference timing systems. By 2032, total market revenue is expected to surpass 60 million USD, illustrating sustained institutional and commercial demand for frequency standards that deliver unparalleled long-term stability and traceability to international timekeeping frameworks.
Several structural factors underpin this expansion. First, the growing deployment of optical cesium beam architectures and enhanced hydrogen maser platforms is broadening the addressable market beyond traditional national metrology laboratories and defense enterprises into commercial data centers, power grid synchronization networks, and next-generation telecommunications infrastructure. Second, the industry’s shift toward sovereign timing capabilities has accelerated procurement cycles, as governments and critical infrastructure operators seek to reduce reliance on vulnerable satellite-based timing signals. Third, the maturation of manufacturing ecosystems and the establishment of dedicated production lines for high-performance hydrogen masers are gradually improving supply chain reliability, reducing lead times, and expanding the commercial viability of these precision instruments. Together, these drivers create a durable growth foundation that strategic stakeholders can leverage to align product roadmaps, capacity planning, and partnership strategies.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate-to-high concentration profile, with the top three participants collectively commanding a significant share of total revenue and the top five firms accounting for approximately half of the overall market. This concentration reflects the capital-intensive nature of precision timing research, the stringent certification requirements associated with primary frequency standards, and the long-standing intellectual property positions held by established players. However, the competitive environment is not static. Recent corporate developments underscore a sharp focus on manufacturing scalability, product diversification, and strategic deployment of atomic clock systems in high-stakes operational contexts.
- Microchip Technology Inc., headquartered in Chandler, Arizona, continues to reinforce its leadership in cesium beam frequency standards and active hydrogen maser solutions. The company’s MHM-2020 active hydrogen maser and 5071B cesium beam frequency standard have become reference architectures for metrology, telecommunications, and satellite applications requiring accuracies at the 5×10⁻¹³ level. In April 2026, the company inaugurated a new manufacturing facility in Tuscaloosa, Alabama, purpose-built to expand MHM-2020 production capacity, reduce delivery lead times, and address rising demand for independent timing systems in national infrastructure protection programs.
- Oscilloquartz SA, based in Neuchâtel, Switzerland, has extended its footprint through the OSA 3230 series of optical cesium beam atomic clocks and hydrogen maser solutions engineered for enhanced short-term stability via its ESTU module. The firm serves telecommunications, defense, and precision timing customers seeking compact, high-reliability architectures that bridge the performance gap between legacy cesium systems and premium hydrogen masers.
- Safran Electronics & Defense, operating from Paris, France, has emerged as a decisive player in spaceborne and ground-based atomic clock deployments. The Space Hydrogen Maser (SHM) powered the ESA ACES atomic clock ensemble aboard the International Space Station, achieving record stability for global timekeeping and deep-space applications. In September 2025, an all-European maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions and signaling a broader push toward sovereign timing sovereignty in deep-space communications.
- Adtran Inc., headquartered in Huntsville, Alabama, has strengthened its positioning through the integration of Oscilloquartz optical cesium beam clocks with ESTU modules, delivering hydrogen-maser-comparable short-term stability for data centers, power utilities, and defense PNT (positioning, navigation, and timing) applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, cost-effective optical cesium beam solutions with a 10-year lifespan and improved holdover capabilities designed to support telecom and infrastructure modernization efforts.
These developments reflect a competitive environment characterized by parallel strategies: vertical expansion into dedicated manufacturing capacity, cross-company technology integration, space mission validation, and product launches targeting cost-sensitive yet performance-critical segments. For buyers and partners, this landscape presents both consolidation opportunities and fragmentation risks. Organizations that map the competitive dynamics with precision can anticipate supply shifts, evaluate vendor lock-in exposure, and identify collaborative pathways that align with long-term timing resilience objectives.
Industry Dynamics: Regulation, Certification, and Technological Substitution
The market’s trajectory is increasingly shaped by regulatory milestones, standardization activities, and certification events that redefine performance benchmarks and procurement criteria. A notable catalyst occurred in April 2025, when the National Institute of Standards and Technology certified the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard, calibrated against hydrogen masers to improve UTC traceability and metrology applications. This certification effectively signals the transition away from legacy HP 5071A models in national metrology laboratories and establishes a new reference baseline that influences downstream procurement specifications across government and commercial sectors.
Simultaneously, the ESA ACES mission’s selection of Safran’s Space Hydrogen Maser in April 2025 underscores the strategic importance of exceptional short-term frequency stability for spaceborne applications. The deployment of an all-European maser active hydrogen maser at the New Norcia deep-space ground station in September 2025 further illustrates how certification and mission validation are converging to support sovereign deep-space tracking and GNSS resilience. These events are not isolated achievements; they represent structural shifts in how timing infrastructure is evaluated, deployed, and protected against environmental and geopolitical disruptions.
On the commercial side, Adtran’s June 2025 launch of Oscilloquartz optical cesium beam clocks with ESTU modules demonstrates a deliberate push to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a more accessible cost profile. This product evolution reflects a broader industry dynamic: the compression of performance gaps between cesium beam and hydrogen maser technologies, driven by module-level enhancements, improved holdover characteristics, and extended operational lifespans. As these dynamics mature, procurement teams must reassess the traditional dichotomy between cost and stability, particularly when evaluating deployment scenarios that demand rapid recovery from signal loss, long-duration holdover, or stringent synchronization tolerances.
Cs beam and Hydrogen Maser Atomic Clocks Market
What This Research Delivers: Operational Intelligence for 2026 Decision-Making
This market research study is designed as a decision-support toolkit rather than a static data summary. It provides a multi-layered examination of the Cs beam and hydrogen maser atomic clocks market, translating complex technical, commercial, and regulatory interdependencies into structured intelligence that can be operationalized across strategy, procurement, R&D, and investment functions. The report integrates historical performance data, forecast modeling, segment-level analysis, and competitive profiling to deliver a comprehensive view of market directionality and actionable differentiation points.
Core Analytical Components
- Macro market sizing and forecast modeling that contextualizes historical growth from 2020 through 2025 and projects revenue expansion through 2032, enabling scenario-based planning for capacity allocation, investment prioritization, and demand forecasting.
- Segment-level evaluation across technology types and regional markets, offering insight into how cesium beam and hydrogen maser architectures are positioned relative to one another, where adoption momentum is concentrating, and which demand drivers are most influential in shaping procurement strategies.
- Competitive profiling of incumbent and emerging participants, including corporate headquarters, product portfolios, accuracy and stability specifications, application footprints, and recent strategic developments that signal shifts in manufacturing scale, technology roadmaps, and market emphasis.
- Regulatory, certification, and standardization tracking that maps the impact of metrology lab transitions, space mission deployments, ground station operations, and product certifications on downstream procurement requirements and vendor qualification criteria.
- Market concentration and structural analysis that evaluates the implications of top-three and top-five share distribution for pricing dynamics, supply chain resilience, and partnership opportunities in a market where incumbency and certification heritage carry significant weight.
- Application-driven demand assessment that connects timing performance requirements to end-use environments—including telecommunications synchronization, defense PNT resilience, power grid stability, data center infrastructure, satellite operations, and deep-space communications—enabling stakeholders to align product strategy with real-world operational constraints.
Each component is constructed to support practical decision-making. Procurement leaders can use the segmentation and competitive profiling modules to evaluate supplier qualification criteria, benchmark performance specifications, and anticipate supply continuity risks. R&D and product management teams can leverage the regulatory and certification tracking sections to align development roadmaps with evolving metrology standards and space mission validation pathways. Strategy and corporate development functions can draw on the concentration analysis, regional demand signals, and technology substitution dynamics to identify partnership targets, geographic expansion priorities, and investment allocation frameworks.
Strategic Imperatives for 2026 and Beyond
As the market advances toward 2032, several strategic imperatives emerge for organizations operating within or adjacent to the precision timing ecosystem. First, sovereign timing resilience is transitioning from a policy aspiration to an operational requirement, and organizations that proactively align their timing infrastructure with independent, high-stability atomic clock solutions will be better positioned to mitigate GNSS disruption risks and comply with evolving national security and critical infrastructure mandates. Second, the convergence of optical cesium beam enhancements and hydrogen maser performance characteristics is reshaping the value proposition across price-performance tiers, requiring buyers and suppliers alike to reassess specification thresholds, total cost of ownership, and lifecycle support commitments. Third, manufacturing capacity expansions and dedicated production lines are gradually improving supply reliability, but lead time management, component sourcing, and qualification lead times remain critical considerations for deployment planning.
Fourth, space mission validation and deep-space ground station deployments are establishing new reference points for performance and reliability, creating pull-through effects that influence terrestrial procurement specifications and vendor evaluation criteria. Fifth, market concentration implies that strategic partnerships, long-term supply agreements, and dual-sourcing strategies may be necessary to balance performance requirements with supply chain resilience. Organizations that integrate these imperatives into their planning cycles will be better equipped to navigate a market that rewards technical precision, regulatory alignment, and strategic foresight in equal measure.
Conclusion: From Insight to Action
The Cs beam and hydrogen maser atomic clocks market is defined by its technical rigor, its growing strategic importance, and its steady expansion from specialized metrology and defense applications into broader commercial and infrastructure domains. The historical performance from 2020 through 2025 establishes a credible growth baseline, while the forecast through 2032 signals a market that continues to scale in response to sovereign timing initiatives, space mission deployments, telecommunications modernization, and critical infrastructure synchronization requirements. Competitive dynamics remain shaped by incumbency, certification heritage, and manufacturing scale, yet recent facility expansions, product launches, and mission validations demonstrate that the landscape is actively evolving.
For executives, procurement leaders, and strategic planners, the imperative is clear: precision timing is no longer a backend technical consideration but a front-line resilience priority. This market research study provides the structured intelligence required to translate that priority into informed decisions—whether those decisions involve vendor selection, technology roadmap alignment, geographic demand assessment, or investment prioritization. To access the full segmentation analysis, regional demand breakdowns, detailed competitive profiles, and forecast scenario modeling that underpin these strategic conclusions, stakeholders are invited to explore the complete report on our platform, where the complete intelligence is available to support your 2026 planning cycle and beyond.
Rubidium Atomic Clock Market
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


