



PW Consulting: Radar Level Transmitters Market Hits $606.11M in 2025, Forecasting $894M by 2032 at 5.69% CAGR

Radar Level Transmitters Market 2026: Strategic Intelligence for Industrial Automation Leaders
The industrial automation landscape is undergoing a profound transformation, driven by stringent regulatory frameworks, the integration of IoT-enabled diagnostics, and a persistent demand for precision in hazardous environments. For stakeholders operating within the process industries, understanding the trajectory of level measurement technology is no longer optional—it is a critical component of capital allocation and operational resilience. PW Consulting is pleased to introduce our comprehensive market research study on the Radar Level Transmitters Market, designed specifically to equip decision-makers with the foresight required to navigate the period from 2026 through 2032.
This report serves as a strategic compass. While the broader industrial sector faces volatility, the radar level transmitter segment demonstrates a resilient growth trajectory grounded in technological maturation and regulatory compliance. Our analysis moves beyond surface-level observations to unpack the underlying mechanics of market expansion, competitive positioning, and the shifting value chain. By leveraging historical data from 2020 to 2025 and projecting forward, we provide a clear picture of where revenue opportunities will concentrate and how technology adoption curves are likely to unfold.
Executive Summary: Market Trajectory and Growth Dynamics
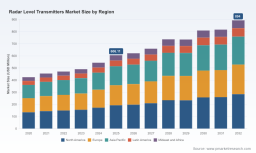
The global market for radar level transmitters has established itself as a cornerstone of modern process instrumentation. Based on historical performance from 2020 through 2025, the market has shown consistent upward momentum, reflecting the broader industrial shift away from traditional gauging methods toward non-contact and advanced guided wave solutions. The market revenue, measured in USD Million, has evolved significantly over the last half-decade, moving from a baseline of 425.0 in 2020 to an estimated 606.11 in 2025.
This historical growth sets the stage for the forecast period. As we look toward 2026, the market is positioned at an estimated 622.3, indicating a continuation of positive momentum. Over the long-term forecast horizon ending in 2032, the market is projected to reach 894.0. This expansion is underpinned by a compound annual growth rate (CAGR) of 5.69 percent during the forecast period. Such a rate suggests steady, sustainable growth rather than speculative bubbles, making this sector attractive for long-term investment and operational planning.
Worldwide Electronic Transmitters Market
The growth is not uniform across all segments. The transition from legacy technologies to 80 GHz radar solutions is a primary driver. For instance, recent industry developments highlight a surge in product launches and certifications tailored to specific regulatory needs. In April 2025, SKE launched its new 80 GHz SKE series radar level transmitter, featuring integrated molding technology aimed at improved performance. Similarly, Emerson launched the Rosemount 1208 wireless non-contacting radar level transmitter in October 2025, focusing on simplified installation for utility and process applications. These launches indicate a market trend toward wireless connectivity, compact design, and ease of integration.
Furthermore, the competitive landscape is characterized by moderate concentration. With a CR3 of 28.5 percent and a CR5 of 53.4 percent, the market remains accessible to a variety of players while maintaining strong leadership from established multinational corporations. This balance suggests that while market leaders hold significant sway, there is ample space for specialized innovators to capture niche segments through differentiation in frequency, certification, or connectivity.
Regulatory Tailwinds and Industry Dynamics
One of the most critical aspects of our analysis focuses on the external forces reshaping demand. Regulation is no longer just a compliance hurdle; it is a market accelerator. In Europe, for example, regulations mandating advanced overfill protection have prompted operators to replace ultrasonic gauges with 80 GHz radar solutions. This shift is not merely technical but operational, as radar offers superior performance in challenging conditions such as vapor, dust, and turbulence.
Simultaneously, methane-emission rules in Europe require tighter tank-gauging accuracy. This regulatory pressure is driving the adoption of 80 GHz radar sensors that can meet these stringent accuracy standards, thereby reducing leaks and environmental impact. In the United States, certification agencies have cleared W-band (76-81 GHz) sensors for process use. This clearance is driving scale economies and eroding price premiums, making advanced technology more accessible to a broader range of industrial clients.
Safety certifications remain a pivotal differentiator. VEGA achieved MCERTS Class 1, WRAS, and Ex ia ATEX certifications for VEGAPULS smart compact radar level sensors in August 2025. This achievement enables use in UK water, wastewater, and hazardous applications, opening up specific verticals that require rigorous safety validation. Similarly, SKE 80 GHz radar level sensors received TÜV NORD SIL2/SIL3 certification, reinforcing the importance of functional safety in critical process industries. These certifications are not just badges; they are prerequisites for entry into regulated markets, and our report details how these compliance landscapes affect market penetration strategies.
Competitive Landscape and Strategic Positioning
The radar level transmitter market is contested by a robust mix of global automation giants and specialized instrumentation firms. The competitive environment is defined by innovation in frequency modulation, wireless connectivity, and integration with broader process control systems. Our report provides an in-depth profiling of key companies that are shaping this landscape, analyzing their product portfolios, strategic moves, and regional strengths.
Radar Level Transmitters Market
Among the leaders, Emerson Electric Co. continues to strengthen its position with the Rosemount series, including the 3408 and 5408 models for liquids, solids, and interface measurement. Their focus on smart diagnostics and wireless options aligns with the industry's move toward Industry 4.0. Endress+Hauser Group maintains a strong foothold with its Micropilot and FMR series 80 GHz radar level transmitters, particularly noted for high precision and hygienic certifications suitable for process liquids, slurries, and solids.
Siemens AG competes with the SITRANS series, emphasizing advanced signal processing and IoT integration for industrial process monitoring. ABB Ltd. supplies both guided wave and non-contact models, including the LWT series, which are critical for total and interface level measurement in harsh environments. VEGA Grieshaber KG remains a key player with the VEGAPULS series, offering 80 GHz radar level sensors with Bluetooth connectivity and compact design, catering specifically to water, wastewater, and hazardous applications.
Other significant contributors include KROHNE Messtechnik GmbH, which introduced the OPTIWAVE 1500 series in October 2025 with expanded models 1520 and 1540, further diversifying their liquid and solids measurement capabilities. Honeywell International Inc. includes radar level transmitters in its broader automation portfolio, while Yokogawa Electric Corporation manufactures solutions tailored for the chemical, oil, and gas industries. Ametek, Inc., through Magnetrol International, offers Pulsar and other radar level transmitters for liquids, slurries, and solids, leveraging its reputation for bulk solids measurement.
The market also includes regional specialists and niche providers such as Automation Products Group (APG) with its TRUE ECHO series explosion-proof pulse radar level transmitters for hazardous locations, and Nivelco Process Control Ltd., which released its 2026 product catalog featuring new PiloTREK WP–200 and WT–300 compact 80 GHz FMCW radar level transmitters. Companies like KOBOLD Instruments, FINE-TEK Co., Ltd., WIKA Alexander Wiegand SE & Co. KG, and Pepperl+Fuchs SE round out the competitive field, each bringing specific strengths in installation ease, sensor portability, or specific industrial verticals. This diversity ensures that while the market is concentrated, it remains dynamic and responsive to varied customer needs.
Product Segmentation and Application Trends
Understanding how the market splits across technology types and applications is vital for targeting sales efforts and procurement strategies. The market is primarily divided into contact and non-contact technologies. Non-contact solutions, including Pulsed Radar and FMCW Radar, continue to gain favor due to their versatility and reduced maintenance requirements compared to contact methods. Guided Wave Radar remains essential for specific interface measurements where precision is paramount.
In terms of application, the demand spans across liquids, slurries, interfaces, and solids. The handling of solids represents a significant portion of the use cases, driven by industries such as mining, cement, and bulk chemical storage. Liquids and slurries remain the traditional stronghold, particularly in oil and gas, water and wastewater, and pharmaceutical sectors. Our report dissects these segments to reveal which combinations of type and application are yielding the highest growth margins.
Recent developments suggest a convergence in technology capabilities. The introduction of 80 GHz sensors across multiple brands—such as KROHNE, VEGA, SKE, and Nivelco—indicates a standardization of high-frequency technology as the benchmark for performance. This standardization allows buyers to compare specifications more easily but also raises the bar for performance across the board. Integration into process control systems is another key trend, with manufacturers ensuring their transmitters communicate seamlessly with PLCs and SCADA systems, reducing engineering time and installation costs.
Strategic Recommendations for 2026 Decision Makers
As enterprises plan their capital expenditures and technology roadmaps for 2026 and beyond, several strategic imperatives emerge from our analysis. First, regulatory compliance should be viewed as a procurement criterion rather than an afterthought. With methane-emission rules and overfill protection mandates tightening, selecting transmitters that already hold necessary certifications like ATEX, SIL, and MCERTS can mitigate project delays and operational risks.
Second, the shift toward wireless and IoT-integrated solutions offers an opportunity to reduce lifecycle costs. The launch of products like the Rosemount 1208 wireless transmitter highlights the industry's direction. Investing in infrastructure that supports wireless connectivity can simplify installation in remote or hazardous locations, where cabling is costly and dangerous.
Third, supply chain resilience and vendor stability are crucial. With a CR5 of 53.4 percent, the top five players hold a majority share, providing a level of stability and support capacity that smaller vendors may struggle to match. However, the presence of agile specialists means that for niche applications, partnering with vendors who offer specialized engineering support can yield better operational outcomes than relying solely on generic large-scale solutions.
Finally, staying abreast of technological standardization is key. As 80 GHz becomes the norm for high-performance applications, legacy 26 GHz systems may face obsolescence pressure in critical environments. Procurement teams should evaluate existing installed bases against these emerging standards to plan for phased upgrades that maintain accuracy and compliance without unnecessary capital waste.
Accessing Comprehensive Market Intelligence
This article provides a strategic overview of the Radar Level Transmitters Market, highlighting the macro-economic trends, regulatory drivers, and competitive shifts that define the landscape. However, the full depth of our research extends far beyond these high-level insights. For organizations seeking to make data-backed decisions regarding market entry, expansion, or procurement, the granular details are essential.
Our complete market research report offers detailed segmentation analysis, historical data tables, and forecast models that quantify growth across specific regions and application verticals. We provide exhaustive company profiles, analyzing strategic moves, product launch timelines, and financial positioning of the key players. Furthermore, the report includes an assessment of market concentration, pricing dynamics, and the specific impact of regulatory changes on supply and demand curves.
To leverage this intelligence for your strategic planning, we invite you to access the full Radar Level Transmitters Market Research report. The comprehensive dataset within will empower your team to identify untapped opportunities, benchmark against competitors, and align your technology investments with the projected market trajectory through 2032. Do not rely on fragmented information when precise intelligence is available. Engage with the full study to secure a competitive advantage in the evolving industrial automation sector.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


