



PW Consulting: Rainscreen Cladding Market Hits $169.2B in 2025, Projected to Hit $293.76B by 2032 at 8.2% CAGR

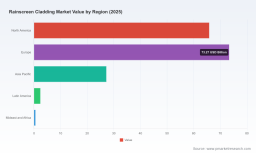
Navigating the Rainscreen Cladding Market: Strategic Intelligence for 2026 and Beyond
The global construction industry stands at a critical juncture where aesthetic ambition must be reconciled with rigorous safety standards, material cost volatility, and evolving regulatory frameworks. Rainscreen cladding systems have emerged as a cornerstone of modern architectural design, offering critical benefits in moisture management, thermal insulation, and fire safety. For executives, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a necessity for capitalizing on growth opportunities while mitigating systemic risks.
PW Consulting's latest comprehensive research on the Rainscreen Cladding Market provides a definitive roadmap for navigating these complexities. This study is designed to empower decision-makers with actionable intelligence, moving beyond surface-level observations to deliver a granular analysis of market drivers, competitive dynamics, and financial forecasts. As we look toward the forecast period extending to 2032, the data reveals a landscape defined by robust expansion, technological innovation, and shifting geopolitical pressures.
Market Trajectory and Financial Outlook
The historical performance of the rainscreen cladding sector underscores its resilience and growing importance in the built environment. Between 2020 and 2025, the market demonstrated consistent upward momentum, driven by a resurgence in construction activity and an heightened focus on building envelope performance. The total market revenue climbed from approximately $114.09 billion in 2020 to an estimated $169.2 billion in 2025. This growth trajectory reflects a compound annual growth rate that signals strong underlying demand across multiple verticals.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is anticipated to reach $181.66 billion in 2026, accelerating toward a projected value of $293.76 billion by 2032. This growth is underpinned by a CAGR of 8.2 percent, indicating that the sector will significantly outpace general construction market averages in many regions. However, realizing this potential requires a nuanced understanding of the forces shaping supply chains, material selection, and regional adoption rates. Our report dissects these variables, offering a clear view of where value is being created and where vulnerabilities lie.
Rainscreen Cladding Market
Product segmentation and Material Shifts
A critical component of strategic planning lies in understanding the divergence in material preferences and application demands. The market is segmented by type into Metal, Fiber Cement, Composite Material, and Ceramic solutions. Metal cladding continues to hold a dominant position, reflecting its versatility and durability, though it faces pressure from raw material cost fluctuations. Fiber Cement and Composite Material segments show substantial uptake, particularly where cost-efficiency and aesthetic flexibility are prioritized. Ceramic solutions, while smaller in volume, are gaining traction in high-end architectural projects demanding specific thermal and fire-resistant properties.
Application-wise, the Residential sector commands the largest share of demand, fueled by urbanization and a shift toward modern, energy-efficient housing designs. Commercial applications follow closely, driven by corporate office builds and retail expansions that prioritize facade branding and weather protection. Institutional and Industrial segments also contribute significantly, often governed by stricter compliance requirements that favor specialized cladding systems. The report provides a deep dive into how these segments interact with regional economic conditions and regulatory environments, allowing stakeholders to identify high-growth niches without exposing themselves to oversaturated or declining sub-markets.
Competitive Landscape: Leaders and Strategic Moves
The market structure is characterized by a mix of established multinational corporations and specialized regional providers. Our analysis identifies key players such as Kingspan Group plc, Rockwool International A/S, Cladding Corp, Alucobond, and Sotech Optima Company as pivotal actors influencing market direction. These companies are not merely competing on price; they are engaging in aggressive innovation and strategic positioning to capture market share.
Kingspan Group plc, headquartered in Ireland, remains a formidable force with its extensive portfolio of ventilated and non-ventilated rainscreen facades and insulation boards. In August 2025, the company announced a new range of eco-friendly rainscreen cladding products meeting stringent environmental standards, signaling a shift toward sustainability as a key differentiator. Similarly, Rockwool International A/S, based in Denmark, has strengthened its position by expanding production capacity in Europe with a new manufacturing facility in September 2025. This move aims to support rising demand for their BBA-approved stone wool insulation boards used in ventilated and sealed rainscreen systems, addressing both performance and supply reliability.
In the Americas, Cladding Corp, located in Camden, New Jersey, continues to serve as a vital provider of drained and back-ventilated systems for terracotta, fiber cement, ceramic, and porcelain panels, offering full engineering support that appeals to complex project requirements. Alucobond, operating from Germany, has focused on innovation in aluminum composite panels designed for pressure-equalized systems. Their strategic partnership with a leading architectural firm in July 2025 highlights a focus on developing innovative cladding solutions for high-rise buildings, where performance and aesthetics intersect. Meanwhile, Sotech Optima Company in the United Kingdom has launched the Optima BrickTech system in February 2025, a fully non-combustible rainscreen system offering the look of traditional brickwork with modern cladding performance, directly responding to fire safety concerns while maintaining design integrity.
The report delves deeper into the competitive dynamics, analyzing market concentration metrics such as CR3 and CR5 percentages to illustrate the balance of power. While these figures indicate a degree of consolidation among top players, there remains significant opportunity for agile competitors who can navigate local regulations and supply chain disruptions effectively.
Industry Dynamics: Regulatory and Economic Headwinds
No strategic assessment is complete without a rigorous examination of the external forces reshaping the market. The regulatory environment has become increasingly stringent, particularly regarding fire safety. In the UK, the government has implemented a complete ban on Metal Composite Material with unmodified polyethylene core in rainscreen cladding for all new buildings under the revised Approved Document B of the Building Regulations. This regulation, coupled with the requirements of the Building Safety Act which mandates stricter testing and certification following the Grenfell Tower inquiry, has fundamentally altered material preferences in the region. Similarly, local building codes in states such as California and New York increasingly mandate non-combustible materials for buildings over four stories, favoring metal and stone wool rainscreen systems.
Worldwide Wall Cladding Market
Economic factors also play a decisive role. Raw material cost volatility presents a significant challenge. Aluminum prices rose by over 30 percent from December 2024 into 2025, while steel prices increased nearly 17 percent, directly raising costs for architectural metal cladding components. These pressures are compounded by trade policy shifts. The US Environmental Protection Agency imposed a 50 percent import tariff on aluminum and steel products under Section 232 tariffs, effective April 2026, increasing costs for imported rainscreen cladding materials. These dynamics create a complex cost environment where pricing strategies, supply chain localization, and material substitution become critical success factors. Our research analyzes how these headwinds impact margins and advises on mitigation strategies.
Scope of Comprehensive Analysis
PW Consulting's Rainscreen Cladding Market report is engineered to provide end-to-end visibility for strategic planning. The study encompasses a detailed analysis of market size and growth forecasts, segmented by region, type, and application, allowing stakeholders to benchmark their performance against broader industry trends. It includes a thorough examination of the competitive landscape, profiling key companies with insights into their product portfolios, recent developments, and strategic initiatives.
Beyond quantitative data, the report offers qualitative insights into market dynamics, including the impact of regulatory changes, raw material price fluctuations, and technological advancements. It provides a review of historical performance from 2020 to 2025 to contextualize current market conditions and validate forecasting models. The forecast period through 2032 is analyzed with scenario-based projections to account for potential disruptions. Additionally, the research explores supply chain structures, identifies barriers to entry, and highlights emerging trends such as the integration of living wall systems and eco-friendly materials. This holistic approach ensures that readers gain a 360-degree view of the market, enabling informed decisions on product development, market entry, partnership formation, and investment allocation.
Strategic Imperatives for 2026 and Beyond
As the market moves into 2026, the convergence of growth opportunities and regulatory constraints demands a proactive stance. Companies must balance the push for innovative, sustainable products with the need to manage rising input costs and navigate complex compliance landscapes. The ban on certain composite materials in key regions necessitates a re-evaluation of product lines, while tariffs on metals require supply chain resilience and potential localization strategies. The expansion of capacity by major players like Rockwool underscores the importance of securing reliable supply channels, while product launches focused on non-combustibility and eco-friendliness highlight the shifting priorities of architects and developers.
This report serves as an essential tool for organizations aiming to thrive in this evolving environment. By leveraging the data-driven insights and strategic analysis provided, stakeholders can identify high-value segments, anticipate regulatory shifts, and align their portfolios with market demands. Whether you are a manufacturer seeking to expand your footprint, a distributor looking to optimize your inventory, or an investor evaluating market potential, this research delivers the depth and precision required to navigate the future of rainscreen cladding with confidence. The detailed forecasts, competitor benchmarks, and dynamic analysis contained within are designed to transform uncertainty into actionable strategy.
For a complete understanding of the global rainscreen cladding market, including detailed regional breakdowns, application-specific growth rates, and financial modeling, we invite you to access the full report. The data presented here offers a strategic overview, but the full intelligence package provides the granular detail necessary to execute with precision. Explore the findings in depth to secure your competitive advantage in a market poised for significant transformation.
For detailed analysis of this topic, please visit the official page: Rainscreen Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


