



PW Consulting: Luxury Sunglasses Market Hits $14.45B in 2025, Set for 4.59% CAGR Through 2032

The Strategic Imperative: Navigating the Luxury Sunglasses Market in 2026
The global accessory landscape is undergoing a subtle but profound transformation. Within this shift, the Luxury Sunglasses Market stands out as a beacon of resilience and sustained growth. For brand leaders, investors, and supply chain strategists, understanding the nuance of this sector is no longer optional; it is a critical component of long-term portfolio management. As we move through 2026, the intersection of timeless design, technological integration, and complex regulatory environments defines the operational terrain.
PW Consulting's latest comprehensive market research offers a detailed map of this terrain. This report is not merely a collection of statistics; it is a strategic toolkit designed to inform decision-making across product development, regional expansion, and competitive positioning. By analyzing historical trajectories and forecasting future trends, we provide the intelligence necessary to capitalize on emerging opportunities while mitigating the risks inherent in a fragmented market.
The following insights outline the current state of the industry and demonstrate why access to granular data is the ultimate competitive advantage in the coming fiscal years.
Macro Growth Trajectory and Market Valuation
The financial architecture of the luxury eyewear sector reveals a steady upward trend. Our analysis covers historical performance from 2020 through the base year of 2025, extending with precision into the forecast period of 2026 to 2032. This longitudinal view allows stakeholders to contextualize recent volatility against long-term growth patterns.
In 2025, the global market reached a valuation of approximately 14.45 billion USD. Looking ahead, the market is projected to expand to 14.95 billion USD in 2026, continuing its climb toward nearly 19.78 billion USD by 2032. This expansion reflects a Compound Annual Growth Rate (CAGR) of 4.59 percent over the forecast period. While these headline figures indicate healthy momentum, the drivers behind this growth are multifaceted, influenced by consumer behavior shifts, economic conditions, and product innovation.
For executives, the implication is clear: the market is large enough to support diverse strategies but competitive enough to demand precise execution. The steady CAGR suggests that organic growth is achievable, but capturing market share requires more than passive participation. It requires an understanding of where value is being created and how supply chain constraints might alter profitability margins.
The Competitive Landscape: Consolidation and Innovation
The luxury sunglasses sector is characterized by a moderate to high level of concentration. Our research indicates that the top three players hold a significant portion of the market revenue, while the top five firms command an even larger share. This concentration highlights the dominance of major conglomerates that manage multiple licensed and owned brands, though niche players continue to carve out premium positions through craftsmanship and brand heritage.
Several key companies define the current competitive hierarchy:
- EssilorLuxottica (Paris, France): As a market leader, this entity controls a vast portfolio including Ray-Ban, Oakley, and licensed luxury brands such as Tom Ford, Oliver Peoples, and Dolce & Gabbana. Their strategy blends mass appeal with high-end licensing.
- Marcolin Group (Italy): A crucial player in the production and distribution of designer luxury sunglasses, notably holding strong associations with Tom Ford eyewear.
- De Rigo Rem (Italy): Specializes in manufacturing and licensing luxury eyewear, with notable presence in brands like Police and Lozza.
- Safilo Group (Italy): Known for producing licensed luxury sunglasses for prestigious houses such as Gucci, maintaining strong ties to fashion heritage.
- Garrett Leight (United States): Represents the artisanal end of the market, designing and selling handcrafted luxury sunglasses with a focus on premium materials.
- Oliver Peoples (United States): Under EssilorLuxottica ownership, this brand continues to offer premium luxury sunglasses, leveraging its independent heritage within a larger corporate structure.
Strategic activity among these players is intensifying. For example, in March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana, securing development, production, and worldwide distribution rights for prescription frames and sunglasses. Simultaneously, they unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses handmade in Japan. These moves signal a dual strategy: consolidating established luxury licenses while pushing the boundaries of material and fashion collaborations. Furthermore, the expansion of AI glasses portfolios, such as new Ray-Ban Meta optical styles for prescription wearers, indicates a convergence of wearable technology and traditional luxury aesthetics.
Market Dynamics and Regulatory Headwinds
No strategic plan is complete without accounting for external forces. The operational environment in 2026 is shaped by significant regulatory developments, particularly regarding trade policy. Recent updates from The Vision Council highlight substantial shifts in duty rates affecting the optical industry.
Imports of optical products from China have faced updated duty rates, with sunglasses encountering combined rates reaching 154.5 percent. This figure includes base duties, Section 301 tariffs, and reciprocal tariffs enacted in 2025. Such levels drastically impact landed costs and require immediate adjustments in pricing strategies and sourcing logic. In response to these pressures, major industry participants like EssilorLuxottica have implemented price increases in the US market to offset tariff impacts on imports from China and Thailand.
However, the regulatory landscape remains fluid. A 90-day pause on newly implemented country-specific reciprocal tariff increases was announced by the US Administration for countries that have not retaliated, effective April 2025. While this pause offers temporary relief, the underlying trade tensions suggest that supply chain diversification is no longer just a best practice but a necessity for risk mitigation. Companies relying heavily on single-source manufacturing hubs face elevated exposure, making the case for nearshoring or multi-regional production capabilities more compelling than ever.
Segmentation Insights: Where Value Resides
Understanding the composition of the market is vital for targeted investment. Our report dissects the market across three primary dimensions: Region, Type, and Application. While the aggregate numbers tell a story of growth, the segmentation data reveals where the profitability engines are located.
The market is distributed across major geographic zones, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct consumer behaviors. For instance, mature markets in Europe and North America continue to drive volume through established luxury channels, while Asia Pacific represents a dynamic zone of growing affluence and brand consciousness. Navigating these regional differences requires more than a one-size-fits-all approach; it demands localized marketing strategies and distribution partnerships that resonate with specific cultural nuances.
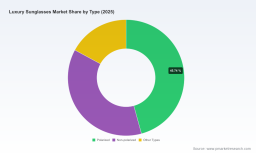
Product type segmentation further illustrates the evolution of consumer preference. The market is divided between Polarized, Non-polarized, and Other Types. The performance of polarized lenses reflects a growing demand for functional luxury, where eye protection and visual clarity are prioritized alongside style. Meanwhile, the non-polarized segment maintains a stronghold in fashion-forward contexts where aesthetics take precedence.
Application-based segmentation highlights the dual identity of luxury sunglasses. The Fashion application dominates the landscape, underscoring the role of eyewear as a critical accessory in personal style and identity. Sports and Other applications, while smaller in relative value, represent high-growth niches where performance materials and specialized designs command premium pricing. Recognizing the balance between these applications allows brands to allocate R&D resources effectively, ensuring they meet the demands of both the runway and the racecourse.
Luxury Sunglasses Market
The Strategic Value of Granular Intelligence
Headline figures and company profiles provide the context, but the true power of this research lies in the details that are not immediately visible. Strategic decisions regarding pricing elasticity, channel mix, and inventory management require access to specific volume data, share percentages, and trend velocity metrics.
For example, knowing the exact revenue split between regions helps determine where to prioritize expansion capital. Understanding the precise share of polarized versus non-polarized types informs product roadmap prioritization. Identifying the specific growth rate of the fashion application segment versus sports allows for nuanced marketing budget allocation. This report provides those specific data points, enabling clients to move beyond general assumptions to evidence-based planning.
Furthermore, the interplay between tariff structures and segmentation is critical. A tariff impact might affect one region or product type more severely than another. Only with detailed data can a company model these scenarios accurately and prepare contingency plans. The inclusion of recent developments, such as specific partnership extensions and product launches, also provides a benchmark for evaluating competitor aggression and innovation cycles.
The market concentration data served as a warning and an opportunity. For new entrants or smaller brands, the high concentration among the top players suggests high barriers to entry in mainstream luxury. However, the persistence of niche brands like Garrett Leight shows that differentiation through material quality and brand storytelling remains a viable path. The research helps identify the white spaces where concentration is lower and potential for disruption exists.
Looking Ahead: Actionable Intelligence for 2026 and Beyond
As we progress through 2026, the Luxury Sunglasses Market will continue to be shaped by the tension between heritage and innovation. Brands must honor the craftsmanship that defines luxury while integrating new technologies and adapting to regulatory shifts. The forecast period extending to 2032 offers a long-term view, allowing companies to plan beyond quarters and focus on sustainable growth.
Sunglasses Market
The data indicates that the market will continue to expand, reaching nearly 20 billion USD by the early 2030s. However, capturing this value requires agility. Supply chain resilience, pricing strategy adjustments, and brand differentiation are the pillars of success in this environment. Companies that rely on outdated assumptions about trade flows or consumer preferences risk margin erosion and loss of relevance.
PW Consulting's Luxury Sunglasses Market Research is designed to equip stakeholders with the clarity needed to navigate these complexities. By providing a comprehensive view of market size, segmentation, competitive dynamics, and regulatory impacts, we enable leadership teams to make informed choices. The insights contained within this report are not just observations; they are the foundation for strategy.
To fully leverage this intelligence, stakeholders must access the complete dataset. The intersection of macro trends and micro-segmentation data reveals the specific pathways to growth that headline numbers cannot show. We invite decision-makers to explore the full report to unlock the detailed analytics required to outmaneuver competitors and secure a dominant position in the evolving luxury eyewear landscape.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


