



PW Consulting: Concrete Expansion Joint Market Hits $596.4M in 2025, On Track for $880.73M by 2032

Navigating the Next Horizon: Strategic Intelligence for the Concrete Expansion Joint Market (2026-2032)
The global construction landscape is undergoing a structural recalibration. As infrastructure ages, urbanization accelerates, and climate resilience becomes a non-negotiable engineering standard, the systems that accommodate movement, stress, and thermal expansion in concrete structures are moving from the background to the center of strategic procurement discussions. The concrete expansion joint market, long viewed as a commodity-adjacent segment, is now a critical nexus where materials science, regulatory compliance, and lifecycle asset management intersect. For executives navigating procurement, engineering, or market entry decisions in 2026 and beyond, generic industry narratives no longer suffice. Precision, traceability, and forward-looking scenario modeling have become table stakes.
This report has been engineered to serve as a decision-grade intelligence framework. Rather than offering retrospective summaries, it maps the operational, financial, and competitive contours that will define market behavior across the forecast horizon. What follows is a structural preview of the analytical architecture, the macro trajectory, and the competitive undercurrents that procurement leaders, product strategists, and infrastructure investors will need to internalize before committing capital or renegotiating supply contracts.
Worldwide Railway Expansion Joints Market
The Macroarc: Growth, Momentum, and the 2032 Trajectory
Understanding where the market is headed requires first grounding the conversation in a verified historical baseline. Drawing on an eight-year observational window from 2020 through 2025, the market has demonstrated consistent expansion, evolving from a 478.4 million USD revenue base in 2020 to 596.4 million USD by 2025. That progression reflects more than incremental volume growth; it signals a maturation in specification practices, a broadening of application mandates, and a gradual shift from reactive repair cycles toward proactive joint system integration during initial construction phases.
Projecting this momentum forward, the trajectory through 2032 maps a disciplined but robust expansion curve. Starting from an estimated 623.0 million USD in 2026, the market is positioned to reach approximately 880.73 million USD by the close of the forecast period. This pathway is underpinned by a compound annual growth rate of 5.8 percent, a figure that encapsulates the compounding effect of infrastructure renewal programs, material upgrades, and sustained demand across multiple end-use environments. For decision-makers, this growth rate is not merely a headline statistic; it is a planning parameter that informs capacity allocation, supplier diversification, and long-term contract structuring. The forward curve suggests a market that is expanding without overheating, creating room for differentiated value plays while maintaining enough competitive intensity to reward operational efficiency and technical differentiation.
The critical takeaway for 2026 strategy teams is that the next seven years will not be defined by sudden volatility, but by the compounding impact of specification trends, regional project pipelines, and material cost pass-through dynamics. Organizations that anchor their planning to this sustained growth trajectory, rather than to short-term contractual fluctuations, will be better positioned to navigate procurement cycles with strategic foresight.
What the Report Delivers: From Framework to Actionable Intelligence
A market research document only earns its place on a strategy desk when it translates into actionable levers. This study has been structured to bridge that gap. Rather than stopping at top-line sizing, the analysis dives into the operational layers that determine how growth is distributed, captured, and defended. The report is organized to serve multiple internal stakeholders simultaneously, from procurement and supply chain leads to product development, regional business development, and competitive intelligence teams.
Concrete Expansion Joint Market
Scope and Analytical Architecture
The research framework is built around three interlocking lenses that together provide a complete view of market mechanics. Each lens is designed to answer a distinct set of strategic questions while remaining fully integrated with the broader market narrative.
- Regional Market Architecture. The analysis maps how demand, project pipelines, and procurement preferences distribute across major geographic zones. Rather than treating regions as uniform blocks, the report examines the underlying drivers shaping consumption patterns, including infrastructure renewal velocity, specification standards, and local material availability. This geographic lens is essential for organizations evaluating market entry, export expansion, or regional supplier rationalization.
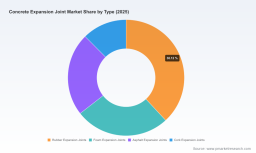
- Product-Type Competitive Positioning. Expansion joint solutions are not interchangeable. The report dissects the market by type, analyzing how engineered rubber and elastomeric systems, foam-based solutions, asphalt configurations, and cork alternatives compete across performance requirements, installation contexts, and lifecycle cost profiles. This segmentation is particularly actionable for manufacturers refining product portfolios, sales teams tailoring value propositions, and procurement groups evaluating total cost of ownership rather than unit price alone.
- Application-End-Use Mapping. Demand does not emerge uniformly across use cases. The study tracks how expansion joint requirements flow from buildings, roads, bridges, and ancillary applications, revealing where specification intensity is highest, where tolerance thresholds drive material selection, and where maintenance cycles reshape replacement demand. This application lens helps stakeholders align product roadmaps, service offerings, and regional targeting with the most responsive demand pools.
Beyond segmentation, the report integrates competitive benchmarking, supply chain exposure, and procurement behavior analysis. It traces how concentration patterns shape pricing power, how specification influence is distributed among key players, and how end-users are recalibrating their evaluation criteria in response to performance reliability and compliance requirements. The intent is to provide a reference architecture that can be directly overlaid onto internal planning models.
Competitive Landscape: Positioning, Differentiation, and Market Concentration
No market strategy is complete without a clear view of the players shaping supply, specification, and customer expectations. The concrete expansion joint segment exhibits a moderately fragmented competitive structure, with market concentration metrics indicating that the top three firms account for approximately 18.5 percent of aggregate revenue, while the top five extend to roughly 22.3 percent. This concentration profile suggests a landscape where scale confers advantages in specification access and supply chain leverage, but where differentiated engineering, regional presence, and application specialization still create meaningful pockets of competitive insulation.
Two organizations exemplify the strategic poles that define current competition. D.S. Brown Company, headquartered in North Baltimore, Ohio, has built its positioning around engineered rubber and elastomeric expansion joint systems tailored for bridges and pavements. Its product philosophy emphasizes movement accommodation, durability, and engineered performance under structural stress. In May 2025, the company reinforced this positioning through updated technical communications highlighting strip seals as a long-lasting sealed expansion joint system capable of handling movement exceeding four inches. This kind of specification-level communication demonstrates how leading participants are competing not merely on product availability, but on performance narratives that align with engineering priorities and lifecycle expectations.
Sika Emseal, operating from the United States, represents a complementary but distinct competitive profile. Its focus spans elastomeric concrete expansion joint systems, covers, and sealants designed for buildings and broader infrastructure applications. The emphasis here extends beyond movement accommodation to integrated sealing performance, coverage systems, and compatibility with building and civil specifications. Together, these participants illustrate how the market is being shaped by firms that translate materials capability into specification relevance, whether through structural joint engineering or integrated sealing and coverage solutions.
For strategists, the competitive takeaway is straightforward: growth in this market will not be captured by undifferentiated capacity alone. It will be earned by organizations that can align product architecture with application-specific performance demands, articulate reliable lifecycle value, and navigate the specification pathways that govern procurement decisions. The report dissects these dynamics in greater detail, mapping how competitive positioning interacts with regional demand, application mix, and pricing behavior.
Market Dynamics and Operating Conditions: What Is Shaping Margins and Execution
Growth trajectories do not unfold in a vacuum. The profitability, execution risk, and supply planning assumptions that underpin 2026 decision-making are being reshaped by a set of operating conditions that demand active management rather than passive monitoring. Raw material exposure, regulatory formulation constraints, and price transmission dynamics are now central variables in joint system procurement and production planning.
Raw Material Exposure and Formulation Complexity
The economics of expansion joint and sealant production are tightly coupled to feedstock markets. Polyurethane sealant formulation, for example, depends on isocyanate and polyol inputs, with pricing closely linked to toluene di-isocyanate and MDI production economics as well as petroleum-derived raw material costs. This linkage means that margin structures are increasingly sensitive to petrochemical price movements, not as an occasional shock, but as a continuous planning variable.
The pressure intensified in early 2026. In the first quarter, prices for Dimethyldichlorosilane rose by 28 percent year-on-year, driven by operational outages at Chinese chlor-alkali units and higher tariffs on silicon metal. Simultaneously, Wacker announced a mid-single-digit price increase in April 2026 in response to supply disruptions in the Middle East and elevated energy tariffs in Europe. These movements are not isolated events; they signal a broader environment in which input cost volatility is becoming a recurring feature of the supply landscape, especially for performance sealants and engineered elastomeric systems.
Regulatory Pressure and Compliance-Driven Cost Dynamics
Beyond raw materials, regulatory frameworks are reshaping formulation strategies and production economics. Stringent VOC emission limits imposed by regulatory bodies have increased formulation complexity and elevated production costs for construction sealants, including those used in concrete joint systems. For suppliers, this means that compliance is no longer a checkbox exercise; it is a product architecture consideration that affects raw material selection, processing requirements, and ultimately cost structures. For buyers, it introduces a new dimension to specification evaluation, where emissions performance, regulatory conformity, and long-term durability must be weighed alongside upfront pricing.
These dynamics create a dual effect on the market. On one side, cost pressure is real and increasingly visible in supplier pricing behavior and contract negotiations. On the other, regulatory and performance expectations are raising the barrier to entry for undifferentiated products, reinforcing the value of engineered solutions that can meet both compliance thresholds and structural performance requirements. Organizations that treat these forces as separate issues, rather than as interconnected drivers of specification and cost, risk misjudging both margin exposure and competitive positioning.
Why This Report Matters for 2026 Decision-Making
The concrete expansion joint market is entering a phase where strategic clarity outperforms tactical reactivity. Growth is steady, competition is intensifying in specific application and product niches, and the cost and compliance environment is demanding more sophisticated procurement and product planning than in prior cycles. For executives, the central challenge is no longer whether the market is expanding, but how to allocate resources, structure supplier relationships, and align product or service strategies with the segments and regions where value is being created most reliably.
This research is designed to address that challenge directly. It provides the structural context needed to evaluate where demand is concentrated, how competitive advantage is being built, and which operating conditions will most affect margins and execution over the forecast period. It is intended for teams that need to move beyond aggregate market narratives and into the segmentation logic, competitive behavior patterns, and supply-side dynamics that actually shape procurement and investment outcomes.
The full study contains the detailed segmentation breakdowns, competitive profiles, regional demand architecture, and forward scenario analysis required to translate this landscape into concrete planning assumptions. The complete intelligence framework, including product-type splits, application-end-use distribution, regional demand architecture, and extended competitive profiling, is available through the full report. For strategy, procurement, and business development teams preparing for 2026 and the years that follow, the depth of that analysis is where directional insight becomes executable strategy.
For detailed analysis of this topic, please visit the official page: Concrete Expansion Joint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


