



PW Consulting Forecasts Dental Intraoral X-ray Sensor Market to Grow at 8.59% CAGR Reaching $473M by 2032

Strategic Horizons: Navigating the Dental Intraoral X-ray Sensors Market in 2026 and Beyond
The global dental imaging landscape is undergoing a profound transformation, driven by the accelerating adoption of digital diagnostics and the relentless pursuit of clinical precision. As stakeholders prepare for the strategic initiatives of 2026, understanding the trajectory of the Dental Intraoral X-ray Sensors Market becomes not just an option but a necessity for informed decision-making. Our latest comprehensive research study offers a definitive guide through this evolving ecosystem, providing the granular intelligence required to position organizations at the forefront of innovation and growth.
The market has demonstrated robust momentum over the past half-decade, establishing a strong foundation for sustained expansion. Historical analysis from 2020 through 2025 reveals a consistent upward trajectory, with the global valuation climbing from 142.0 million USD to a substantial 265.0 million USD in 2025. This progression underscores the industry's resilience and the growing integration of digital sensors into standard dental practices. Looking ahead, the forecast period spanning 2026 to 2032 projects a compelling compound annual growth rate of 8.59 percent. By 2032, the market is anticipated to reach 473.0 million USD, signaling a future where digital imaging becomes ubiquitous across diverse clinical settings. This macroeconomic outlook forms the backbone of our analysis, offering a reliable framework for long-term capacity planning and investment strategies.
Such growth is not merely a function of volume but is deeply rooted in technological evolution and shifting clinical priorities. The transition from traditional film-based methods to digital intraoral sensors represents a paradigm shift in diagnostic efficiency and patient safety. Evidence suggests that optimized digital environments can reduce average X-ray exposure significantly compared to legacy methods, aligning with broader healthcare trends toward minimizing radiation doses while enhancing image fidelity. This technological advantage, coupled with favorable reimbursement structures under codes such as CPT 70350 for radiographic services, creates a supportive economic environment for adoption. However, navigating this landscape requires more than a high-level view; it demands a nuanced understanding of the specific drivers, restraints, and opportunities that define each segment of the value chain.
Unpacking the Competitive Arena
The competitive dynamics within the dental intraoral sensor sector are characterized by a mix of established giants and innovative challengers, each vying for differentiation through product performance and ecosystem integration. Market concentration analysis indicates that the top three players hold a combined share of approximately 40.0 percent, while the top five account for 55.0 percent. This structure suggests a market where scale and brand recognition matter, yet ample room remains for specialized players to capture value through technological distinctions or regional expertise.
Leading the charge is Dentsply Sirona, headquartered in Charlotte, North Carolina. As a manufacturer of Schick intraoral sensors, including the Schick 33 with 33 lp/mm resolution and the AE series, the company continues to set benchmarks for high-quality digital X-ray imaging in dental practices. Their portfolio reflects a deep commitment to reliability and image clarity, crucial factors for practitioners seeking consistent diagnostic outcomes. Similarly, DEXIS, based in Quakertown, Pennsylvania, has carved a significant niche with its DEXIS Ti2 and IXS intraoral sensors, known for high-clarity images and durable hardware. Beyond hardware, DEXIS emphasizes integrated workflows through its DTX Studio software, a strategy that was reinforced by a significant product launch in February 2026. This update introduced expanded AI capabilities for pathological findings on 2D intraoral X-ray images, marking a pivotal step in bridging hardware performance with intelligent diagnostic support. Furthermore, in September 2025, DEXIS released the Imprevo intraoral scanner powered by IS ScanFlow 2.0 innovation, enhancing wireless freedom and precision for digital dentistry workflows, thereby broadening their appeal to practices seeking comprehensive digital solutions.
Planmeca Oy, originating from Helsinki, Finland, brings a distinct focus on user experience and patient-centered design with its Prosensor HD intraoral sensors. The emphasis on exceptional image quality and usability resonates with clinicians prioritizing ergonomics and workflow efficiency. In the Asia Pacific region, Vatech, based in Hwaseong, South Korea, continues to expand its footprint with EzSensor HD and EzSensor UHD intraoral sensors, supporting high-resolution digital X-ray applications. Their growth trajectory reflects the broader dynamism of the Asian market, where digital adoption rates are rising rapidly. Carestream Dental LLC, located in Atlanta, Georgia, maintains a strong presence through its RVG 5200 and other RVG intraoral sensors, integrated within broader digital imaging solutions that leverage the company's extensive distribution network.
The competitive field also includes specialized innovators and emerging players. Owandy Radiology, from Croissy-Beaubourg, France, recently marked a milestone with the launch of its third-generation Opteo intraoral sensor in May 2025. This product is designed for enhanced image clarity, speed, and reliability, showcasing the continuous iteration of sensor technology to meet clinical demands. Freedom Technologies Group, LLC, based in Carmel, Indiana, differentiates itself as a distributor and provider of DC-Air wireless direct-conversion intraoral X-ray sensors. Their offering features Bluetooth connectivity and a zero-profile design, addressing the growing demand for wireless convenience and reduced patient discomfort. Acteon Group, headquartered in Mérignac, France, supplies SOPIX and SOPIX 2 digital X-ray sensors, emphasizing reliable clinical diagnosis and precise tissue differentiation, which are critical for complex restorative and endodontic procedures.
Regulatory milestones and emerging market entrants further shape the landscape. Qpix Solutions Inc, based in Morrisville, North Carolina, achieved a significant regulatory feat in November 2025 by receiving FDA 510(k) clearance for its EzSensor HD and EzSensor UHD digital intraoral sensors. This clearance validates the device's safety and efficacy, opening doors for broader commercial deployment in the United States. Meanwhile, XpectVision Technology Co., Ltd, from China, continues to produce the ZXSZ series intraoral X-ray sensors, focusing on global distribution and technology integration. These developments highlight the global nature of innovation and the increasing importance of regulatory compliance in accessing key markets.
Regulatory Imperatives and Technological Standards
Strategic planning in this sector must account for a rigorous regulatory environment. All dental intraoral X-ray sensors must comply with FDA 510(k) clearance requirements as Class II medical devices under 21 CFR 872.1800. This regulatory framework ensures that devices meet essential performance and safety standards before reaching the market, influencing product development timelines and market entry strategies. Additionally, ISO 10993-1 biocompatibility standards apply to sensor housings and cables for medical-grade materials in direct oral contact. Compliance with these standards is non-negotiable for manufacturers aiming to assure clinicians and patients of the safety and quality of their products. These regulatory layers add complexity but also serve as barriers to entry that can protect established players with robust quality management systems.
Segmentation Dynamics and Market Drivers
The market's growth is fueled by distinct segmentation drivers that our report analyzes in depth. The type segment reveals a prevailing preference for wired sensors, which continue to dominate in terms of revenue contribution, reflecting their established reliability and cost-effectiveness in many practices. However, the wireless segment is gaining traction, driven by the demand for improved ergonomics and flexibility in clinical workflows. This shift is exemplified by products like the DC-Air wireless sensors and the integration of wireless capabilities in broader imaging ecosystems. The balance between wired and wireless adoption varies by region and practice type, and understanding these nuances is critical for product positioning and marketing strategies.
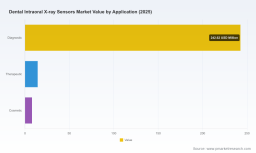
In terms of application, diagnostic use cases account for the lion's share of market activity. Clinicians rely on intraoral sensors for precise caries detection, periodontal assessment, and endodontic diagnosis, making diagnostic functionality the primary value proposition. Therapeutic and cosmetic applications, while smaller in volume, represent specialized niches where imaging supports treatment planning and aesthetic outcomes. The end-user landscape is similarly stratified, with dental clinics representing the largest segment due to their sheer number and high frequency of imaging procedures. Dental hospitals, while fewer in count, contribute significantly through higher-volume usage and the complexity of cases handled. These structural insights inform channel strategies, pricing models, and service support requirements tailored to each customer type.
Regional Perspectives and Global Opportunities
Geographically, the market exhibits diverse growth patterns shaped by healthcare infrastructure, economic development, and regulatory environments. North America remains a dominant force, supported by advanced dental infrastructure and high adoption rates of digital technologies. Europe follows as a significant market, characterized by strong regulatory standards and a mature dental sector. The Asia Pacific region, while currently smaller in absolute terms compared to North America and Europe, is poised for rapid expansion driven by increasing healthcare expenditure, growing awareness of oral health, and the expanding presence of key manufacturers. Latin America and the Mideast and Africa present emerging opportunities, where infrastructure development and trade dynamics influence market penetration. Our analysis avoids simplistic generalizations, instead providing context-aware insights that help stakeholders identify the most promising corridors for expansion or partnership.
What This Research Delivers
This market research report is designed as a strategic tool for executives, product managers, investors, and policymakers. It moves beyond aggregate numbers to provide actionable intelligence across multiple dimensions. Readers will find a detailed examination of market size and forecasts, contextualized within historical trends and future projections. The report dissects the competitive landscape, offering profiles of key companies, their product portfolios, and recent strategic moves such as product launches and regulatory clearances. This competitive intelligence enables benchmarking and helps identify gaps in the market that may represent opportunities for innovation or acquisition.
Furthermore, the study explores market dynamics comprehensively, analyzing drivers, restraints, opportunities, and challenges. It delves into the impact of reimbursement policies, regulatory requirements, and technological advancements on market growth. The segmentation analysis provides a granular view of how different product types, applications, and end-users contribute to the overall market, allowing for targeted strategy development. The regional analysis offers a nuanced understanding of geographic variations, supporting decisions related to market entry, localization, and resource allocation. Additionally, the report includes a value chain analysis, examining the roles of raw material suppliers, manufacturers, distributors, and end-users, which is essential for optimizing supply chain efficiency and identifying leverage points.
Strategic Outlook for 2026
As organizations formulate their strategies for 2026, the dental intraoral X-ray sensors market presents a landscape rich with potential but also complex with challenges. The integration of AI capabilities, as demonstrated by recent updates to imaging platforms, points toward a future where diagnostic support becomes more intelligent and integrated. Wireless technology continues to evolve, addressing usability concerns and expanding the flexibility of clinical setups. Regulatory compliance remains a critical success factor, with firms needing to stay abreast of evolving standards and clearance processes. Reimbursement landscapes and healthcare policies will continue to influence adoption rates, requiring stakeholders to monitor policy developments closely.
Dental Intraoral X-ray Sensors Market
Success in this environment depends on the ability to synthesize market data with strategic foresight. Companies must balance the pursuit of technological leadership with the pragmatic needs of their customers, whether they are individual clinics seeking reliable, cost-effective tools or large hospital networks demanding seamless integration and high throughput. Understanding the competitive positioning of peers, the nuances of regional markets, and the specific requirements of different application segments is paramount. This report serves as a compass in that endeavor, providing the depth and breadth of analysis necessary to navigate the market with confidence. The insights contained within are structured to support a wide range of strategic decisions, from product development and portfolio optimization to market expansion and partnership formation.
For those seeking to capitalize on the growth trajectory of this sector, the time to act is now. The convergence of favorable market fundamentals, technological innovation, and evolving clinical needs creates a window of opportunity for organizations ready to invest in a deeper understanding of the landscape. We invite stakeholders to access the full scope of our research to unlock the detailed data, forecasts, and strategic recommendations that will empower their decision-making in 2026 and beyond. The complete analysis offers the granularity required to turn market intelligence into competitive advantage, ensuring that your organization is well-positioned to thrive in the evolving world of dental digital imaging.
Intraoral Optical Scanner Market
For detailed analysis of this topic, please visit the official page: Dental Intraoral X-ray Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


