



PW Consulting: School Furniture Market Hits $4.8B in 2025, Projects 7.2% CAGR to 2032

Strategic Horizons: Navigating the Global School Furniture Market Through 2032
Introduction to the 2026 Market Intelligence Brief
As educational paradigms shift rapidly toward flexible learning environments and increasing emphasis on health-centric infrastructure, the global school furniture market stands at a pivotal juncture. Our latest market research delves into the complex interplay of demand drivers, regulatory shifts, and competitive positioning that will define the industry over the next decade. This article serves as a strategic preview of the full study, highlighting the macroeconomic trajectories and structural dynamics that corporate leaders must parse to secure growth in 2026 and beyond.
Trajectory and Scale: A Decade of Sustained Expansion
The market has demonstrated remarkable resilience and consistent expansion over the past half-decade. Historical data from 2020 through 2025 reveals a clear upward trajectory, with total industry revenue climbing from a baseline of USD 3,300 million to an estimated USD 4,800 million in 2025. This growth reflects sustained capital allocation toward educational infrastructure and a structural pivot toward higher-quality, ergonomically optimized classroom equipment.
Looking forward, the revenue forecast extends through 2032, projecting a compound annual growth rate of 7.2 percent. By the close of the forecast horizon, total market revenue is anticipated to reach approximately USD 7,780 million. Such figures underscore a sector that is not merely expanding in nominal terms but is also maturing in terms of product sophistication and compliance requirements. For corporate planners, these numbers signal sustained demand velocity rather than a transient post-pandemic rebound, making long-term capacity planning and portfolio optimization imperative.
Core Drivers: Policy, Pedagogy, and Compliance Standards
Several converging forces are propelling this expansion. First, global education spending remains a strategic priority for governments and private institutions alike. Upgrades to aging classroom infrastructure, combined with the integration of modern pedagogical approaches, are accelerating replacement cycles and driving demand for furniture that supports collaborative, movable, and technology-integrated learning setups.
Second, regulatory and standards-based compliance has become a defining feature of procurement decision-making. The industry is witnessing heightened attention to durability, safety, and environmental accountability. The widely referenced BIFMA X6.1 standard for educational seating continues to shape product specifications across pre-school through adult education environments, ensuring that seating solutions meet rigorous performance criteria. Concurrently, the updated BIFMA Furniture Surfaces Guideline (BIFMA G8.1-2026) provides detailed protocols for surface performance against cleaning, sanitizing, and disinfecting products. These guidelines directly influence material selection, coating technologies, and lifecycle durability, especially in high-traffic institutional settings.
Additionally, the BIFMA LEVEL certification program has gained traction among institutions seeking to align purchasing decisions with environmentally and socially responsible criteria. Together with the general-purpose and educational seating standards codified in ANSI/BIFMA X5.1 and X6.1, these frameworks create a compliance layer that rewards manufacturers and suppliers who invest early in certified, specification-ready product lines.
Educational Furniture Market
A recent industry development highlights the active role of standards bodies in this ecosystem. In February 2026, BIFMA published the updated Furniture Surfaces Guideline, hosted sessions on industry leadership and standards development during its 360 Conference, and released the Outdoor Furniture Whitepaper covering performance and sustainability criteria relevant to educational outdoor spaces. These deliverables reflect a broader push toward holistic environmental and hygiene considerations that extend beyond the traditional indoor classroom.
Product Archetypes: Seating, Storage, and Specialized Lab Solutions
The market is structured around distinct product families that serve different functional needs within educational environments. Seating remains the dominant category, reflecting the centrality of ergonomic and durable seating to daily student comfort and institutional compliance. Storage solutions constitute a substantial complementary segment, supporting organizational demands across classrooms, libraries, and administrative areas. Specialized laboratory furniture represents a focused but high-value category, where durability, chemical resistance, and modularity demand differentiated engineering and specification processes.
Beyond product type, application context shapes purchasing behavior. Classroom environments form the core application base, driven by large-volume procurement and frequent replacement schedules. Library and laboratory settings contribute additional demand, often characterized by higher specification thresholds and longer asset lifecycles. A residual application stream encompasses administrative, multipurpose, and specialty environments, ensuring diversified revenue channels across the sector. These structural distinctions matter for market entrants and incumbents alike because they influence SKU complexity, lead times, and the nature of specifier relationships with school districts and institutional buyers.
Competitive Landscape: Incumbency, Specialization, and Geographic Footprints
The competitive arena is characterized by a mix of established regional manufacturers and globally oriented suppliers, with a moderate degree of concentration among leading players. The top three participants collectively account for approximately 52.3 percent of industry revenue, while the top five extend their combined share to roughly 68.4 percent. Such concentration indicates the presence of scaled incumbents with established supply chains, specifier relationships, and compliance portfolios, but it also leaves meaningful space for differentiated players in niche categories, specialized applications, and regional procurement ecosystems.
School Furniture Market
Several companies illustrate the breadth of strategic positioning in the market. Smith System, headquartered in Grand Haven, Michigan, specializes in wholesale ergonomic and flexible school furniture designed for K-12 classrooms, including desks, chairs, and collaborative systems that span elementary through high school levels. Haworth, based in Holland, Michigan, provides institutional and educational furniture solutions encompassing tables, seating, and modular systems tailored to both higher education and K-12 learning environments. VS Furniture, operating from Germany, offers school and office furniture with a strong emphasis on ergonomic systems and modular solutions for education facilities. Krueger International, located in Green Bay, Wisconsin, manufactures institutional furniture including school and educational seating and tables under BIFMA standards, underscoring a compliance-oriented product philosophy.
Virco, based in Placentia, California, focuses on durable school desks, chairs, and modular seating solutions for educational institutions, highlighting an emphasis on longevity and cost-effective lifecycle performance. Insalco provides contract furniture that includes school and library seating and storage systems for educational use, bridging institutional procurement requirements with functional versatility. Robert H. Lord offers school furniture developed under BIFMA X6.1 educational seating standards, reflecting alignment with sector-specific seating criteria. PSI-New England Storage Products supplies storage and seating solutions for school environments as part of institutional furniture contracts, illustrating the role of specialized storage and ancillary seating providers in holistic facility planning.
Strategically, the market rewards firms that can combine compliance readiness, ergonomic credibility, and flexible system design. In practice, winning suppliers often differentiate through durable material platforms, service-oriented specification support, and regionally attuned distribution models that reduce procurement friction for school districts and facility managers.
Strategic Imperatives for 2026 Decision-Makers
Corporate leaders evaluating this market should focus on several actionable priorities. First, compliance integration must move from reactive to proactive. As cleaning, sanitizing, and disinfecting protocols become embedded in procurement specifications, product surfaces, edges, and materials need documented performance evidence. Firms that pre-position their portfolios against evolving surface-performance guidelines and educational seating standards will shorten specification cycles and reduce qualification risk.
Second, portfolio architecture should balance volume stability with premium differentiation. While seating remains the volume backbone of the market, storage and specialized lab furniture offer higher margin potential and longer replacement intervals. Companies that can bridge both mass-market reliability and specification-grade engineering are better positioned to capture institutional budget allocations across multiple procurement categories.
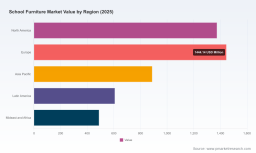
Third, geographic strategy should reflect regional procurement rhythms and funding patterns. Some regions exhibit stronger institutional investment profiles and mature specifier networks, while others present growth headroom tied to infrastructure modernization and expanding enrollment. The distribution of revenue across major regions underscores that a one-size approach is insufficient; instead, localized service coverage, specification support, and compliance documentation are essential to capturing share in each territory.
Fourth, sustainability credentials are transitioning from optional differentiators to procurement expectations. Certification frameworks that evaluate environmental and social responsibility resonate with institutional buyers and can influence vendor shortlists. Manufacturers and suppliers that embed sustainability into material sourcing, production practices, and product end-of-life considerations can strengthen competitive positioning in specification-driven bids.
Fifth, modular and flexible system design should be treated as a strategic asset. As learning spaces adapt to varied pedagogical modes, furniture that supports reconfiguration, durable mobility, and collaborative use cases aligns with buyer demand for multi-functional, future-ready environments. Suppliers capable of offering integrated seating, storage, and collaborative modules can differentiate not just on product but on total-space value.
What the Full Study Delivers: Applied Intelligence for Execution
This market research goes beyond high-level sizing to provide operational granularity that supports planning, forecasting, and competitive benchmarking. The study maps revenue distribution across region, product type, and application, enabling leaders to identify the most attractive sub-segments for investment, capacity allocation, and go-to-market tailoring. It also examines the competitive architecture in greater depth, profiling leading players and their positioning along dimensions such as compliance readiness, product specialization, geographic reach, and service models.
In addition, the report analyzes regulatory and standards developments with an eye toward commercial impact, translating technical guideline updates into implications for material selection, surface engineering, certification strategy, and procurement dialogue. Procurement dynamics, specifier behavior, lead-time expectations, and lifecycle cost considerations are assessed to help firms optimize pricing architecture and channel strategy. The study also incorporates scenario sensitivity around growth pacing, allowing decision-makers to test assumptions against alternative demand paths and adjust portfolio commitments accordingly.
For organizations engaged in manufacturing, distribution, specification, or institutional procurement, the full report provides the structured intelligence needed to prioritize SKUs, allocate sales resources, refine compliance documentation, and time market entry or expansion moves with greater confidence.
Conclusion: Positioning for Informed Growth
The school furniture market is entering a period of steady, standards-shaped expansion. With a projected compound annual growth rate of 7.2 percent and revenue expected to approach USD 7,780 million by 2032, the sector offers durable opportunity for firms that can align product quality, compliance readiness, and regional execution. The convergence of ergonomic expectations, hygiene-conscious surface performance, sustainability certification, and modular flexibility is reshaping what buyers value and how competition unfolds. Leaders who act on these signals now will be better positioned to secure share, reduce specification friction, and build resilient revenue channels across the forecast horizon. This research is designed to convert those signals into actionable strategy, and we invite stakeholders to explore the complete findings for the full intelligence set needed to guide 2026 decisions.
For detailed analysis of this topic, please visit the official page: School Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


