



PW Consulting: Ribbon Fiber Cable Market Hits $2.58B in 2025, Growing at 8.9% CAGR to 2032

Strategic Pulses Beneath the Surface: Why the Ribbon Fiber Optic Cable Market Demands Executive Attention in 2026
Capital allocation in fiber infrastructure has reached a decisive inflection point. For network operators, hyperscale tenants, and optical equipment leaders, the ribbon fiber optic cable category is no longer a niche alternative. It has become a foundational enabler of bandwidth density, deployment speed, and total cost efficiency across everything from fiber-to-the-x builds to intercontinental data center interconnects. Our newly released Ribbon Fiber Optic Cable Market study was designed to transform that strategic reality into a decision-ready intelligence framework. This article previews the analytical architecture of the report, highlights the structural forces reshaping the competitive field, and explains why the full dataset is essential for boards and strategy teams navigating the 2026 to 2032 investment horizon.
The Strategic Imperative of Density, Speed, and Cost Discipline
The ribbon fiber category has earned its place in forward-looking infrastructure roadmaps by solving three persistent bottlenecks simultaneously: duct and rack space constraints, fiber count ceilings, and installation labor intensity. As bandwidth demand compounds across enterprise campuses, wholesale metro networks, and hyperscale campuses, the industry is shifting away from incremental single-fiber scaling toward high-density ribbon architectures that compress physical footprint while accelerating splicing, handling, and deployment timelines. That transition is not cosmetic. It recomputes the economics of civil works, reduces exposure to skilled labor scarcity, and changes the relative attractiveness of different cable formats under constrained right-of-way conditions. The strategic question for 2026 is no longer whether ribbon fiber has a role, but which designs, counts, and supplier ecosystems will outperform under specific deployment conditions, procurement regimes, and margin pressures.
Blueprint of the Market Study: A 2026-Ready Intelligence Architecture
This study is built for operators and investors who need more than a top-line growth estimate. It places the ribbon fiber optic cable market inside a rigorous, forward-looking analytical structure that connects historical performance to the 2026 to 2032 forecast window. The report definition base year is 2025, with historical analysis spanning 2020 through 2025 and a forecast horizon extending to 2032, all valued in USD billions. The study integrates that trajectory with segmentation logic that lets decision-makers evaluate where value is accumulating, which applications are scaling fastest, and how regional deployment cycles influence supplier demand. Rather than presenting the market as a single growth line, the analysis separates type dynamics, application-driven pull, and regional demand patterns so that procurement, capacity planning, and supplier negotiations can be calibrated to actual operating conditions.
Practically, the report is structured to support concrete decisions. It maps the market by cable configuration, application pull, and regional deployment intensity, giving leadership the context needed to prioritize fiber count strategies, hedging approaches, and sourcing footprints. It also evaluates competitive positioning through concentration metrics and company-level profiles, which allows teams to assess market vulnerability, partnership opportunities, and the strategic importance of supplier differentiation beyond fiber count alone. The segmentation architecture is deliberately comprehensive because ribbon fiber economics vary sharply across environments: a hyperscale data center interconnect, a metro duct build, and a rural fiber-to-the-x program face different density requirements, regulatory constraints, and labor profiles. The study treats those differences as decision inputs, not background noise.
Analytical Pillars Built for Execution
- Type evaluation that contrasts multi-mode and single-mode ribbon offerings across fiber count flexibility, density advantages, and deployment suitability
- Application analysis covering fiber-to-the-x, data center interconnects, and other network uses, with attention to how each environment shapes cable specification needs
- Regional demand mapping that reflects where infrastructure investment cycles are concentrated and how procurement environments differ by geography
- Competitive concentration analysis, including CR3 and CR5 readings, to frame supplier power, diversification risk, and negotiation leverage
- Company and product intelligence that compares leading cable and connectivity players on architecture, handling characteristics, density gains, and application fit
- Emerging industry developments such as product compatibility programs and awards that signal architectural validation and cross-vendor integration momentum
Market Trajectory: What the Growth Arc Signals for Strategy Teams
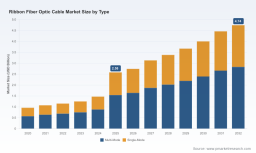
The headline trajectory is powerful, but the real strategic value lies in what that trajectory implies for capacity timing, supplier selection, and deployment sequencing. Over the 2020 to 2025 review period, the market moved from below one billion USD to a materially higher base, and the forecast suggests continued expansion through the end of the decade and into the early 2030s. That sustained upward path reflects more than cyclical demand. It reflects a structural re-rating of fiber density as a first-order requirement in an environment where bandwidth growth, space constraints, and deployment economics are increasingly inseparable. The forecast CAGR of 8.9 percent over the 2026 to 2032 window underscores that this is not a short-lived surge; it is a multi-year shift in how high-capacity optical connectivity is planned, specified, and deployed.
For strategy teams, the implication is that ribbon fiber is becoming a core part of long-cycle infrastructure planning rather than a tactical substitute. That matters because long-cycle planning changes the calculus for supplier relationships, technology roadmaps, and capital exposure. A market expanding on this schedule rewards organizations that can align product specification, installation process, and sourcing strategy with where capacity will be needed, when it will be needed, and under which regulatory and cost conditions. The report provides the structured context to make those choices deliberately rather than reactively.
Growth Pattern and Decision Implications
The overall market size progression used in the study reflects that forward momentum. From 2020 through 2025, the base evolution spans from approximately 0.96 billion USD to 2.58 billion USD, with the forecast band advancing through the forecast window and reaching 4.74 billion USD by 2032. Those figures are presented in the report as part of a broader analytical narrative, not as isolated endpoints, because the real challenge for leadership is to interpret growth in relation to segmentation, concentration, and application-specific pull. The report keeps the emphasis on relative positioning and strategic sequencing so that executives can see how the market is evolving, where the share shifts are likely to concentrate, and which decisions are most sensitive to timing.
Segmentation and Application Signals Without Losing the Strategic Thread
One of the study’s most valuable contributions is its treatment of demand by type and by application, which helps executives understand why different deployments favor different ribbon approaches. The type split in the reporting framework distinguishes multi-mode and single-mode ribbon products, each with different strengths in reach, density, and network architecture fit. The application breakdown makes clear that ribbon fiber is being pulled by a range of use cases, with fiber-to-the-x representing the largest share of application-driven demand, data center interconnects holding a significant and strategically important position, and other applications contributing additional demand layers. That mix matters because application economics differ sharply in terms of fiber handling, splicing complexity, installation environment, and long-term scalability.
Regional context is just as important. The study distributes demand across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, reflecting the geographic unevenness of infrastructure investment, policy support, and deployment velocity. The report avoids flattening those regions into a single narrative, because regional procurement behavior, manufacturing footprints, and fiber deployment cycles directly influence which suppliers win, which specifications scale, and which contracts become strategically critical. By preserving that regional specificity within the analysis, the study gives leaders a more usable view of where demand is forming and how supplier competition is being shaped on the ground.
Competitive Landscape: Concentration, Differentiation, and the New Battleground for Density
The ribbon fiber market is not a commodity game. The study’s competitive concentration metrics show that the top three suppliers account for roughly 30 percent of market share, while the top five collectively command approximately 45 percent. That concentration structure has strategic consequences. It suggests that a meaningful share of scaling demand is being captured by established players with differentiated product architectures, strong manufacturing footprints, and broad application coverage. At the same time, it also indicates room for specialized challengers, regional winners, and cross-ecosystem partnerships to influence customer choice through technical differentiation, installation efficiency, and deployment flexibility.
The competitive profiles compiled in the report demonstrate that differentiation is increasingly being won on more than raw fiber count. The leading companies are shaping buyer preference through cable architectures that reduce physical size, shorten installation time, improve handling, and increase usable density in constrained pathways. For example, the study examines suppliers whose ribbon designs are engineered to compress cable outer diameter, eliminate gel-dependent construction where high-density indoor or outside-plant performance is required, and accelerate deployment in data center and OSP settings. Other profiles focus on intermittently bonded ribbon approaches that make high-density cables easier to handle, fold, or roll, which changes the practical experience of installation teams and can materially affect total deployment time. The report also maps offerings that push fiber counts into the thousands with reduced diameter profiles for underground and high-capacity applications, as well as designs built for hyperscale data centers with non-metallic construction and extremely high fiber counts.
Equally important, the study highlights companies whose ribbon products are being positioned for practical density gains in fiber-to-the-x and enterprise environments, where installation time savings and duct efficiency can change program economics. It also covers players focused on high-density ribbon patch cords and compact cable formats for data-center applications, alongside companies serving enterprise, tactical, and industrial requirements with ribbon configurations designed for durability and handling resilience. The competitive analysis therefore reflects a market in which technical claims must be matched with operational reality: density, bend performance, installability, compatibility with downstream components, and fit with regional procurement expectations.
Strategic Reading of Leading Profiles
The report treats competition as a multi-dimensional problem rather than a simple vendor list. Some suppliers compete on extreme fiber count and compact geometry aimed at hyperscale and high-capacity environments. Others compete through handling innovations that make ribbon easier to deploy in field conditions. Others build strength around application-specific variants for metro, FTTH, and enterprise networks, or around compatibility with domestic procurement mandates and regional supply expectations. The study’s company profiles are structured to help strategy teams compare these positions directly, understand where each supplier creates value, and anticipate where procurement negotiations are likely to center on specifications, lead times, and installation efficiency rather than price alone.
Ribbon Fiber Optic Cable Market
Momentum Points: Compatibility, Recognition, and Supply-Side Pressure
Recent industry developments reinforce the direction of the market and the importance of tracking how ribbon fiber is being validated and adopted in live deployment ecosystems. One notable signal is the product compatibility program pairing drop closures with rollable ribbon fiber optic cable, which showcases how integration between closure hardware and high-density cable design can streamline FTTx network design and deployment. That kind of interoperability focus matters because ribbon adoption does not depend on cable performance alone; it depends on whether the broader outside-plant and termination ecosystem can absorb high-density architectures efficiently. A second signal is the recognition of a 13824-fiber ribbon and wrapping tube cable design with a major product award for hyperscale data center applications, which reflects the industry’s increasing emphasis on extreme-density, non-metallic, high-capacity cable formats for campus-scale data infrastructure.
Just as important, the study incorporates supply-side dynamics that can alter both cost assumptions and sourcing strategies. Input cost pressure is visible in recent pricing trends for bend-insensitive fiber, where per-kilometer costs rose sharply between mid-2025 and early 2026 amid sustained demand and supplier caution about further increases. That kind of movement affects margin planning, product pricing, and the timing of large specification commitments. At the same time, the report addresses how domestic content and procurement policy environments are shaping purchase behavior, with some major providers adjusting assembly and manufacturing footprints to align with local sourcing expectations. Policy support for digital inclusion and data-sovereignty requirements is increasingly converging across regions in ways that favor domestic fiber optic cable production and procurement. These dynamics are not peripheral; they influence where capacity should be sourced, how flexible the supply chain needs to be, and which suppliers can offer adaptable local or compliant manufacturing pathways.
Why the 2026 Decision Window Requires the Full Study
Executives evaluating ribbon fiber strategies in 2026 need more than a directional market narrative. They need to understand which cable types are gaining share in which applications, how regional demand patterns translate into supplier exposure, where competitive concentration is rising, and how cost and policy pressures might reshape total deployment economics. The public-facing growth figures and competitive structure outlined here confirm that ribbon fiber is a strategically significant category with a durable multi-year trajectory. Yet the operational decisions that separate winners from followers depend on the deeper segmentation data, concentration detail, application nuance, and supplier positioning contained in the full report.
The complete study gives strategy teams the ability to connect market size to deployment reality. It helps procurement teams assess supplier risk and negotiation leverage. It helps network planners align ribbon specifications with application requirements and regional conditions. It helps investors and corporate development teams understand where density innovation, compatibility programs, and manufacturing adaptation are creating defensible advantage. Most importantly, it creates a shared analytical frame for decisions that will shape infrastructure economics for the rest of the decade.
Next Steps: Turn Directional Confidence into Decisive Intelligence
This preview is intended to establish the strategic relevance and analytical rigor of the Ribbon Fiber Optic Cable Market study, while preserving the segment-level detail that makes the report a decision tool rather than a summary. The directional growth path, competitive structure, application momentum, and supply-side pressures described here justify immediate strategic attention. The full report is where that attention becomes actionable: it delivers the specific segmentation values, regional demand patterns, supplier comparisons, and deployment context that allow leadership teams to convert market growth into a disciplined 2026 strategy. For organizations planning capacity, negotiating supply, or evaluating where ribbon fiber fits into their infrastructure roadmap, the complete study offers the granularity required to move from informed anticipation to confident execution.
Fiber Optic Cable Assembly Market
For detailed analysis of this topic, please visit the official page: Ribbon Fiber Optic Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


