



PW Consulting Report: Smart Water Meters Market to Hit $16.29M by 2032, Driven by 9.6% CAGR

The Strategic Imperative of Smart Water Infrastructure in 2026 and Beyond
Market Evolution and Growth Trajectory
The global smart water meters market is undergoing a structural transformation, driven by mounting pressure on utilities to improve operational efficiency, reduce non-revenue water, and meet increasingly stringent environmental and regulatory standards. According to our latest market research covering the historical period from 2020 to 2025 and a forward-looking forecast through 2032, the industry has demonstrated a clear upward trajectory. The market reached a valuation of $16.82 billion in 2023 and climbed to $17.78 billion in 2024, reflecting sustained demand for advanced metering infrastructure across municipal and commercial networks. Our forecast model projects the market to expand from $9.59 billion in 2026 to $16.29 billion by 2032, delivering a compound annual growth rate of 9.6 percent. This growth rate is not merely a statistical projection; it is a reflection of systemic shifts in how utilities manage water distribution, how governments prioritize infrastructure resilience, and how technology providers are converging metering hardware with intelligent analytics platforms.
The base year analysis for 2025 establishes a critical inflection point in the market cycle. While macroeconomic fluctuations and supply chain adjustments have introduced short-term variability, the underlying demand drivers remain firmly intact. Governments and water authorities are accelerating capital expenditure toward digital infrastructure, recognizing that legacy metering systems are no longer adequate for managing scarcity, detecting leaks, or engaging end consumers with transparent usage data. For corporate strategists, municipal planners, and technology investors, understanding the magnitude and pace of this transition is essential. Our research is designed to provide that clarity, offering a data-backed framework that separates long-term structural trends from short-term market noise.
Key Market Drivers and Structural Dynamics
Several interconnected forces are propelling the smart water meters market forward, and each carries distinct implications for stakeholder strategy. First, the imperative to reduce non-revenue water continues to dominate utility investment priorities worldwide. Aging distribution networks, undetected leaks, and manual meter-reading limitations have historically resulted in substantial revenue losses. Smart metering technologies address these challenges by enabling continuous, high-frequency consumption monitoring, automated anomaly detection, and rapid response workflows. Utilities that deploy advanced metering infrastructure can identify leaks in near real time, prioritize maintenance efforts, and significantly reduce water loss across their networks.
Second, regulatory frameworks and public funding mechanisms are increasingly aligned with digital water infrastructure. Policy initiatives across multiple regions have reinforced the strategic priority of modernizing utility networks, with funding programs and grants specifically targeting smart meter adoption and advanced metering rollouts. Public-sector projects are leveraging federal and regional support to replace aging meters, upgrade communication networks, and integrate data analytics capabilities. These developments are not isolated events but part of a broader acceleration in infrastructure modernization that favors vendors and partners capable of delivering end-to-end solutions.
Third, operational cost reduction remains a decisive factor. Manual meter reading requires dedicated labor, vehicle fleets, and recurring field expenditures. Smart water meters substantially reduce or eliminate these recurring costs by enabling remote data collection, automated billing cycles, and centralized performance monitoring. Utilities that have completed large-scale meter upgrades have reported measurable reductions in daily truck routes, staff hours, and operational overhead, reinforcing the business case for widespread deployment.
Fourth, consumer engagement and demand-side management are becoming central to utility strategy. Real-time usage portals, leak alerts, and granular consumption insights empower residential and commercial users to adjust behavior, reduce waste, and improve cost predictability. This shift toward transparency is reshaping the relationship between utilities and end users, creating new expectations for service quality and digital interaction.
Smart Water Meters Market
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three players accounting for approximately 28 percent of market revenue and the top five representing around 38 percent. This concentration suggests that while established vendors hold meaningful share, the market still offers substantial room for differentiated positioning, regional expansion, and technology-led disruption. The leading ecosystem spans a diverse set of global and regional players, each pursuing distinct value propositions across hardware, communication protocols, software analytics, and utility integration services.
Several major vendors have built strong positions around advanced metering infrastructure and integrated analytics. Badger Meter continues to emphasize ultrasonic and mechanical meter platforms combined with AMI integration, real-time consumption data, leak detection capabilities, and advanced analytics for utilities. Sensus, operating under Xylem, has focused on AMI-enabled smart water meters that support cellular and wireless networks, alongside data analytics for leak detection and customer-facing portals. Neptune Technology Group has concentrated on ultrasonic and mechanical smart meters paired with AMI systems, remote monitoring, and integration tailored to municipal utilities. Itron has advanced its OpenWay Riva AMI smart water solution, combining advanced metering infrastructure, cellular network support, and utility analytics. These players illustrate a common strategic theme: the value proposition is no longer limited to metering hardware alone but extends to data flow, network reliability, and decision-support tools.
In parallel, a strong cohort of international manufacturers is expanding across specialized communication protocols and regional market requirements. Kamstrup has emphasized ultrasonic and mechanical smart water meters with LoRaWAN and cellular communication, highlighting energy efficiency and real-time usage analysis. Diehl Stiftung & Co. KG has developed the HYDRUS 2.0 ultrasonic smart water meter with LoRaWAN connectivity and remote monitoring capabilities. Landis+Gyr has focused on AMI-enabled smart water meters with integrated software platforms for utilities and demand response. Zenner International GmbH & Co. KG has positioned its ultrasonic and mechanical smart water meters around support for multiple data transmission protocols. Honeywell International Inc. has moved into 5G-enabled smart meters with Verizon connectivity for remote data access and utility monitoring. Aclara Technologies, part of Hubbell, has advanced RF-based AMI smart water meters for advanced metering and leak detection. These examples reflect a broader industry pattern in which communication architecture and interoperability are becoming critical differentiators.
Regional and specialty manufacturers are also shaping competitive dynamics. Wasion Group has targeted international markets with prepaid and remote-reading smart water meters supported by ISO and MID certifications. BMETERS Srl has focused on digital multi-jet and ultrasonic smart water meters with M-Bus and LoRa modules. Collectively, these companies demonstrate that the market is not defined by a single technology standard or business model. Instead, success increasingly depends on aligning hardware performance, communication flexibility, regulatory compliance, and utility integration across diverse operating environments.
Recent corporate and municipal activity reinforces this competitive intensity. Itron released a 2026 report examining how European utilities are using AI and real-time data for leak prevention in digitizing water infrastructure. Such initiatives signal a shift toward intelligence-led operations, where metering data feeds directly into predictive maintenance and demand management workflows. The competitive advantage belongs to organizations that can convert raw metering data into actionable operational insights at scale.
Report Coverage and Decision-Making Utility
Our Smart Water Meters Market research is structured to support concrete strategic decisions rather than abstract market observation. The study provides a comprehensive mapping of market size, growth trajectory, segmentation dynamics, and competitive positioning across the 2026 to 2032 forecast window. It is designed for executives who need to evaluate entry timing, investment prioritization, product roadmap alignment, and regional expansion opportunities with a clear view of where demand is forming and why.
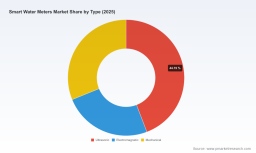
The report analyzes the market across multiple structural dimensions, including technology type, application context, and regional deployment patterns. Rather than treating these categories as static labels, the analysis examines how each segment contributes to overall growth momentum, where adoption curves differ, and which demand drivers are most influential in each context. This segmentation-based perspective enables stakeholders to identify high-conviction opportunities, anticipate displacement risks, and calibrate commercial strategies to the realities of market adoption.
A core feature of the study is its focus on competitive differentiation. The report evaluates how leading vendors are positioning their offerings across AMI integration, communication technologies, analytics platforms, and utility-specific service models. It also incorporates recent developments that illustrate how the market is evolving in practice. For example, municipal deployments such as the meter upgrade completion by City of Bloomington Utilities have demonstrated how hourly readings, customer portals, and leak alerts can be operationalized at the local level. Similarly, the Town of Ocean City began upgrading residential and commercial meters to a new AMI system to improve accuracy and enable remote readings, while the North Tahoe Public Utility District resumed a large-scale meter replacement program supported by federal WaterSMART grant funding and cellular networks for real-time leak detection. These projects highlight the practical deployment environment in which vendors, utilities, and technology partners must compete and collaborate.
The research also integrates regulatory and funding developments that shape market conditions. The EU Horizon 2020 SmartWaterNet project approval in May 2025, for instance, underscores the broader policy support for advanced smart water networks and meter deployment across Europe. At the same time, initiatives such as the WaterSMART grant secured by North Tahoe Public Utility District and RF-based AMI projects supported by Hubbell in Santa Barbara illustrate how financial incentives and regulatory alignment can accelerate adoption timelines. Understanding these dynamics is essential for anticipating demand acceleration points and evaluating the resilience of regional market strategies.
Strategic Implications for Market Participants
For technology providers and equipment manufacturers, the market trajectory suggests that product strategy must extend beyond meter hardware. Competitors are increasingly winning on the strength of communication reliability, integration ease, analytics depth, and utility workflow alignment. Companies that can demonstrate measurable reductions in leak-related losses, operational labor, and billing inefficiencies will be better positioned to secure large-scale contracts and long-term utility relationships.
For utilities and public-sector organizations, the decision to invest in smart water meters is no longer a question of if but how to sequence deployment for maximum operational return. Priorities include selecting communication architectures that fit local infrastructure, ensuring interoperability with existing systems, and building the data capabilities needed to translate meter telemetry into operational action. Projects that combine funding support, regional partnerships, and clear performance metrics are likely to achieve faster and more durable ROI.
For investors and strategic partners, the market presents a landscape where growth is driven by both infrastructure modernization and technology convergence. The moderate concentration of market share leaves room for specialized entrants and regional leaders, but success will depend on credible utility engagement, proven field performance, and the ability to navigate differing regulatory environments. Monitoring recent developments, such as the integration of AI-driven analytics into water infrastructure and the expansion of cellular and 5G-enabled monitoring solutions, will be important for evaluating which players are likely to capture disproportionate value over the forecast period.
Smart Meters Market
Conclusion
The smart water meters market is entering a phase of sustained expansion defined by infrastructure urgency, technological maturation, and increasing reliance on data-driven utility operations. With a forecast compound annual growth rate of 9.6 percent and a projected market size reaching $16.29 billion by 2032, the sector offers significant strategic opportunity for organizations that can align product capabilities, deployment partnerships, and market timing with the realities of utility decision-making. This research provides the analytical foundation required to navigate that opportunity with confidence. To access the full segmentation detail, competitive benchmarking, regional demand mapping, and forward forecast breakdowns that support executive planning, we invite you to explore the complete Smart Water Meters Market report on our website.
For detailed analysis of this topic, please visit the official page: Smart Water Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


