



L-Carnitine Market Hits $216.4M in 2025, Forecasts 5.2% CAGR to Surpass $307.8M by 2032

Strategic Intelligence for the L-Carnitine Market: Navigating Growth and Compliance in 2026 and Beyond
The global landscape for L-Carnitine is undergoing a subtle but significant transformation. As stakeholders across pharmaceuticals, nutraceuticals, and animal nutrition evaluate their positioning for 2026, the need for precise, forward-looking intelligence has never been more critical. Our latest market research report offers a comprehensive examination of this evolving sector, delivering actionable insights designed to support strategic decision-making in an environment defined by steady expansion and shifting regulatory parameters.
Market Trajectory and Growth Dynamics
The L-Carnitine market has demonstrated consistent resilience over the past half-decade, with historical performance from 2020 through 2025 establishing a foundation of incremental yet reliable growth. Valuations have progressed from approximately 178.5 million USD in 2020 to an estimated 216.4 million USD by 2025, reflecting a compound annual growth rate of 5.2 percent across the forecast horizon extending to 2032. This trajectory suggests that the market will reach roughly 307.8 million USD by the close of the projection period, indicating sustained demand drivers rather than episodic spikes.
For enterprise leaders, this growth profile carries important implications. A moderate CAGR of this magnitude typically signals a mature but still expanding category, where competitive advantage is increasingly derived from operational efficiency, regulatory preparedness, and product differentiation rather than pure volume play. The forecast period through 2032 provides sufficient runway for organizations to calibrate capacity investments, assess supply chain vulnerabilities, and align product portfolios with emerging application trends. Readers seeking a complete breakdown of segment-level performance, regional distributions, and application-specific revenue splits are encouraged to review the full report, where granular data tables and analytical commentary provide the granularity required for precise planning.
Structural Forces Shaping the Industry
Several structural dynamics are actively reshaping how value is created and captured within the L-Carnitine ecosystem. On the supply side, synthesis pathways involving fermentation or chemical processes remain cost-intensive, introducing persistent pressure on pricing architectures across global markets. Raw material price fluctuations have emerged as a recurring obstacle for manufacturers operating within complex international supply chains, compelling producers to adopt more sophisticated hedging strategies, diversify sourcing arrangements, and optimize production yields to protect margins.
Regulatory developments are simultaneously redefining market access parameters. In October 2025, Lonza Sales AG received an EFSA scientific opinion renewal for the authorization of L-Carnitine and L-Carnitine L-tartrate as feed additives for all animal species, a decision that reinforces the regulatory legitimacy of carnitine-based feed applications within European markets and provides downstream assurance for feed-grade manufacturers. More recently, in January 2026, the EU Commission enacted Regulation (EU) 2026/140, revising Maximum Residue Levels for carnitine derivatives. This regulatory adjustment concentrates market access among active pharmaceutical ingredient manufacturers that maintain documented safety verification infrastructure, effectively raising the compliance bar for exporters seeking to serve European downstream customers.
On the demand and therapeutic side, the FDA has approved both oral and intravenous L-Carnitine specifically for the treatment of primary and secondary carnitine deficiency resulting from inborn errors of metabolism, reinforcing a clinically validated application base that anchors pharmaceutical-grade demand. Meanwhile, product innovation continues to broaden the commercial footprint: in January 2025, Otsuka Pharmaceutical launched the ENSOLID clinical nutrition formula incorporating L-Carnitine, illustrating how established players are integrating carnitine into specialized nutritional formulations that bridge medical and wellness positioning.
These intersecting forces create a landscape where regulatory literacy, supply chain resilience, and application diversification converge as decisive competitive factors. The full report dedicates substantial analysis to each of these dynamics, offering scenario-based commentary and mapping their implications across different business models and geographic contexts.
Competitive Landscape and Strategic Positioning
The competitive architecture of the L-Carnitine market reflects a diversified set of participants spanning pharmaceutical manufacturing, nutritional ingredient supply, research reagent distribution, and animal nutrition specialization. Market concentration metrics indicate that the top three firms command approximately 25.4 percent of total revenue, while the top five collectively account for roughly 31.7 percent. This moderate concentration suggests that while leading players hold meaningful share, the market remains sufficiently fragmented to allow new entrants and regional specialists to carve out differentiated positions through quality assurance, regulatory compliance, and application-specific expertise.
Worldwide Pharmaceutical Grade L-Carnitine Market
Among the prominent incumbents, Lonza Ltd., headquartered in Basel, Switzerland, stands out for its specialization in L-Carnitine production under the Carnipure® brand, serving pharmaceutical, nutraceutical, and animal feed applications with a recognized quality signature. Biosint S.p.A., based in Italy, produces L-Carnitine as an active pharmaceutical ingredient and feed additive, positioning itself at the intersection of clinical-grade and agricultural-grade demand. In China, Northeast Pharmaceutical Group Co., Ltd., located in Shijiazhuang, Hebei, manufactures L-Carnitine and derivatives for pharmaceutical and supplement use, reflecting the growing capability of regional producers to serve both domestic and export markets.
Additional participants broaden the competitive mosaic. Cayman Chemical Co., based in Ann Arbor, Michigan, supplies L-Carnitine for research, diagnostics, and nutritional products, catering to precision-oriented downstream users. Kaiyuan Hengtai Nutrition Co., Ltd. and ChengDa Medicines Co., Ltd., both operating from China, produce L-Carnitine for animal nutrition and human health supplements, as well as pharmaceutical and veterinary applications, respectively. Huanggang Huayang Medicines Co. Ltd. supplies L-Carnitine for pharmaceutical and feed markets, while AdvaCare Pharma USA LLC, headquartered in Cheyenne, Wyoming, offers L-Carnitine in OTC supplements and formulations. Tokyo Chemical Industry Co., Ltd. provides L-Carnitine as a fine chemical and research reagent, and Merck KGaA and Sigma-Aldrich contribute to the laboratory and industrial supply chain, distributing and supplying L-Carnitine for research and manufacturing contexts.
These firms illustrate the breadth of the value chain and the varied strategic priorities that define success in this market. For competitive intelligence purposes, our report examines each profiled company with a structured assessment encompassing geographic footprint, product architecture, regulatory posture, and recent strategic moves. The objective is to equip clients with the comparative context required to evaluate partnership opportunities, assess competitive threats, and identify whitespace where brand positioning or application focus can be sharpened. Detailed competitive profiles, including URL references and operational summaries, are provided in the complete publication.
L-Carnitine Market
Report Architecture and Practical Utility
Our market research is designed as an operational tool rather than a static data repository. The report integrates multiple analytical dimensions that collectively support strategic planning across commercial, operational, and regulatory functions. Core components include a comprehensive market overview grounded in historical performance and forecast modeling, regional and segment-level analyses that map opportunity distribution without diluting methodological rigor, and an application-based evaluation that distinguishes demand patterns across dietary supplements, sports nutrition, functional beverages, animal feed, and pharmaceutical formulations.
The competitive landscape section delivers structured company profiles, share distribution insights, and an assessment of concentration dynamics that help stakeholders gauge the intensity of rivalry and the potential for consolidation. Recent developments are tracked chronologically and contextualized within broader industry trends, ensuring that regulatory renewals, product launches, and policy adjustments are interpreted not as isolated events but as signals within an evolving market architecture. Supply-side considerations, including synthesis cost structures and raw material volatility, are examined alongside demand-side drivers to provide a balanced view of margin risk and pricing strategy levers.
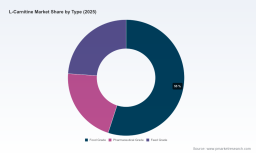
Importantly, the report avoids superficial aggregation. Where segment splits, regional valuations, and application revenue figures exist, they are presented with sufficient depth to enable scenario planning, yet the publication intentionally directs readers to the full dataset for precise percentage breakdowns and detailed tabulations. This approach ensures that the executive summary establishes analytical credibility while preserving the incentive to access the complete research deliverable for decision-grade detail.
Strategic Implications for 2026 Decision-Making
For organizations formulating strategy in 2026, several priorities emerge from the intersection of growth trends, regulatory evolution, and competitive structure. First, compliance infrastructure is no longer a back-office function but a market access determinant. The January 2026 EU regulation on Maximum Residue Levels means that exporters and API manufacturers must demonstrate robust safety verification capabilities to maintain eligibility in European channels. Companies that treat regulatory documentation as a strategic asset will be better positioned to secure supply agreements and differentiate from competitors with weaker compliance postures.
Second, supply chain design requires renewed attention. Cost-intensive synthesis pathways and raw material volatility demand proactive inventory management, multi-source procurement strategies, and continuous yield optimization. Firms that integrate these considerations into their operational planning can convert supply-side pressure into a margin defense advantage, particularly in price-sensitive segments where pass-through mechanisms are constrained.
Third, application diversification offers a pathway to resilience. While dietary supplements and sports nutrition continue to represent substantial demand centers, functional beverages, animal feed, and pharmaceutical formulations each present distinct growth drivers and regulatory contexts. Understanding the revenue contribution and growth characteristics of each application stream enables portfolio managers to balance exposure, align R&D priorities, and tailor marketing messaging to the expectations of different downstream audiences.
Fourth, competitive awareness must extend beyond headline market shares. The moderate concentration profile of this market means that regional specialists, research-grade suppliers, and formulators can exert meaningful influence within niche channels. Monitoring the activities of firms such as Lonza, Biosint, Northeast Pharmaceutical, Cayman Chemical, and the broader set of Chinese and American participants provides early warning of capacity expansions, regulatory milestones, and product launches that may reshape regional pricing or availability.
Accessing the Full Intelligence Package
This article offers a high-level orientation to the forces shaping the L-Carnitine market and the strategic questions that organizations should be addressing as they move through 2026. However, the density of market activity, the granularity of segment performance, and the specificity of regulatory developments require a more detailed analytical apparatus than a summary can provide. The complete report delivers exhaustive market sizing across the full forecast horizon, segment- and region-level revenue distributions, application-based growth narratives, and structured competitive profiles that collectively support rigorous planning.
Decision-makers who require precise percentage splits, detailed regional valuations, and comprehensive company assessments will find the full publication essential. We invite you to access the complete market research deliverable to obtain the data depth and analytical context necessary for confident strategic execution.
For detailed analysis of this topic, please visit the official page: L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


