



PW Consulting Sunglasses Market to Hit $310M by 2032, 6.5% CAGR Drives Fashion Demand

Beyond the Lens: Strategic Imperatives in the 2026 Sunglasses Market
The global sunglasses market is undergoing a period of structural acceleration. As consumer behavior shifts toward health-conscious eyewear, outdoor recreation, and expressive fashion, industry stakeholders face a complex matrix of growth opportunities, supply chain friction, and intensifying competitive dynamics. At PW Consulting, we have synthesized multi-year historical tracking with forward-looking modeling to deliver a comprehensive market research report designed explicitly for executive decision-making in 2026 and beyond. This article outlines the strategic architecture of our analysis, demonstrates how macroeconomic and competitive forces are reshaping the landscape, and highlights the actionable intelligence packaged within the full study.
The Growth Trajectory: What the Numbers Reveal
Historical tracking from 2020 through 2025 illustrates a market that has consistently outpaced broader consumer goods benchmarks. Revenue climbed from approximately 120.0 million USD in the early part of the decade to 190.0 million USD by the 2025 base year, reflecting a compound trajectory that signals durable demand rather than cyclical spikes. Looking ahead, our forecast window extends through 2032, projecting continued expansion with a 6.5 percent compound annual growth rate. By the close of the forecast period, market revenue is expected to surpass 310.0 million USD, driven by sustained polarization adoption, lifestyle integration of performance eyewear, and expanding accessibility in emerging consumer segments.
These figures are not abstract indicators. They represent a市场 that is maturing in its segmentation logic, where premiumization, functional utility, and sustainability are converging to redefine purchasing behavior. Yet the aggregate numbers only tell the first layer of the story. The real strategic value lies in understanding how value is distributed across product architectures, consumer applications, and geographic corridors—and where intervention points exist for brands, distributors, and private-label operators.
Why 2026 Demands a Strategic Reset
Several concurrent pressures make this an inflection point for industry leadership. On the regulatory front, tariff revisions and material duties have introduced immediate cost volatility. The Vision Council has documented additional 20 percent duties on Chinese-origin materials that took effect in early 2025, directly impacting eyewear production expenses and forcing supply chain recalibration. Alongside these, 25 percent tariffs on goods originating from Mexico and Canada, effective in March 2025, are reshaping cross-border sourcing economics for optical products. Further compounding the landscape, steel and aluminum duties at 25 percent, implemented in mid-March 2025, have increased input costs for frame manufacturing, prompting manufacturers to evaluate material substitution, regional sourcing shifts, and inventory buffering strategies.
Simultaneously, the competitive field is consolidating around premium brand portfolios, polarized lens differentiation, and sustainability narratives. Industry participants are no longer competing solely on price or style; they are competing on lens technology performance, brand equity depth, and the ability to align product development with evolving outdoor and lifestyle use cases. These dynamics require decision-makers to move beyond static market snapshots and adopt scenario-aware planning that accounts for tariff exposure, raw material innovation, and partnership realignment.
What Our Report Delivers: A Framework for Action
The PW Consulting Sunglasses Market research report is engineered to translate macro trends into operational clarity. It provides a rigorous examination of the competitive hierarchy, product segmentation evolution, application-driven demand shifts, and regional momentum patterns. The study is structured to support multiple enterprise use cases, from portfolio optimization and go-to-market positioning to supply chain risk assessment and M&A targeting.
Key components of the report include:
- Historical baseline analysis spanning 2020 to 2025, establishing growth patterns and structural breakpoints
- Forward-looking revenue projections through 2032, anchored by a 6.5 percent CAGR and calibrated for demand continuity and price architecture shifts
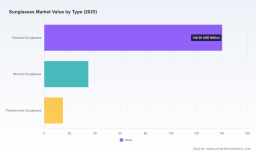
- Segment-by-segment evaluation across product type, application category, and regional distribution, revealing where value concentration and growth acceleration intersect
- Competitive profiling of leading manufacturers and brand custodians, with emphasis on portfolio strategy, lens technology positioning, and channel orientation
- Supply chain and regulatory dynamics analysis, mapping tariff impacts, material cost pressures, and sustainability-driven product mix changes
- Actionable strategic recommendations for brand builders, contract manufacturers, distributors, and retail operators
Importantly, the report does not merely describe the market. It stress-tests strategic choices against the forces that will define the next planning cycle. Readers will gain visibility into where polarization and photochromic technologies are expanding functional relevance, where luxury and lifestyle applications anchor the revenue core, and how outdoor and sports segments are carving out differentiated demand pathways. The analysis also tracks how leading players are responding through acquisitions, campaign launches, and trade-show innovations that signal the direction of industry investment.
Competitive Architecture: Leaders, Niche Players, and Strategic Moves
The competitive landscape is characterized by a concentrated top tier and a dynamic field of specialized operators. Established groups anchor the market through portfolio breadth, brand licensing strength, and global distribution networks. EssilorLuxottica, headquartered in France, leverages signature names including Ray-Ban, Oakley, Costa, and Oliver Peoples, while maintaining extensive production of polarized and photochromic lenses worldwide. Its scale and brand architecture position it as a central force in both fashion-driven and performance-oriented segments.
Kering Eyewear, based in Italy, operates a complementary luxury and performance-oriented model under Maui Jim, Gucci, and other premium brands, with strong emphasis on polarized lenses and adventure-aligned collections. The group’s recent activity underscores its focus on experiential brand storytelling: in early 2026, Maui Jim unveiled a global advertising campaign for its spring-summer collection, reinforcing themes of adventure and connection while highlighting polarized lens differentiation for outdoor use.
Luxury Sunglasses Market
Safilo Group, also Italian, produces and distributes sun and optical frames with a pronounced focus on lifestyle, sport, and performance sunglasses. In May 2026, the company announced a binding agreement to acquire Spy+ and Serengeti, a move that expands its sunglasses portfolio and signals a clear intent to strengthen its foothold in performance and specialty categories. This type of portfolio expansion is particularly instructive for market observers, as it illustrates how incumbents are consolidating capability to capture higher-value demand pools.
De Rigo Vision stands out for its sustainability-forward product development. The company specializes in eco-friendly and high-performance sunglasses, with frames incorporating recycled inputs and lifestyle collections designed to align with environmentally conscious consumer preferences. Industry data indicates that its eco-frame collections, built with over 60 percent recycled inputs, achieved a 12 percent unit mix shift toward sustainable SKUs in EMEA retailers during peak seasons. This suggests that sustainability is no longer a peripheral differentiator; it is becoming a measurable driver of assortment composition and retailer acceptance.
Marcolin, also headquartered in Italy, manufactures sunglasses for licensed brands including Tom Ford, Adidas, and Timberland, balancing fashion credibility with performance relevance. Its business model highlights the strategic importance of licensing partnerships in scaling brand presence while maintaining manufacturing discipline.
On the specialized end of the spectrum, companies such as Maui Jim and goodr illustrate how focused product strategies can capture distinct demand niches. Maui Jim provides polarized sunglasses for fishing, outdoor sports, and adventure, supported by proprietary lens technology that emphasizes visual clarity and glare reduction. goodr, meanwhile, targets the accessible performance segment with affordable, polarized active sunglasses designed for no-slip and no-bounce stability, demonstrating that functional reliability can drive loyalty even in price-sensitive environments. Bajio Sunglasses rounds out this category with a premium polarized focus on fishing and water sports, reinforcing the value of adventure-oriented positioning and specialized use-case marketing.
These competitive profiles are not static. They reflect an industry where brand architecture, lens technology, and channel alignment are being continuously re-weighted. By mapping these players and their recent strategic actions, the report reveals where capability gaps exist, where acquisition opportunities may arise, and how differentiation pathways are evolving.
Market Dynamics: Regulation, Materials, and the Cost of Doing Business
The sunglasses market in 2026 is being shaped as much by external policy and material realities as by consumer preferences. Tariff actions have introduced immediate and medium-term cost pressure. The additional 20 percent duties on Chinese-origin materials are disrupting eyewear production costs and supply chains, forcing manufacturers and import-dependent operators to reconsider sourcing exposure and inventory posture. At the same time, 25 percent tariffs on goods from Mexico and Canada are elevating production costs and prompting supply chain adjustments for optical products. The steel and aluminum duties at 25 percent further complicate frame manufacturing economics, especially for brands that rely on metal components or mixed-material constructions.
In response, industry participants are evaluating a range of mitigation strategies. Some are accelerating material substitution programs, others are diversifying supplier geographies, and still others are recalibrating product mix toward SKUs with better margin resilience. The regulatory environment is likely to remain a decision variable rather than a transient disruption, which means strategic planning must incorporate tariff sensitivity as a core assumption rather than an exceptional scenario.
Materials innovation is proceeding in parallel. Sustainability-driven frame development is moving from pilot initiatives to commercial scaling, with recycled content, lightweight performance polymers, and eco-conscious finishing processes gaining retailer and consumer acceptance. Where these initiatives succeed, they do more than improve environmental positioning; they create product differentiation that can support premium pricing, enhance assortment distinctiveness, and align with procurement requirements in increasingly sustainability-conscious retail channels.
How to Use This Research for 2026 Decision-Making
The strategic utility of this report lies in its multi-lens design. For brand and portfolio leaders, the segmentation analysis clarifies where demand is accumulating and which product attributes are driving repeat purchase behavior. For supply chain and operations teams, the regulatory and materials discussion provides context for cost modeling, sourcing diversification, and inventory strategy. For corporate development and investment teams, the competitive profiling and recent industry developments offer a basis for evaluating partnership structures, acquisition targets, and white-space positioning.
The report is built to support scenario-based planning. Decision-makers can use the forecast framework to test revenue assumptions against different price, mix, and channel strategies. They can assess how tariff-related cost changes might influence margin structures across product types and applications. They can also evaluate whether sustainability-oriented product development is likely to translate into measurable assortment advantages in specific retail environments. In each case, the goal is not to provide a single forecast line, but to equip leaders with the analytical architecture needed to make defensible, forward-looking choices.
The full study goes further still. It details the structural logic behind demand concentration, traces how product type and application categories interact with regional momentum, and identifies the strategic implications of recent competitive activity. It also contextualizes the market within broader consumer trends, including the growing importance of eye protection, the blending of fashion and function, and the role of outdoor recreation as a durable demand engine. Together, these elements form a decision-ready intelligence package for organizations that need to act with precision in a market where the stakes are rising.
Conclusion: Turning Market Visibility into Strategic Advantage
The sunglasses market is expanding with clarity and complexity. Revenue is climbing, product categories are evolving, and competitive players are reshaping their portfolios in response to both consumer demand and external pressure. In this environment, generic market summaries are insufficient. What leaders need is a structured, evidence-based view of where growth is originating, how competitive advantage is being built, and which operational adjustments will protect margins while enabling expansion.
PW Consulting’s Sunglasses Market research report is designed for exactly that purpose. It combines historical rigor, forward-looking projection, competitive intelligence, and dynamic context into a single analytical framework. The insights within are intended to inform product strategy, sourcing decisions, brand positioning, and investment prioritization throughout 2026 and the extended forecast horizon. To access the complete segmentation detail, company profiles, forecast breakdowns, and strategic recommendations, we invite you to explore the full report on our website.
Sunglasses Market
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


