



PW Consulting: Greenhouse Soil Market to Grow at 5.5% CAGR, Reaching $6,856.6 Million by 2032

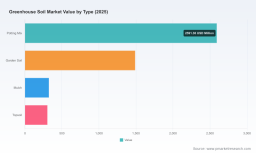
Cultivating Resilience: Inside the Greenhouse Soil Market of 2026
Executive Overview
The global greenhouse soil market stands at a definitive inflection point. As controlled environment agriculture matures from a niche practice into a foundational pillar of modern food and ornamental production, the substrate systems that support root health, nutrient delivery, and water retention have never commanded greater strategic attention. Our latest market research publication dissects this rapidly evolving landscape, offering enterprise leaders a rigorous, forward-looking blueprint for capital allocation, product positioning, and supply chain resilience through the end of the decade.
Drawing on validated historical data spanning 2020 through 2025 and extending into a comprehensive forecast window that runs through 2032, this analysis quantifies the trajectory of an industry transitioning from incremental expansion to structurally accelerated growth. The narrative is clear: greenhouse soil is no longer a commodity input. It is a performance-critical variable where formulation science, regulatory compliance, and regional sourcing economics converge. Organizations that treat it as such will capture disproportionate share; those relying on legacy assumptions will face margin compression, compliance risk, and competitive displacement.
This preview outlines the strategic architecture of our full report. It highlights how the market has evolved, what forces are actively reshaping competitive dynamics, and which analytical frameworks decision-makers need to navigate 2026 with precision. The complete study contains granular segmentation breakdowns, regional demand profiles, channel distribution insights, and detailed competitor scorecards. Every dataset, model, and executive recommendation has been engineered for immediate application in product roadmapping, procurement strategy, partnership evaluation, and market entry planning.
Potting Soil Market
Market Trajectory and Structural Evolution
The commercial foundation of the market has demonstrably expanded over the past half-decade. Historical revenue progression from 2020 through 2025 reflects sustained growth driven by intensified horticultural output, shifting consumer preferences toward greenhouse-propagated produce, and the steady professionalization of containerized growing operations. The momentum does not plateau at the current baseline. Our forecasting framework projects continued revenue expansion across the 2026 to 2032 window, anchored by a compound annual growth rate of 5.5 percent. By the close of the forecast period, total industry revenue is positioned to approach its largest scale yet, reflecting both volume acceleration and value migration toward higher-performance substrate formulations.
This growth curve is not uniform. The market is being pulled forward by a convergence of agronomic innovation, regulatory realignment, and operational cost pressures that are simultaneously expanding opportunity pools and compressing traditional margin structures. Understanding where value pools will concentrate, which product architectures will command premium pricing, and which geographic corridors will experience the steepest demand inflection requires a granular view that our full research delivers. What can be stated with confidence is that the structural drivers behind the forecast are durable, interconnected, and unlikely to reverse in the short to medium term.
For corporate strategy teams, this trajectory presents two immediate imperatives. First, historical performance must be disaggregated to identify which product categories, distribution channels, and application environments are genuinely expanding versus those merely riding broader market sentiment. Second, forward-looking models must incorporate the cost and compliance variables that will redefine substrate economics well before 2030. The complete report provides the analytical scaffolding to do both, enabling leaders to separate signal from noise and align investment horizons with realistic demand pathways.
Forces Reshaping the Competitive Landscape
Industry dynamics in 2026 are being dictated by an unusually dense cluster of external pressures. Regulatory action is accelerating across multiple jurisdictions, fundamentally altering raw material availability and formulation requirements. In the United Kingdom, the nursery sector is executing a government-mandated peat reduction pathway that targets complete phase-out for the hobby segment by 2025 and extends a 100 percent peat reduction mandate to professional greenhouse media by 2030. Across the North Sea, a Finnish greenhouse cooperative has already enforced a threshold requiring less than 30 percent peat content across all production soil mixes, a threshold that has displaced legacy suppliers from established vendor lists and forced rapid rebalancing of sourcing portfolios.
These regulatory shifts are intersecting with environmental policy at scale. Broader European peatland protection frameworks are actively accelerating the substitution of traditional peat inputs with alternative substrates such as wood fiber and coir within greenhouse applications. The transition is not merely compositional; it reshapes procurement logistics, processing requirements, quality control standards, and end-user performance expectations. At the same time, operational cost pressures are mounting. Rising fuel and transportation expenses tied to peat moss and perlite supply chains have elevated both labor and material costs associated with preparing greenhouse soil blends, squeezing operators that lack diversified input strategies or localized processing capabilities.
Greenhouse Soil Market
Counterbalancing these pressures is a policy environment that increasingly rewards climate-aligned soil practices. Funding mechanisms structured under the USDA Inflation Reduction Act are supporting climate-smart agricultural practices, with greenhouse soil amendments explicitly positioned within programs targeting soil carbon sequestration and emission reduction. This creates a strategic opening for suppliers and growers who can document verifiable environmental benefits, align with measurement and reporting standards, and articulate substrate choices within broader sustainability reporting frameworks. The market is no longer pricing soil purely on agronomic performance; compliance posture, input traceability, and carbon impact narratives are becoming material differentiators.
Opportunities and Strategic Pivot Points for Enterprises
The intersection of regulation, input economics, and policy support is generating a set of actionable strategic openings for organizations prepared to act with precision.
- Alternative substrate leadership: The regulatory trajectory away from peat-heavy formulations is creating durable demand for engineered blends that maintain water retention, aeration, and nutrient stability while meeting compliance thresholds. Suppliers that can validate performance parity or superiority with lower-peat or peat-free architectures will capture premium positioning as professional growers recalibrate their purchasing criteria.
- Sustainability-linked procurement: As greenhouse operators face increasing scrutiny from downstream retail, food service, and ornamental distribution channels, substrate sourcing decisions are becoming embedded in broader environmental compliance and reporting obligations. Documented carbon impact, responsible sourcing credentials, and transparent input provenance are transitioning from marketing attributes to procurement requirements.
- Formulation and processing innovation: The cost escalation observed in traditional input transport and preparation is rewarding organizations that can localize blending operations, optimize substrate particle morphology, and reduce dependency on volatile logistics corridors. Operational efficiency in media preparation is emerging as a direct margin lever, not merely an operational convenience.
- Policy-aligned product architecture: Climate-smart funding pathways are expanding the addressable economic rationale for certain soil amendments and substrate strategies. Companies that design product portfolios compatible with sequestration objectives and emission-reduction frameworks can unlock incentive-aligned demand that is less sensitive to pure commodity pricing cycles.
Capturing these opportunities requires more than product iteration. It demands a disciplined assessment of which customer segments are most exposed to regulatory change, which distribution networks can accelerate reformulation adoption, and where competitive moats can be built through certification, consistency, and technical support. The full study maps these decision vectors against quantified demand pathways so that leadership teams can prioritize initiatives with the highest probability of return.
Competitive Ecosystem and Strategic Positioning
The competitive field is anchored by a cohort of established producers with deep formulation expertise, extensive substrate manufacturing capabilities, and long-standing relationships across professional horticulture and commercial greenhouse channels. Scotts Miracle-Gro Company operates at scale as a major producer of organic and conventional greenhouse soil mixes and potting substrates tailored for professional growers. Sun Gro Horticulture maintains its position as the largest North American producer of horticultural peat moss and bark-based growing media blends designed for greenhouse environments. In Europe, Klasmann-Deilmann GmbH has built a leading profile in peat-based and alternative growing media substrates optimized for controlled cultivation, while Premier Tech Ltd. supplies specialized growing media and greenhouse substrates engineered for commercial horticulture applications.
The broader ecosystem extends across organic-focused formulators, regional performance specialists, and European substrate manufacturers. FoxFarm Soil and Fertilizer Co. produces organic greenhouse soil amendments and ready-to-use potting mixes, while Michigan Peat Company remains a key producer of peat-based greenhouse soil mixes and custom horticultural substrates. Espoma Company manufactures natural and organic greenhouse soil products and blends, and Good Earth Horticulture provides high-performance greenhouse soil solutions directed at commercial growers. Florentaise supplies specialized greenhouse and nursery growing media substrates, and ASB Greenworld contributes European production of peat and bark-based growing media for greenhouse use.
Strategic activity among these players is intensifying, reflecting both the opportunity set and the compliance-driven urgency to secure reliable input channels and differentiated product architectures. In April 2025, Griffin Greenhouse Supplies announced a master distributor agreement with Hortus U.S.A. covering growing media products including greenhouse soil substrates, a move that expands channel reach and consolidates distribution leverage for participating partners. In September 2025, HydraFiber introduced HydraTerra, a new formulation combining HydraFiber Advanced Substrate with Sunterra Canadian Sphagnum Peat for greenhouse growers, signaling continued investment in engineered blends that balance performance characteristics with evolving input preferences.
The market concentration profile indicates a moderately fragmented but strategically consolidating landscape. Competitive advantage is increasingly determined not only by volume capacity but by the ability to navigate peat reduction mandates, secure alternative input supply, and deliver consistent blend quality across diverse regional requirements. The complete report provides detailed competitor profiling, strategic posture assessment, and supply chain positioning analysis that enables procurement, product, and corporate development teams to benchmark their standing and identify displacement or partnership opportunities with precision.
What the Full Research Delivers
This preview is designed to establish the substantive depth of our analysis while preserving the granular intelligence that decision-makers require for execution. The complete Greenhouse Soil Market research study expands every dimension introduced here into an actionable intelligence framework. It delivers validated market sizing and forward projections across the full forecast horizon, supported by methodology-transparent modeling that can be integrated into internal planning processes. It disentangles demand by product architecture, application environment, and regional corridor without relying on superficial aggregates, enabling teams to identify where growth is structurally rooted versus cyclically inflated.
The study also provides operational and strategic content built for immediate application:
- Comprehensive segmentation analysis that isolates demand drivers, pricing dynamics, and substitution risk across core product categories and use environments
- Regional demand profiles that map growth intensity, regulatory exposure, and input sourcing realities to support capacity planning and channel strategy
- Competitor benchmarking and strategic posture mapping that clarify where incumbents are reinforcing positions, where vulnerabilities are opening, and where partnership or acquisition logic is most compelling
- Supply chain and raw material assessments that quantify exposure to peat reduction mandates, alternative substrate transitions, transportation cost volatility, and processing constraints
- Regulatory and policy scenario analysis that frames how peat bans, emission-focused directives, and climate-smart funding pathways will reshape procurement criteria and product requirements through 2032
- Actionable strategic recommendations designed for product roadmapping, market entry evaluation, supplier diversification, and commercial positioning in a compliance-sensitive procurement environment
Every section of the report is structured to answer the questions that sit at the center of enterprise planning: Where is durable demand forming? Which formulation strategies will remain viable under tightening input regulations? How should organizations balance cost pressure with performance and sustainability expectations? And which competitive moves will create defensible positioning in a market where regulatory and environmental variables are no longer peripheral concerns?
How Leaders Can Use This Intelligence in 2026
The strategic value of this research lies in its capacity to convert complex market movement into executable direction. In 2026, substrate procurement and product strategy cannot be managed as static line items. They are dynamic decisions shaped by regulatory timing, input substitution velocity, regional demand divergence, and the growing premium on verifiable sustainability performance. Organizations that treat greenhouse soil as a strategic variable rather than a standardized input will be better positioned to protect margins, secure reliable supply, and align product portfolios with the procurement criteria that professional growers are actively revising.
The full study is built for executive review, category management, R&D planning, and commercial strategy. It provides the quantification required for budgeting and forecasting, the competitive context needed for positioning and partnership evaluation, and the regulatory framing necessary to anticipate compliance-driven shifts before they become cost events. For organizations evaluating market entry, regional expansion, formulation diversification, or supplier consolidation, the report offers a structured basis for scenario planning and risk-adjusted decision-making.
The market trajectory is clear, the pressure points are identifiable, and the competitive stakes are rising. What remains is disciplined interpretation and timely execution. Our complete Greenhouse Soil Market research closes the gap between high-level trend awareness and the operational intelligence required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Greenhouse Soil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


