



PW Consulting: Calcium Sulfate Market Hits $288.9M in 2025, Poised for 4.2% CAGR Growth to 2032

Strategic Outlook: Navigating the Calcium Sulfate Market Through 2026 and Beyond
The global industrial landscape for calcium sulfate is undergoing a nuanced transformation, driven by shifting construction demands, evolving regulatory frameworks, and the strategic repositioning of key material suppliers. For executives and portfolio managers operating within the industrial minerals, agriculture, and specialty chemicals sectors, 2026 represents a pivotal inflection point. Decisions made today regarding supply chain diversification, grade-specific sourcing, and regional expansion will directly determine competitive positioning through the end of the decade. Our latest research initiative examines the structural forces shaping this market, providing a decision-ready architecture for navigating both near-term volatility and long-term growth trajectories.
Market Architecture and Macro Trajectory
Calcium sulfate continues to anchor a multifaceted value chain that spans construction infrastructure, agricultural soil management, food and pharmaceutical formulation, and broad industrial processing. Historical movement from 2020 through 2025 illustrates a market that has demonstrated steady resilience despite macroeconomic headwinds, raw material supply constraints, and regional policy realignments. Revenue expanded from approximately 235.18 Million USD in 2020, reached 246.45 Million by 2021, fluctuated marginally at 246.44 Million in 2022, and then accelerated to 269.81 Million in 2023 as construction and industrial activity rebounded across major economies. By 2024, the figure climbed to 278.75 Million, and the current baseline for 2025 sits at 288.90 Million USD.
Magnesium Sulfate Market
These sequential expansions reflect more than incremental demand; they signal the maturation of application ecosystems and the gradual integration of calcium sulfate into higher-value manufacturing and processing workflows. Looking forward, the forecast window extending to 2032 maps a clear upward pathway. Revenue is projected to advance toward 302.82 Million in 2026, followed by sustained growth across subsequent years, ultimately approaching 385.32 Million by the close of the decade. This trajectory corresponds to a compound annual growth rate of 4.2 percent, a figure that underscores moderate but structurally reliable expansion.
For strategic planners, this pace of growth carries distinct implications. A 4.2 percent CAGR suggests a market that is neither volatile nor speculative, but rather characterized by methodical procurement cycles, grade-driven pricing premiums, and regional supply-demand mismatches. Companies that align procurement calendars with forecast inflection points, rather than reacting to annual spot fluctuations, will be better positioned to manage working capital and secure favorable contract terms. The underlying forecast also reveals where capacity planning, inventory optimization, and downstream application development will yield the highest returns, and our full report isolates those leverage points with granular timeline mapping.
Segmentation Dynamics and Application Realities
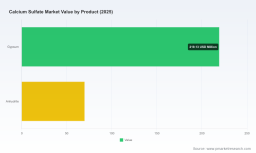
The calcium sulfate market is inherently multi-dimensional, spanning variations in mineral forms, grade specifications, and end-use applications. Gypsum and anhydrite represent the two foundational product categories, each with distinct handling characteristics, processing requirements, and downstream suitability. Technical-grade, food-grade, and pharmaceutical-grade specifications further fragment procurement strategies, as material purity, trace element limits, and certification pathways vary significantly across industries. The construction sector remains the dominant application anchor, drawing substantial volume for wallboard manufacturing, cement conditioning, and specialty finishing products. Agricultural applications constitute another meaningful demand stream, particularly where calcium sulfate serves as a soil amendment and secondary nutrient carrier. Food and beverage formulation, pharmaceutical and personal care manufacturing, and broader industrial processing round out a diversified application matrix.
Understanding how these segments interact is essential. Industrial buyers do not simply purchase a homogenous material; they navigate a tiered landscape where grade purity, origin traceability, moisture content, and particle morphology directly influence processing efficiency and final product quality. The construction industry's volume requirements often create baseline demand floors, while food-grade and pharmaceutical-grade channels operate on tighter specification windows and command differentiated pricing structures. Agricultural demand, meanwhile, fluctuates with planting cycles, regional soil conditions, and the availability of competing amendments. Our detailed analysis dissects these interdependencies and maps where procurement teams should prioritize grade flexibility versus specification rigidity, but the exact volume distributions, regional consumption allocations, and application-level revenue splits are reserved for the complete intelligence package. The objective of this overview is to establish the structural logic; the report delivers the operational quantification needed to act on it.
Competitive Landscape and Strategic Postures
The competitive environment in calcium sulfate is defined by a blend of industrial mineral processors, regional suppliers, and specialized formulators who serve distinct end markets. Several established players illustrate the strategic diversity within this space. One prominent supplier headquartered in Mamaroneck, New York, offers calcium sulfate in dihydrate, hemihydrate, and anhydrous forms, sourcing from both domestic and international origins while targeting industrial and agricultural buyers. Another U.S.-based processor, operating out of Mentor, Ohio, functions as a supplier and industrial mineral extender, distributing anhydrous and dihydrate forms for additive and formulation applications. In China, a manufacturer and exporter based in Xingtai, Hebei, processes food-grade, anhydrous, and specialized calcium sulfate products used in baking ingredients, tofu coagulation, and pharmaceutical contexts. Separately, a U.S. operation headquartered in Illinois has focused on granular calcium sulfate fertilizer blends designed to deliver secondary nutrients such as calcium and sulfur for agricultural use.
The strategic postures of these companies reveal broader market dynamics. Some entrants emphasize multi-origin sourcing to mitigate supply disruptions and maintain price competitiveness, while others concentrate on grade specialization to capture higher-margin formulation and food-adjacent channels. Agricultural-focused producers increasingly differentiate through nutrient delivery formats and soil-health positioning. These approaches reflect a market where scale alone is insufficient; sourcing reliability, specification consistency, regulatory compliance, and application-specific technical support increasingly determine purchasing decisions. The report includes a structured competitive assessment that maps these differentiation vectors across the leading participants, including recent operational milestones such as new facility openings and capacity expansions that reshape regional supply availability. Full competitor benchmarking, sourcing footprints, and strategic capability comparisons are available within the published intelligence, enabling procurement and strategy teams to calibrate vendor selection with precision.
Regulatory, Supply-Side, and Operational Headwinds
Beyond demand-side growth, calcium sulfate markets are being shaped by regulatory evolution and supply-side constraints that carry direct operational consequences. Government agencies in key regions have begun issuing handling and management guidance for by-product gypsum derived from flue gas desulfurization processes, aiming to facilitate agricultural and industrial reuse while strengthening environmental compliance standards. These guidance frameworks influence how secondary calcium sulfate streams can be processed, certified, and commercialized, adding both opportunity and compliance complexity for processors and end users.
Simultaneously, the raw material environment is experiencing structural adjustments. Synthetic gypsum production has declined as coal-fired power facilities continue to close, reducing the availability of a historically important secondary feedstock for calcium sulfate processing. This shift affects cost structures, supply continuity, and regional sourcing strategies, particularly for industrial buyers who have relied on recovered gypsum streams to balance procurement economics. The intersection of cleaner environmental standards and reduced synthetic feedstock availability is prompting a recalibration of primary versus secondary sourcing mixes. Organizations that anticipate these supply-side transitions, evaluate primary deposit access, and build qualification pathways for alternative feedstocks will face less disruption than those depending on legacy synthetic supply networks. The complete report examines these regulatory and supply dynamics in context, including their projected impact on pricing behavior, processing investments, and regional availability throughout the forecast window.
Strategic Implications for Corporate Decision-Making
For executives evaluating market entry, capacity investment, sourcing strategy, or product portfolio development, the calcium sulfate landscape offers both predictable growth and targeted risk. The 4.2 percent CAGR indicates that expansion will be driven by steady industrial and agricultural demand rather than speculative cycles, which favors disciplined long-term planning. However, the segmentation complexity means that growth opportunities are uneven across grades, applications, and geographies. Companies that treat calcium sulfate as a single commodity risk missed margin opportunities in higher-specification channels, while organizations that over-specialize without securing diversified supply may face cost volatility when regulatory or feedstock conditions shift.
Effective positioning requires a multi-layered strategy. Procurement teams must evaluate supplier qualification frameworks that account for both origin traceability and grade reliability. Operations leaders should assess whether existing facilities can accommodate shifts in feedstock composition and specification requirements as synthetic gypsum volumes change. Market development teams need to identify where food-grade and pharmaceutical-grade applications offer margin premiums and where agricultural channels provide volume stability. Regulatory affairs functions should monitor handling and reuse guidance that may expand downstream utilization of by-product streams while introducing new compliance obligations. Each of these considerations carries distinct return profiles and implementation timelines, and our research isolates where strategic capital and operational attention will generate the strongest outcomes.
Calcium Sulfate Market
How the Full Report Supports Your Next Move
This overview establishes the strategic contours of the calcium sulfate market and the rationale for informed, forward-looking decision-making in 2026. The complete market research publication extends this foundation into a fully operational intelligence framework. It delivers a detailed segmentation analysis across product types, grade specifications, and application channels, alongside regional market sizing and consumption trajectories. It maps the competitive landscape with structured company profiles, recent operational developments, and capability comparisons that help procurement and strategy teams evaluate vendor alignment. It integrates regulatory and supply-side developments into scenario-based implications, allowing decision-makers to test sourcing and pricing assumptions under changing feedstock and compliance conditions.
Most importantly, the report translates market structure into actionable milestones. It identifies where demand acceleration is most likely, which grade channels merit specification investment, and where sourcing diversification will provide the greatest resilience. For leaders responsible for capital allocation, supply chain design, or market expansion, the publication functions as a single-source reference for aligning commercial strategy with market reality. To access the complete segmentation data, regional breakdowns, competitive benchmarking, and forecast pathways, readers are invited to explore the full research publication. The detailed intelligence contained within is designed to support precise, confident decisions as the calcium sulfate market continues its measured ascent through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


