



PW Consulting: E-Liquids Market Hits $1.125B in 2025, Projects 12.58% CAGR Through 2032

Navigating the Vapor Shift: Strategic Intelligence for the 2026 E-Liquids Market
The global e-liquids market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, understanding the precise trajectory of this sector is no longer optional—it is a prerequisite for sustainable growth. Our latest market research publication offers a comprehensive roadmap for navigating the complexities of the e-liquids landscape from 2026 through 2032. This report is designed not merely as a data repository, but as a strategic asset for decision-makers who need to anticipate shifts rather than react to them.
For industry stakeholders, the difference between market participation and market leadership often comes down to the quality of intelligence available at the point of decision. The following analysis outlines the macro-economic environment, the competitive architecture, and the regulatory currents shaping the sector, demonstrating why deep-dive research is essential for capital allocation, product development, and market entry strategies in the coming year.
Macro-Economic Trajectory and Growth Fundamentals
The historical performance of the e-liquids market demonstrates a robust upward trend, reflecting the continued shift away from traditional combustion products toward vaporized nicotine delivery systems. Between 2020 and 2025, the sector experienced consistent expansion, building a substantial revenue base that sets the stage for the forecast period. Current estimates place the total market valuation at USD 1,125.0 Million in 2025, marking a significant increase from the 2020 baseline.
Looking forward, the growth momentum is projected to accelerate. Our forecast models indicate that the market will reach USD 1,265.53 Million in 2026, continuing to climb steadily toward a projected valuation of USD 2,470.0 Million by 2032. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 12.58 percent during the 2026-2032 forecast period. Such a rate suggests that the e-liquids sector will continue to outpace many traditional consumer goods categories, driven by innovation in device compatibility, flavor profiling, and evolving regulatory approvals that legitimize specific product categories.
For strategic planners, these figures represent more than just top-line growth; they indicate a maturing market where consolidation and specialization are becoming key drivers. The sheer scale of the projected revenue unit expansion over the next six years implies significant opportunities for players who can secure supply chain stability and navigate the varying compliance landscapes across different jurisdictions.
Market Structure and Concentration Dynamics
One of the most critical aspects of strategic planning in this sector is understanding the competitive density. The market is not uniformly distributed; rather, it exhibits a high degree of concentration among key players. Current analysis reveals a CR3 (Concentration Ratio of the top three firms) of 62.0 percent, while the CR5 extends to 78.0 percent. This level of concentration highlights the dominance of established tobacco giants and specialized nicotine technology firms that have secured significant market share through brand recognition, regulatory approvals, and distribution networks.
This concentration has profound implications for new entrants and existing mid-sized players. It suggests that while the total addressable market is growing, the pathway to capturing share requires distinct differentiation. Companies cannot simply rely on volume; they must offer unique value propositions, whether through proprietary flavor technologies, superior hardware integration, or specialized OEM/ODM manufacturing capabilities. The gap between the top-tier concentrated firms and the long tail of the market is where strategic agility becomes most valuable.
Our research delves into the specific structural dynamics that allow certain entities to maintain these high concentration levels while others struggle to gain footholds. Understanding the barriers to entry, the cost structures of compliant manufacturing, and the distribution leverage held by incumbents is vital for any organization considering M&A activity or organic expansion.
Competitive Landscape and Key Players
The competitive environment is a mix of established multinational tobacco corporations and specialized e-liquid manufacturers. This duality creates a complex ecosystem where traditional smoke-free portfolios intersect with agile, niche liquid producers. Our report profiles the strategies and operational focuses of the industry's pivotal companies.
Major multinational entities such as Philip Morris International Inc., British American Tobacco PLC, Imperial Brands PLC, and Japan Tobacco International are heavily invested in the e-vapor space. These companies integrate e-liquids into broader smoke-free business portfolios, leveraging their existing distribution channels and regulatory expertise to maintain market presence. Their approach often focuses on standardized, compliant products that align with global regulatory trends.
On the other side of the spectrum are specialized manufacturers and technology developers. JUUL Labs Inc. and Logic Technology Development LLC have historically focused on specific delivery systems and cartridge formats, emphasizing authorized variants and specific flavor profiles. NJOY LLC continues to push pod formats designed for ease of use and nicotine delivery efficiency. Meanwhile, specialized manufacturers like Hangsen have carved out a significant role as world-leading OEM/ODM partners, providing solutions to markets across over 86 countries. This highlights a crucial supply-side dynamic: the reliance of many brands on specialized manufacturing partners to scale production while adhering to quality guidelines.
Independent premium brands such as Ruthless Vapor, Mister-E-Liquid, and Vape Base Ltd also play a crucial role in shaping consumer preferences, particularly in the flavored e-liquid segment. These companies often lead in flavor innovation and community engagement, setting trends that larger conglomerates may later adopt or regulate around. Our analysis examines how these different tiers of competitors interact, compete for shelf space, and navigate the varying regulatory requirements that define their respective operational zones.
Regulatory Environment and Industry Dynamics
No strategic discussion of the e-liquids market is complete without addressing the regulatory environment, which remains the single most significant variable affecting market access and profitability. As of May 2026, the regulatory landscape is characterized by a patchwork of authorizations and duties that vary significantly by region.
In the United States, the FDA continues to be the gatekeeper. As of May 2026, the FDA has authorized 45 ENDS products, representing the only ones legally marketed in the United States. This tight control over market entry creates a high barrier for new products but provides stability for those who secure authorization. Recent developments underscore this reality; in June 2025, the FDA granted premarket authorizations to Swedish Match North America, Inc. for tobacco-flavored e-liquid products. Furthermore, in May 2026, the FDA authorized the marketing of four Glas ENDS products featuring e-liquid pods with non-tobacco and non-menthol flavors. This authorization is particularly significant as it signals a potential pathway for flavor diversity under strict compliance conditions, a key area of interest for consumer growth.
Across the Atlantic, the UK has introduced new fiscal measures. On 01 April 2026, the UK HMRC opened applications for the Vaping Products Duty of £2.20 per 10ml on all vaping liquids. This duty imposes a direct cost on production and distribution, which will inevitably influence pricing strategies and margin structures for companies operating in or exporting to the UK market. Strategic budgeting for 2026 and beyond must account for these duty implications to avoid margin erosion.
State-level actions also contribute to the complexity. The Virginia Annual Report on Liquid Nicotine and Nicotine Vapor Products, published in February 2026, records 13 manufacturers certified and $380,000 in revenue collected, indicating active state-level monitoring and taxation. Similarly, Arkansas requires manufacturers to certify compliance with directory rules for vapor products and e-liquid products, with penalties for non-compliance starting November 2025. These fragmented regulatory requirements necessitate a robust compliance infrastructure that our report details extensively.
Industry Activity and Capacity Expansion
Despite regulatory headwinds, industry activity remains vigorous. Corporate strategies reflect a commitment to growth and capacity building. In February 2026, VPZ announced a multi-million-pound investment to expand e-liquid manufacturing capacity and launch new retail locations. This move signals confidence in the long-term demand for compliant vaping products and highlights the importance of physical retail presence alongside manufacturing scalability.
Trade activity also continues to facilitate commercial connections. The Total Product Expo in April 2026 featured a dedicated e-liquids and vapes category with significant commercial activity for independent retailers. Such events are critical nodes in the supply chain, where manufacturers connect with distributors and retailers to secure shelf space and negotiate terms for the upcoming fiscal year. Our market research captures the sentiment and transaction trends observed at these key industry gatherings, providing qualitative context to the quantitative data.
E-cigarette Market
Strategic Value of the 2026 Market Research
Given the interplay of high market concentration, rapid growth projections, and a shifting regulatory moat, generic market data is insufficient for high-stakes decision-making. This report provides the granular intelligence required to transform uncertainty into strategy.
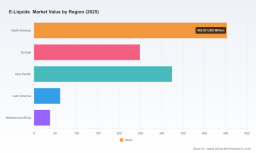
Our analysis goes beyond surface-level metrics to explore the segmentation splits that drive revenue. We examine the performance of different product types, including Pre-Filled and Bottled E-Liquids, and analyze how application preferences such as Tobacco, Fruit, and Menthol flavors influence purchasing behavior in different regions. However, the specific weightings and regional revenue distributions are detailed within the full report to maintain competitive confidentiality and ensure that subscribers receive the most actionable, non-public insights.
The core value of this research lies in its operational applicability. For investors, it offers a clear view of where capital is flowing and which segments offer the highest risk-adjusted returns. For manufacturers, it identifies gaps in the supply chain and opportunities for OEM/ODM expansion. For distributors and retailers, it highlights the flavor profiles and product formats that are gaining traction in compliant markets.
Readers are encouraged to access the full source webpage to retrieve the complete segmentation data, detailed company profiles, and specific regional forecasts. Only through the comprehensive dataset can organizations build the precise financial models and market entry plans required to succeed in this high-growth, high-regulation environment. The summary provided here establishes the strategic necessity of the research; the full document delivers the executional intelligence.
Conclusion
The e-liquids market is poised for substantial expansion over the next six years, but the path to capturing this value is fraught with regulatory and competitive challenges. With a projected market size nearing USD 2,470.0 Million by 2032 and a CAGR of 12.58 percent, the opportunity is significant. However, success will belong to those who can navigate the FDA authorization landscape, adapt to duties like the UK Vaping Products Duty, and compete effectively within a market where the top five players already control 78.0 percent of the share.
E-Liquids Market
PW Consulting's latest market research equips stakeholders with the necessary tools to make informed decisions. By integrating historical performance data, current regulatory facts, and competitive profiles, this report serves as a foundational document for strategic planning in 2026. We invite you to review the complete findings on our website to fully leverage this intelligence for your organization's growth objectives.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


