



PW Consulting: 6.2% CAGR Drives Bike Racks Market to $2.5B by 2032

Strategic Intelligence in Motion: Navigating the Global Bike Racks Market Through 2032
The transportation of bicycles has evolved from a niche logistical consideration into a critical component of broader mobility, urban planning, and recreational infrastructure strategies. As cycling gains sustained momentum across commuter corridors, adventure tourism routes, and institutional facilities, the hardware designed to safely secure and transport these assets has become a focal point for manufacturers, distributors, and public-sector procurement teams alike. Our latest market research publication examines the structural trajectories, competitive pressures, and regulatory inflection points shaping the global bike racks market, offering a decision-ready framework for executives who must allocate capital, refine product portfolios, and position for sustained growth through the end of the decade.
Market Trajectory and the 2026 Decision Window
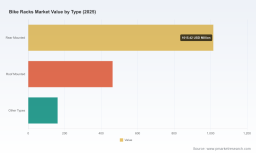
Historical valuation patterns through the base year demonstrate a consistent upward arc, with market revenue expanding steadily from just above twelve hundred million USD in the early 2020s to a projected 1,720.23 million USD in 2026. The forecast horizon extending to 2032 indicates that this momentum is neither anomalous nor cyclical; rather, it reflects entrenched shifts in consumer transportation preferences, municipal infrastructure investments, and the ongoing normalization of multi-modal travel. A compound annual growth rate of 6.2 percent across the evaluation window underscores a market that is maturing with predictable velocity, even as regional demand centers and application-specific monetization strategies diverge in meaningful ways.
Bike Locks Market
For strategic planners operating in 2026, this trajectory carries several operational implications. First, the growth baseline is sufficiently stable to validate mid-cycle capacity investments, but precision in timing matters. Second, the divergence between macroeconomic expansion and segment-level absorption rates means that top-line projections must be calibrated against channel readiness, distribution density, and regulatory compliance costs. Third, the market’s structural resilience creates an environment where differentiation, rather than volume alone, becomes the primary lever for margin preservation. Our analysis isolates these dynamics with forward-looking scenarios that stress-test demand elasticity, supply chain responsiveness, and competitive pricing behavior under varying economic assumptions.
Report Architecture and Actionable Intelligence
This publication is structured to move beyond descriptive market sizing and into the operational mechanics of value creation. The analytical framework integrates baseline demand mapping, segmentation interrogation, competitive benchmarking, and regulatory durability assessments into a single decision-support instrument. Readers will encounter practical tools designed to translate market signals into procurement, R&D, and channel strategy actions:
- Comprehensive segmentation mapping that dissects revenue concentration across mounting configurations, vehicle-class applications, and end-use environments, revealing where adoption curves are steepening and where saturation thresholds are approaching.
- Competitive positioning matrices that evaluate incumbents across product architecture, geographic footprint, distribution agility, and service-model differentiation, enabling benchmarking against peers that have successfully converted product innovation into share gains.
- Regulatory and compliance sensitivity analysis that tracks certification requirements, recall exposure, and fatigue-testing standards, providing risk-adjusted context for product launches and production planning.
- Scenario-based forecasting modules that model revenue pathways under alternative penetration rates, pricing architectures, and policy-support assumptions, helping teams stress-test investment theses before committing capital.
- Channel and procurement pathway reviews that examine how public-sector grant programs, institutional purchasing cycles, and retail ecosystem dynamics shape order velocity and lifecycle revenue capture.
Each section is calibrated for executive utility rather than academic completeness. The objective is to equip strategy, product management, and commercial leadership teams with a defensible basis for prioritizing development pipelines, allocating marketing resources, and negotiating supplier or distribution agreements with awareness of where structural advantages are forming.
Competitive Landscape and Strategic Positioning
The competitive architecture of the market is defined by a relatively fragmented but increasingly specialized participant base, with leadership concentration remaining disciplined. Industry concentration metrics indicate that the top three enterprises command approximately 30 percent of aggregate revenue, while the top five collectively hold roughly 35 percent. This structure suggests that scale advantages exist without creating insurmountable barriers for focused specialists who can differentiate through engineering, application fit, or regional service intensity.
Within this ecosystem, firms are pursuing divergent value propositions aligned to distinct customer priorities. Commercial and institutional-oriented manufacturers concentrate on durable mounting systems, post and ring configurations, and lift-assisted storage solutions designed for high-traffic public and facility environments. These players emphasize longevity, vandalism resistance, and integration with municipal or campus infrastructure specifications. Vehicle-transport specialists, by contrast, optimize for hitch compatibility, aerodynamic clearance, load stability, and ease of deployment, often aligning product architecture with specific vehicle platforms and recreational use cases. A third cohort explores modular storage and wall-mounted solutions that address space-constrained residential and indoor environments, leveraging pivoting or tiered mechanics to maximize utility within limited footprints.
Strategic positioning increasingly hinges on the ability to bridge engineering rigor with user experience. Companies that have built recognizable reputations in this space typically anchor their portfolios around a core mounting philosophy while extending into adjacent application lanes where channel relationships and service assurance can compound advantage. Product development cadence, warranty architecture, and compatibility assurance have become as commercially significant as raw manufacturing scale. For entrants or incumbents evaluating partnership, acquisition, or geographic expansion opportunities, the market rewards clarity of application focus and disciplined go-to-market execution over broad, undifferentiated product proliferation.
Regulatory, Technical, and Operational Undercurrents
Hardware reliability and compliance performance are no longer peripheral concerns; they are central to brand durability and procurement eligibility. Certification expectations and dynamic fatigue testing standards require manufacturers to validate vertical load resistance and long-cycle structural integrity under realistic stress conditions. These technical mandates influence material selection, assembly tolerances, and validation costs, and they increasingly shape the competitive baseline for any firm seeking institutional contracts or retail placement in regulated channels.
The compliance environment has also been shaped by recent recall activity affecting specific hitch-mounted and carrier product lines. Investigations into pivot-cam engagement integrity, latch-mechanism wear, and service requirements on particular models have highlighted how design validation, production consistency, and post-market service responsiveness can directly influence market standing. These episodes are instructive for procurement teams and product developers alike, reinforcing the importance of supplier due diligence, documentation traceability, and proactive field-service planning when integrating third-party components or scaling production across model years.
Beyond compliance, recent program-level developments signal how public-sector incentives and product-cycle timing can accelerate adoption in targeted segments. Grant programs supporting safer school routes and institutional cycling infrastructure have expanded procurement pathways for commercial-grade parking and storage hardware, creating demand pockets that reward readiness, specification alignment, and reliable fulfillment capacity. At the same time, spring and summer product introductions from established manufacturers indicate an ongoing commitment to refinement in hitch, roof, and trunk-mounted configurations, sustaining consumer-facing innovation even as the broader market shifts toward more normalized demand patterns. The interplay between policy-supported procurement and consumer-product refreshes adds a layer of temporal complexity to demand forecasting, one that our research models explicitly address.
Bike Racks Market
2026 Strategic Priorities for Market Participants
Executing effectively in this environment requires a disciplined balance of investment, compliance readiness, and channel alignment. Organizations that treat the market as a single homogeneous opportunity tend to over-index on volume assumptions and under-allocate to the application-specific requirements that actually drive conversion and retention. The research suggests several priorities that should shape executive agendas in 2026:
- Clarify application focus before expanding SKU breadth. Revenue concentration across mounting styles and vehicle-class applications indicates that adjacency expansion works best when anchored by proven channel demand and engineering compatibility rather than speculative diversification.
- Integrate compliance and durability validation into product roadmaps. Certification expectations and recall precedents make structural testing and quality assurance not just technical concerns but commercial differentiators that influence procurement trust and retail shelf performance.
- Align capacity and service planning with procurement cycles. Public-sector grant timing, institutional purchasing calendars, and seasonal product launches create demand pulses that reward flexible fulfillment and proactive field support rather than static inventory assumptions.
- Benchmark competitive advantage through ecosystem strength. Distribution relationships, installation support, warranty responsiveness, and compatibility assurance increasingly determine share movement, especially in a market where leadership concentration remains moderate and specialization is viable.
- Adopt scenario-based capital allocation. Because segment-level absorption and regional readiness can diverge from aggregate growth signals, investment decisions should be tested against multiple penetration and pricing pathways rather than a single baseline forecast.
Conclusion: Why This Research Matters Now
The global bike racks market is not simply expanding; it is reorganizing around clearer application boundaries, more demanding reliability expectations, and a competitive field that rewards focused differentiation. The 6.2 percent compound annual growth trajectory through 2032 provides a credible macro foundation, but the operational decisions that determine who captures disproportionate value will be made at the level of product architecture, compliance readiness, channel execution, and procurement timing. Our full research publication delivers the segmentation resolution, competitive mapping, regulatory context, and scenario modeling required to move from awareness to action. For executives responsible for product strategy, commercial planning, and investment allocation in 2026 and beyond, the detailed intelligence within this report is designed to sharpen judgment and reduce exposure to assumption-driven decisions.
For detailed analysis of this topic, please visit the official page: Bike Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


