



Pw Consulting: Torsional Vibration Damper Market Hits $1.8B in 2025, Projects 5.5% CAGR to 2032

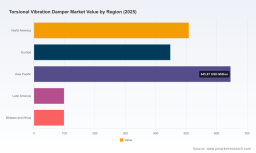
Navigating the Next Wave: Strategic Intelligence for the Global Torsional Vibration Damper Market (2026–2032)
Executive Perspective: Why This Study Matters for 2026 Decision-Making
As industrial engines, powertrains, and heavy-duty drivelines face tighter NVH mandates and more aggressive downsizing roadmaps, the torsional vibration damper market has entered a phase of structural acceleration. This study is designed as a decision-grade intelligence asset for executives, product planners, and supply-chain leaders who must align capital allocation, R&D roadmaps, and commercial positioning with the realities of the 2026–2032 forecast window. Rather than offering a static snapshot, the analysis is built to support scenario planning, pricing strategy, and competitive positioning in a market where technological differentiation increasingly determines margin survival.
The global revenue trajectory reflects a market that has moved beyond post-pandemic normalization and is now being shaped by powertrain hybridization, emission-driven crankshaft protection requirements, and the cost dynamics of engineered elastomers and silicone-based fluids. From a historical base of approximately 1.2 billion USD in 2020, the market expanded to roughly 1.8 billion USD by 2025, with momentum carrying into a projected 1.95 billion USD in 2026. Over the full forecast horizon, the market is expected to advance at a compound annual growth rate of 5.5 percent, reaching approximately 2.8 billion USD by 2032. These headline figures establish the scale of opportunity, but the strategic value of this research lies in how that growth is distributed across product architectures, application-driven demand, regional maturity curves, and the competitive responses of incumbents and challengers.
Market Dynamics: Forces Shaping Demand, Cost, and Margin Structure
The growth path is not uniform. Several interlocking dynamics are reshaping both the demand side and the cost structure for damper manufacturers, and the study unpacks each of them with operational granularity.
- Regulatory and NVH pressure is becoming a primary demand catalyst. Stricter emission and noise regulations continue to tighten at a pace that is increasing certification and testing protocols for damper manufacturers in many mature markets. Because torsional vibration dampers protect crankshaft integrity and reduce NVH-related emissions impact, compliance-driven design cycles are extending the lifecycle relevance of dampers even as powertrain architectures evolve.
- Powertrain evolution is changing the technical spec window. Downsized high-torque internal combustion engines, hybrid system integration, and higher-performance stationary power applications are creating new vibration profiles that legacy single-stage designs do not always address efficiently. This is driving interest in multi-stage elastomer solutions, viscous systems suited to severe-duty cycles, and tuned steel spring geometries that balance performance with cost of ownership.
- Raw material volatility is reshaping cost assumptions. Fluctuations in petrochemical markets have raised input costs for engineered elastomers and silicone-based fluids used in damper production. For suppliers, this creates a margin environment where material strategy, formulation innovation, and supplier diversification are no longer support functions but core commercial levers.
- OEM pricing pressure is rewarding differentiated scale. Sustained OEM price-reduction programs in high-volume automotive contracts compress margins for suppliers lacking differentiated technology or scale advantages. This means competitive positioning increasingly depends on the ability to offer validated performance, integration-ready designs, and cost-efficient manufacturing footprints rather than commoditized component supply.
These dynamics do not operate in isolation. They interact with product architecture choices, application mix, and regional demand maturity, producing a market in which growth is real but uneven. The report maps these interactions so decision-makers can distinguish between structural expansion and transient demand spikes, and align their strategies accordingly.
What the Study Delivers: Operational Content for Commercial and Technical Leaders
This research is structured to serve multiple internal audiences. For strategy and corporate development teams, it provides a macro-to-micro framework that links market size evolution to the drivers behind it. For product and engineering leaders, it translates demand-side requirements into technology roadmaps, supplier selection criteria, and integration considerations. For commercial and sales leadership, it outlines where demand intensity is building, which application segments are expanding most reliably, and how competitive intensity varies by type and geography.
The core analytical sections include:
- Market sizing and forward modeling. A detailed historical reconstruction and forecast engine covering 2020 through 2032, anchored in the latest observed base-year data and projected through the forecast period with scenario-sensitive CAGR logic.
- Segment-level demand architecture. A structured breakdown by product type, application, and region that reveals where concentration is high, where growth is broadening, and which sub-markets are likely to become decisive for capacity and portfolio planning. The report deliberately avoids publishing the granular split values in this preview; those figures, along with their growth velocities and share trajectories, are embedded in the full dataset and accessible through the complete study.
- Competitive positioning and capability mapping. Profiles of the companies that define the market’s technical and commercial frontier, with attention to product families, end-market coverage, and the types of innovation each player is advancing.
- Recent corporate activity and signal analysis. A curated review of product unveilings, technical webinars, trade-show showcases, and aftermarket expansions that indicate where incumbents are placing bets and how fast commercialization cycles are moving.
- Risk, margin, and sourcing considerations. An integrated discussion of raw material cost exposure, certification burden, OEM price dynamics, and the operational choices that determine whether suppliers capture value or merely participate in volume growth.
Throughout, the study emphasizes actionable inference over descriptive enumeration. The aim is to help teams answer questions such as: Which technology families are likely to command premium positioning? Where do certification and integration requirements make supplier switching costly? Which regional markets offer durable growth rather than short-cycle fluctuations? And how should organizations interpret recent corporate moves as leading indicators rather than isolated events?
Competitive Landscape: Who Is Shaping the Market and How
The torsional vibration damper market is defined by a diverse but concentrated set of players, spanning European engineering heritage, North American heavy-duty and performance expertise, Japanese manufacturing scale, and global Tier-1 integration capability. The study examines the companies that are most influential in setting technical expectations, securing OEM relationships, and expanding aftermarket reach.
A central theme is the coexistence of multiple damper architectures, each with distinct performance and cost profiles. Elastomer-based solutions remain foundational, particularly where multi-stage rubber engineering is advancing beyond traditional single-stage layouts. Viscous shear-type dampers continue to hold strategic importance in severe-duty and reciprocating compressor applications, where reliability and controlled damping characteristics are paramount. At the same time, tuned steel spring configurations and integrated dual-mass flywheel approaches are gaining attention for their ability to decouple torsional vibrations within transmission and driveline systems. Companies operating across these families are increasingly competing on integration readiness, validation depth, and the ability to adapt designs to hybrid and downsized engine environments.
The competitive field includes firms with specialized viscous damper leadership, organizations building on centrifugal pendulum-type absorbers and arc spring dampers for powertrain systems, and suppliers extending torsional damping into transmission, clutch, and driveline integration. There are also players focused on aftermarket and heavy-duty components, as well as manufacturers that provide elastomeric and specialized vibration control components for broader NVH portfolios. Across this landscape, the report assesses not only who is present, but where each company is positioning for the next cycle of demand.
Recent activity reinforces that positioning is moving quickly. In late 2025, a major industry webinar addressed next-generation viscous torsional vibration dampers for downsized high-torque internal combustion engines and hybrid systems, signaling a clear technical focal point for the coming years. In early 2026, a milestone advancement in elastomer engineering was unveiled for multi-stage rubber torsional vibration dampers, accelerating commercialization over traditional single-stage layouts. Around the same period, severe-duty independent aftermarket portfolios were expanded with advanced heavy-duty damping components and belt tensioners optimized for specific high-output engines, while reciprocating compressor applications saw new damper solutions showcased and ordered through established OEM channels. These moves are not isolated product updates; they are indicators of where engineering attention, certification effort, and commercial resources are being concentrated.
Strategic Imperatives for 2026 and Beyond
For organizations operating in, supplying, or investing alongside this market, the 2026–2032 period will reward clarity of posture. The study translates the market’s trajectory into several decision-relevant imperatives.
First, technology selection is becoming a margin decision as much as a performance decision. As OEMs face tighter NVH and emissions standards and run sustained price-reduction programs, suppliers that can deliver validated damping performance with scalable, cost-efficient architectures are better positioned to preserve margins. The report examines how elastomer, viscous, and tuned mechanical approaches compare in the context of these pressures, and where differentiation is most defensible.
Second, application mix matters more than headline growth. The automotive segment remains a dominant share of demand, but industrial machinery and other applications are shaping a broader growth base that can reduce dependency on any single cycle. Understanding which applications expand through compliance-driven replacement, which grow through new powertrain designs, and which depend on severe-duty durability is essential for demand planning and capacity strategy.
Worldwide Automotive Torsional Vibrational Damper Market
Third, regional maturity is uneven, and growth leadership can shift as local regulations, fleet turnover, and industrial demand evolve. The full study maps these regional patterns without reducing them to simplistic rankings, allowing readers to evaluate where near-term volume is coming from and where longer-term expansion is building.
Fourth, recent corporate signals should be read as forward indicators. Technical webinars, elastomer engineering unveilings, aftermarket expansions, and compressor-focused showcases all point to a market in which the next wave of value capture will go to firms that can move from proven concept to commercialized, validated, and integration-ready solution with speed and scale.
How to Use This Preview and Where the Full Intelligence Resides
This article is intentionally structured as a strategic preview. It establishes the scale of the market, the drivers behind the 5.5 percent compound growth path, the competitive logic shaping the field, and the operational questions that executives should be asking in 2026. What it does not do is expose the granular segmentation values, region-by-region revenue splits, type-level share distributions, or application-level market figures that form the analytical backbone of the complete study.
Those detailed figures are not omitted for stylistic reasons. They are reserved for the full report because they are precisely the data points that enable precise capacity planning, pricing strategy, segment entry evaluation, and competitive benchmarking. Once published in a preview setting, they lose their value as decision-grade intelligence and can be used by competitors before a company has completed its own internal assessment.
The complete study provides access to the underlying segmentation structure, forecast sensitivity, company-by-company positioning context, and the recent-deviation analysis needed to interpret raw material, regulatory, and OEM pricing dynamics with confidence. It is designed to support board-level review, product roadmap decisions, sourcing strategy, and market-entry evaluation without forcing teams to reconstruct conclusions from public signals alone.
Closing Case for the Study
The torsional vibration damper market is entering a period in which growth is supported by regulatory pressure, powertrain evolution, and durable industrial demand, but profitability will depend on technical differentiation, cost discipline, and the ability to interpret competitive signals early. This research translates that environment into a structured, forward-looking framework for 2026 decision-making. It offers enough analytical depth to confirm the study’s rigor, while preserving the detailed segmentation and company-level figures that make the full report a practical tool rather than a general overview.
Torsional Vibration Damper Market
For leaders who need to move from market awareness to concrete action, the complete study delivers the depth required to convert a 5.5 percent CAGR trajectory and a 2.8 billion USD 2032 outlook into targeted strategy. The preview makes the case for the study; the full report provides the intelligence to act on it.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


