



PW Consulting: Fatigue Machine Market to Hit USD 731.77M by 2032, 6.2% CAGR

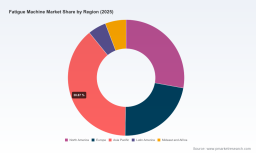
Strategic Intelligence for the Fatigue Machine Market: Navigating Growth and Competition Through 2032
The global landscape for fatigue testing equipment is entering a decisive phase of evolution. As manufacturing sectors face mounting pressure to ensure material durability, lifecycle reliability, and compliance with rigorous safety standards, the demand for precision fatigue machines has become a critical enabler of industrial resilience. PW Consulting’s latest market research on the Fatigue Machine Market offers a comprehensive, data-rich foundation for strategic planning in 2026 and beyond. This report is not merely a retrospective analysis; it is a forward-looking decision-support tool designed to help executives, procurement leaders, engineers, and investors navigate a market undergoing steady expansion, technological refinement, and intensifying competitive dynamics.
The fatigue machine market has demonstrated consistent upward momentum over the past half-decade. Historical valuation data from 2020 through 2025 reveals a clear trajectory of growth, with the market expanding from approximately $360 million to $483 million. This progression reflects sustained capital allocation toward materials testing infrastructure, driven by the needs of automotive validation, aerospace certification, civil engineering assessment, and advanced research applications. Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market anticipated to reach roughly $732 million by the end of the decade. The implied compound annual growth rate of 6.2 percent underscores a market that is not experiencing volatility-driven spikes, but rather a methodological, demand-led expansion rooted in engineering requirements and regulatory expectations. For enterprise decision-makers, this steady growth curve signals a market where long-term capacity planning, technology investment, and supply chain alignment can yield compounding strategic advantages.
Why This Research Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the fatigue testing ecosystem face a conjunction of forces that make high-quality market intelligence indispensable. On the demand side, industries are pushing harder against the boundaries of material performance. Lightweight composites, additively manufactured components, and next-generation battery structures are redefining validation protocols. On the supply side, input cost volatility and competitive pricing pressure are constraining margin expansion for equipment manufacturers, placing a premium on scale, integrated supply chains, and differentiated service capabilities. Simultaneously, evolving regulatory and quality standards are steering procurement decisions toward certified, specification-compliant fatigue testing equipment, making compliance architecture a core competitive variable rather than a back-office function.
In this environment, strategic choices made in 2026 will shape competitive positioning for years. Whether a manufacturer is evaluating capacity expansion, a laboratory is planning capital procurement, an automotive or aerospace supplier is defining testing partnerships, or an investor is assessing market entry and consolidation opportunities, the cost of incomplete intelligence is high. The PW Consulting study is structured to reduce that uncertainty. It provides a granular view of market sizing, segmentation behavior, competitive positioning, and the regulatory and technological currents shaping procurement patterns. By aligning these dimensions into a single analytical framework, the report enables leaders to move from reactive market observation to proactive portfolio and investment strategy.
What the Report Delivers: Operational Content and Analytical Depth
This market research is designed for execution, not just awareness. The report systematically unpacks the Fatigue Machine Market across multiple analytical layers, giving readers a clear map of where value is created, where competition is intensifying, and where strategic openings exist. Core components include:
Fatigue Machine Market
- A detailed historical and forecast revenue analysis covering the base year 2025 and extending through the 2026 to 2032 forecast horizon, allowing readers to benchmark current market conditions against projected growth pathways.
- Segmentation analysis that breaks down demand patterns by technology type, application domain, and geographic footprint, helping stakeholders identify which subsegments are accelerating, which are maturing, and where resource allocation should be prioritized.
- Competitive landscape profiling that examines the strategic posture, product capabilities, geographic presence, and recent activity of leading manufacturers, enabling readers to assess relative market strength and potential partnership or competitive threats.
- Market concentration insights that clarify the share structure among top performers, offering perspective on the balance between established scale players and emerging regional contenders.
- Industry dynamics coverage that integrates regulatory developments, standards symposia, product launches, and major test milestones into a cohesive view of the forces shaping purchasing behavior and technology roadmaps.
Each section is built to translate data into action. Rather than presenting isolated figures, the report contextualizes numbers within operational realities: how different frequency ranges align with specific testing requirements, how application segments differ in procurement cycles and specification sensitivity, and how regional demand profiles interact with local manufacturing capacity and certification ecosystems. For teams responsible for market entry, product positioning, pricing strategy, or long-term capacity planning, this structure provides a practical scaffold for decision-making.
Competitive Landscape: Scale, Specialization, and Strategic Moves
The fatigue machine market is characterized by a blend of globally established testing equipment manufacturers and regionally focused producers that compete on specialization, responsiveness, and cost architecture. Market concentration data indicates that the top three players hold approximately 38 percent of total revenue, while the top five account for roughly 50 percent. This distribution suggests a market where leadership is meaningful but not absolute, leaving substantial room for differentiated positioning by mid-tier and regional suppliers. In practical terms, this means competitive advantage often derives from technology focus, application expertise, service networks, and the ability to meet localized compliance requirements rather than from scale alone.
Several companies illustrate the strategic diversity shaping the market. MTS Systems Corporation, based in Eden Prairie, Minnesota, manufactures servohydraulic and electrodynamic fatigue and fracture testing systems for high-cycle, low-cycle, and thermo-mechanical fatigue applications across aerospace, automotive, and civil engineering. Its breadth of application coverage positions it as a comprehensive solutions provider for sectors where multi-axis and multi-environment validation is essential. ADMET, Inc., headquartered in Norwood, Massachusetts, develops expert and modular fatigue testing systems supporting high-cycle and low-cycle testing compliant with ASTM and ISO standards, emphasizing modularity and standards alignment that appeal to laboratories and industrial users seeking configurable setups. ZwickRoell Group, located in Ulm, Germany, offers dynamic fatigue testing machines, vibrophores, and automated systems for materials including metals, composites, and elastomers, with a clear focus on advanced material categories that are increasingly central to electrification and lightweighting strategies.
Instron, also based in Norwood, Massachusetts, provides fully integrated dynamic and fatigue testing systems using servohydraulic, servo-electric, and linear motor technologies for cyclic loading evaluation. Its technology versatility supports a wide range of test configurations, making it a strong reference point for organizations that prioritize integrated hardware and software ecosystems. Shimadzu Corporation, based in Kyoto, Japan, manufactures hydraulic and electromagnetic fatigue testing machines and servopulser systems for durability assessment under cyclic and sudden loads, reflecting a long-standing capability in precision mechanical testing instrumentation. On the regional side, Testron Group in Guangzhou, China, sells servo-hydraulic anchorage and industrial fatigue testing machines with advanced sensors for cyclic stress and vibration measurement, while Laryee Technology Co., Ltd., in Weifang, Shandong, provides computer-controlled servo-hydraulic and electronic fatigue testing machines for dynamic and static universal testing applications. Shanghai Bairoe Test Instrument Co., Ltd., also in Shanghai, manufactures fatigue testing machines including PLW-series systems for tension, compression, and cyclic loading on metals and non-metals. Together, these companies highlight a market where global technology leadership and regional manufacturing agility coexist, and where procurement decisions increasingly weigh both specification compliance and total cost of ownership.
Recent Developments Shaping Market Dynamics
Current market momentum is being reinforced by a series of high-visibility industrial and standards-related events. In December 2025, ASTM International held its Sixth Symposium on Evaluation of Existing and New Sensor Technologies for Fatigue, Fracture, and Mechanical Testing, inviting papers for related events and signaling sustained attention to the sensor and measurement layer that underpins reliable fatigue data. Earlier that year, in November 2025, the 23rd International ASTM/ESIS Symposium on Fatigue and Fracture Mechanics convened with invited presentations, further reinforcing the role of standards bodies in defining best practices and testing rigor. These gatherings matter because they shape the technical expectations that procurement teams ultimately translate into equipment specifications.
On the product and application front, ZwickRoell Group launched a next-generation biaxial testing system in February 2026, featuring enhanced load capacity for composite materials used in electric vehicle batteries. This launch is strategically significant because it aligns equipment capability with one of the fastest-evolving application demands in the market: the validation of battery-adjacent composite structures. In the aerospace domain, General Atomics Aeronautical Systems, Inc. completed full-scale fatigue testing of the MQ-9B Remotely Piloted Aircraft in January 2026, equivalent to 40,000 operating hours. Such milestones demonstrate the high-stakes nature of fatigue validation in certification-critical programs and reinforce the need for robust, traceable testing infrastructure. Meanwhile, MTS Systems Corporation exhibited at the SAE Japan exhibition in Yokohama in May 2025, showcasing materials testing solutions and underscoring the importance of regional engagement in technology demonstration and customer development.
Hardness Testing Machine Market
Market Dynamics: Standards, Cost Pressures, and Procurement Direction
The fatigue machine market does not evolve in a vacuum. Several structural dynamics are shaping how demand forms and how suppliers compete. First, evolving regulatory and quality standards are structuring procurement toward certified, specification-compliant fatigue testing equipment. As organizations face greater scrutiny on material reliability and component lifecycle performance, the compliance credentials of testing systems have become a decisive factor in purchasing decisions. This trend benefits manufacturers that can clearly demonstrate alignment with recognized standards and provide the documentation, calibration support, and validation traceability that regulated industries require.
Second, input cost volatility and competitive pricing pressure are constraining margin expansion for fatigue testing machine manufacturers. In this environment, scale manufacturers with integrated supply chains hold a structural advantage, since they can better absorb cost fluctuations, manage component availability, and maintain consistent delivery performance. For smaller or more fragmented producers, the strategic response often lies in focused application expertise, faster customization cycles, or regional service advantages that justify price differentials through total value rather than unit cost alone.
Third, the technical standards landscape continues to deepen. Guidance such as NASA-HDBK-5026, finalized in August 2024, provides direction for fatigue and fracture control requirements in additive manufactured parts. As additive manufacturing moves from prototyping into production-critical roles, testing protocols for these components are becoming more formalized. This has direct implications for fatigue machine demand, since additively manufactured parts often require specialized evaluation approaches that differ from conventional wrought or machined components. Markets that embrace advanced manufacturing are therefore likely to drive demand for testing systems capable of handling new geometries, material behaviors, and validation regimes.
Strategic Implications for 2026 and Beyond
For organizations planning their next moves, the strategic implications of this market are clear. Growth is projected to be durable rather than speculative, with the market moving from $504.79 million in 2026 toward $731.77 million by 2032. This trajectory rewards players that can align product portfolios with the most resilient demand drivers, particularly where regulatory expectations, advanced material adoption, and high-cycle validation requirements intersect. At the same time, the concentration structure of the market suggests that while leading firms command meaningful share, there is still substantial competitive space for companies that can differentiate through technology specificity, application focus, or regional execution.
Procurement teams should treat compliance and traceability as strategic procurement criteria, not optional features. Manufacturers and service providers should assess where margin pressure is most intense and where integrated supply chain strength can protect profitability. Investors and entry strategists should pay close attention to the application segments and technology types that are expanding fastest, since the aggregate growth figure alone does not reveal where the most attractive risk-adjusted opportunities reside. In all cases, the ability to connect market data to operational choices will separate informed strategy from generic positioning.
Conclusion: Turn Market Intelligence into Strategic Advantage
The Fatigue Machine Market is entering a period in which disciplined analysis can translate directly into competitive advantage. The combination of steady macroeconomic growth, evolving testing requirements, standards-driven procurement, and cost-side pressure on manufacturers creates a landscape where the right strategic moves can compound over time. PW Consulting’s latest market research provides the depth, structure, and forward-looking context needed to make those moves with confidence. To access the complete analysis, including detailed segmentation insights, company-level evaluations, and full forecast data, readers are encouraged to explore the full report through the source page. In a market defined by durability, precision, and long-cycle decision-making, comprehensive intelligence is the foundation of durable strategy.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


