



PW Consulting: Hemodialysis Concentrates Market to Reach $3.56B by 2032, 6.2% CAGR

Strategic Intelligence for the Hemodialysis Concentrates Market: A 2026 Decision-Maker's Guide
The global landscape for hemodialysis concentrates is undergoing a decisive transformation. As chronic kidney disease prevalence rises and dialysis delivery models evolve, stakeholders across the value chain require more than surface-level market data. They need actionable intelligence grounded in rigorous historical analysis and forward-looking forecasting. PW Consulting's latest Hemodialysis Concentrates Market research report delivers precisely that: a comprehensive, data-driven roadmap designed to inform strategic planning, capital allocation, and competitive positioning through 2032 and beyond. Built on a foundation spanning 2020 to 2025 historical performance and projecting through the 2026 to 2032 forecast horizon, this study equips executives, investors, and operational leaders with the insights necessary to navigate an increasingly complex and regulated marketplace.
The Macro Trajectory: Market Sizing and Growth Dynamics
Understanding where the market stands today and where it is headed requires a clear view of its cumulative growth story. Between 2020 and 2025, the global hemodialysis concentrates market demonstrated consistent expansion, with revenue climbing from approximately 1,800 million USD to an estimated 2,350 million USD by the base year of 2025. This trajectory reflects the compounding effect of rising dialysis patient volumes, evolving clinical preferences, and sustained investment in dialysis infrastructure across multiple continents. Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.2 percent, signaling a market that will continue to expand at a meaningful pace rather than plateauing. By the close of the forecast window in 2032, total market revenue is projected to approach 3,560 million USD.
For enterprise decision-makers, these figures are not merely academic benchmarks. They represent the scale of opportunity and the urgency of strategic preparation. A projected 6.2 percent CAGR over a seven-year horizon implies that companies entering or expanding within this space must align their capacity planning, supply chain resilience, and commercial strategies with a market that will be substantially larger than the one operating today. The report contextualizes this growth within historical volatility, regional infrastructure development cycles, and shifting procurement patterns, ensuring that leadership teams can distinguish between temporary fluctuations and structural trends.
Hemodialysis Concentrates Market
Dissecting the Segmentation Architecture
Effective strategy in the hemodialysis concentrates sector demands a granular understanding of how demand is distributed across product types, end-use applications, and geographic territories. Our analysis examines the market through multiple segmentation lenses, revealing where value concentrates, where growth is most pronounced, and where competitive pressure is intensifying.
Product Type Dynamics
The market is anchored by two principal concentrate categories: acid concentrates and bicarbonate concentrates. Both play indispensable roles in dialysate preparation, yet they serve distinct clinical and operational functions and are subject to different supply chain considerations. The report evaluates the relative market contribution of each type, tracing how formulation preferences, manufacturing complexity, and regulatory scrutiny shape demand patterns. Acid concentrates, which form the foundational component of dialysate chemistry, carry their own set of handling requirements and cost drivers. Bicarbonate concentrates, meanwhile, have seen evolving adoption as clinic and home-care operators seek optimized buffering solutions that align with modern dialysis machine specifications. By mapping historical revenue distribution and projecting forward shifts, the study highlights where manufacturers should prioritize formulation innovation, production scalability, and customer education.
Application and Care Setting Shifts
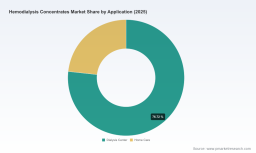
Beyond product chemistry, the channel through which concentrates reach end users is a critical strategic variable. Dialysis centers remain the dominant consumption environment, benefiting from centralized procurement, standardized dosing protocols, and high-volume utilization. At the same time, home care represents a structurally important and increasingly visible segment. As healthcare systems worldwide explore decentralized treatment models and patient preference shifts toward greater independence, home dialysis programs are gaining policy support and operational investment. The report disentangles these application-level dynamics, examining how procurement cycles, reimbursement environments, and equipment compatibility influence concentrate selection in each setting. This dual-lens approach enables suppliers to tailor their commercial outreach, packaging formats, and technical support resources to the distinct needs of institutional and residential users.
Regional Commercial Landscapes
Geographic diversification is a defining feature of the hemodialysis concentrates market. Demand patterns are shaped by local disease epidemiology, healthcare financing models, dialysis center density, and the maturity of domestic manufacturing capabilities. The report evaluates market conditions across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than treating these territories as monolithic blocks, the analysis considers subregional infrastructure gaps, import dependency levels, and the pace of local production ramp-ups. For multinational suppliers, this regional granularity is essential for prioritizing market entry sequencing, localizing supply chains, and calibrating pricing strategies to reflect purchasing power and reimbursement realities in each territory.
Competitive Landscape: Who Shapes the Market and How
The hemodialysis concentrates sector is characterized by a concentrated competitive structure, with a handful of established players accounting for a substantial share of total industry revenue. The report profiles the leading manufacturers whose product portfolios, manufacturing footprints, and commercial strategies define the current market equilibrium. Understanding these companies is not an academic exercise; it is a prerequisite for assessing partnership opportunities, anticipating competitive responses, and identifying white-space opportunities that incumbents may overlook.
Leading Manufacturers and Strategic Positioning
Fresenius Medical Care, headquartered in Bad Homburg, Germany, stands as a major force in the sector, manufacturing Citrasate and a broad range of liquid and dry acid and bicarbonate hemodialysis concentrates for both clinic and home dialysis applications. Its scale and integration with broader dialysis service networks give it a distinctive competitive posture. B. Braun Melsungen, based in Melsungen, Germany, has built its position around the Dialog-plus platform and premixed dialysis concentrates that integrate seamlessly into its full dialysis systems portfolio, emphasizing interoperability and clinician workflow optimization. Nipro Corporation, operating from Osaka, Japan, supplies MedicaPure liquid acid and MedicaLyte bicarbonate concentrates designed for compatibility with hemodialysis machines, reflecting a focus on precision formulation and equipment alignment.
In the United States, Rockwell Medical, headquartered in Wixom, Michigan, has carved out a recognized presence through its CitraPure, Dri-Sate, RenalPure, and SteriLyte product lines, offering both liquid and dry acid and bicarbonate concentrates. Renacon Pharma Limited, based in Karachi, Pakistan, has been manufacturing RENACIT citrate hemodialysis concentrates and related formulations since 1996, representing a long-standing commitment to specialized concentrate production. In Turkey, Farmasol, located in Kayseri, produces acid and bicarbonate concentrates as part of the broader Pollet Medical Group dialysis portfolio. Meanwhile, Pollet Medical Group, operating from Belgium, functions both as a producer of concentrate production systems and as a supplier of acid concentrate solutions for hemodialysis, positioning itself at the intersection of equipment and consumable supply.
Strategic Implications of Competitive Concentration
The market's concentration profile means that strategic moves by top-tier players can ripple across pricing, supply availability, and clinical adoption patterns. The report examines how these manufacturers compete on dimensions such as formulation performance, single-use convenience, digital integration, and geographic reach. By mapping the competitive field, the study helps emerging entrants and mid-tier suppliers identify where they can differentiate effectively, whether through niche formulations, regional partnerships, cost-efficient manufacturing, or service-oriented value propositions that larger incumbents may not fully address.
Recent Industry Developments: Accelerating Change
The competitive and operational landscape is not static. Recent corporate actions and product innovations underscore the speed at which the hemodialysis concentrates market is evolving. In January 2025, Farmasol became part of Pollet Medical Group through an acquisition that expanded in-house production of hemodialysis acid concentrates, illustrating a broader trend toward vertical integration and consolidated manufacturing capabilities. Just weeks later, in February 2025, Rockwell Medical added single-use bicarbonate cartridges to its hemodialysis concentrates portfolio, responding to growing demand for simplified handling, reduced preparation variability, and enhanced infection-control workflows. In July 2025, Fresenius Medical Care launched the kinexus unified digital platform, a move designed to support the integration of hemodialysis concentrates into broader connected care ecosystems, signaling the increasing convergence of consumable supply and digital clinical management. By October 2025, Rockwell Medical further reinforced its commercial visibility by exhibiting its concentrates portfolio at ASN Kidney Week 2025, underscoring the importance of professional conferences as platforms for product education and partnership development.
These developments are not isolated events. They reflect a market in which manufacturers are actively reshaping their portfolios, exploring integration opportunities, and investing in user-centric formats. For buyers and investors, tracking such moves is essential for anticipating supply shifts, evaluating vendor reliability, and understanding where innovation is likely to create new purchasing criteria.
Regulatory, Reimbursement, and Cost Pressures: The Operational Reality
No strategic assessment of the hemodialysis concentrates market is complete without addressing the regulatory and economic forces that shape day-to-day operations. In 2025, the sector faced heightened regulatory attention, including a Class 2 device recall issued by the FDA on May 28, 2025, concerning premixed dialysate for hemodialysis due to potential perimeter seal issues. Later in the year, on December 23, 2025, the FDA issued another Class 2 device recall related to Diasol liquid concentrate, focusing on the safety and efficacy of dialysis acid concentrates. These actions followed earlier quality monitoring measures, including the termination of a Class 2 device recall for dialysate concentrate for hemodialysis on July 11, 2024. Collectively, these regulatory events highlight the critical importance of quality assurance, packaging integrity, and documentation rigor throughout the concentrate supply chain.
Hemodialyzer Market
Reimbursement dynamics add another layer of complexity. Reimbursement for hemodialysis concentrates varies by jurisdiction, with standard CPT codes covering dialysis fluid preparation in major markets. While this framework provides a baseline for cost recovery, differences in coding practices, payer policies, and regional healthcare financing mean that margin structures and purchasing behaviors can diverge significantly across territories. The report contextualizes these reimbursement patterns, helping commercial teams forecast uptake sensitivity to policy changes and design pricing strategies that align with local payment environments.
On the cost side, medical-grade material inputs—including purified water, electrolytes, and acids—are subject to fluctuations driven by supply chain infrastructure and manufacturing logistics. The study examines how input cost variability interacts with production scale, inventory management, and contractual arrangements, providing practical guidance for operators seeking to stabilize margins without compromising product quality or service reliability.
What the Report Delivers: Operational Intelligence for Decision-Makers
PW Consulting's Hemodialysis Concentrates Market report is built to translate market complexity into executable strategy. Its content is organized to support a range of decision-making needs, from long-range capacity planning to near-term commercial execution. The report includes:
- Historical market sizing and growth analysis spanning 2020 through 2025, establishing a reliable baseline against which future performance can be measured.
- A seven-year forecast for 2026 through 2032, projecting revenue evolution at a market level and across key segmentation dimensions, with methodology transparent enough to support internal validation and sensitivity testing.
- Detailed segmentation analysis covering product type, application setting, and regional demand patterns, enabling targeted go-to-market planning and resource allocation.
- Comprehensive company profiles of leading manufacturers, including organizational background, product offerings, and strategic positioning, alongside an assessment of competitive concentration and market share dynamics.
- A curated review of recent industry developments, including acquisitions, product launches, and conference visibility, to help stakeholders track the pace and direction of competitive change.
- An in-depth examination of regulatory events, reimbursement structures, and material cost drivers, providing the operational context needed to interpret market data in practical terms.
- Strategic recommendations and scenario considerations designed to help leaders evaluate entry timing, partnership options, capacity investments, and portfolio emphasis in light of evolving market conditions.
Each section is crafted to avoid generic commentary and instead deliver specific, decision-oriented insight. The report connects quantitative trends with qualitative industry dynamics, ensuring that readers can interpret numbers within the broader operational and regulatory environment in which they will be applied.
Why This Research Matters for 2026 Strategy
As organizations plan their 2026 agendas, the hemodialysis concentrates market presents both opportunity and complexity. Demand is projected to continue its upward trajectory, competitive intensity is being reshaped by consolidation and product innovation, and regulatory scrutiny is reinforcing the importance of quality and supply chain transparency. In this environment, decisions made without comprehensive market intelligence carry heightened risk. Investment timing, geographic prioritization, product portfolio emphasis, and vendor selection all benefit from a clear, evidence-based view of where the market is headed and why.
This report is designed to serve as that reference point. It does not merely describe market size; it explains the forces behind size, the segmentation patterns that determine where growth will be realized, and the competitive and regulatory developments that will shape execution. For executives, procurement leaders, investors, and strategy teams, the study offers a structured basis for evaluating options, challenging assumptions, and aligning internal planning with external realities.
Access the Full Intelligence
While this overview highlights the scope and strategic relevance of the research, the complete report contains the detailed segmentation data, competitive assessments, regional breakdowns, and forward-looking analysis that decision-makers need to act with confidence. For a thorough examination of market trajectories, company positioning, and the operational dynamics influencing hemodialysis concentrates supply and demand, we invite you to explore the full study. Accessing the complete report will provide the depth and specificity required to translate high-level trends into precise, actionable strategy for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


