



PW Consulting: Medical Pressure Transducers Market Hits $360M in 2025, Forecast 6.5% CAGR to $535M by 2032

Strategic Imperatives in the Medical Pressure Transducers Market: Navigating Growth and Complexity through 2032
Executive Overview
The global medical pressure transducers market stands at a critical inflection point where clinical necessity, technological evolution, and regulatory scrutiny converge to shape procurement strategies and product development roadmaps. For healthcare manufacturers, distributors, and hospital systems alike, understanding the trajectory of this sector is no longer optional. It is a fundamental component of risk management and revenue optimization. Our latest comprehensive study on the Medical Pressure Transducers Market offers a granular look into the forces driving value creation and erosion across the forecast horizon.
As we move into 2026, decision-makers are faced with a landscape defined by steady expansion but increasingly complex operational challenges. The market has demonstrated resilience over the past five years, recovering from pandemic-related disruptions and stabilizing into a growth pattern driven by aging demographics, the rising prevalence of cardiovascular conditions, and the continued adoption of minimally invasive monitoring technologies. However, raw growth figures tell only half the story. The real strategic value lies in understanding where margin pressure is building, how regulatory shifts are altering time-to-market, and which geographic corridors offer the most sustainable competitive advantage.
This article serves as a strategic preview of our full market intelligence report. It highlights the macroeconomic trends, competitive dynamics, and regulatory undercurrents that define the sector today. We will outline the operational depth contained within the study and explain why access to the complete dataset is essential for formulating robust strategies in 2026 and beyond.
Market Trajectory and Macroeconomic Context
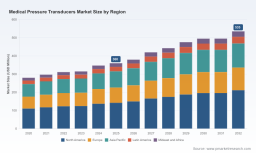
The financial architecture of the medical pressure transducers market reveals a consistent upward trajectory, underpinned by a compound annual growth rate that reflects both recovering demand and structural adoption of advanced monitoring solutions. Between 2020 and 2025, the market expanded from approximately 280 million USD to 360 million USD, signaling a recovery and acceleration phase that has set the stage for the forecast period.
Looking ahead to 2032, the revenue landscape is projected to reach 535 million USD. This growth path is not linear. The forecast period from 2026 to 2032 indicates varying velocities of expansion, with early forecast years showing measured acceleration before gaining momentum in the latter half of the decade. The overall CAGR of 6.5 percent suggests a mature but steadily expanding market, where volume growth is complemented by value-added features and premium product positioning.
It is crucial for stakeholders to recognize that these aggregate numbers mask significant variation across product types, clinical applications, and regional procurement environments. The interplay between established markets with high penetration rates and emerging markets with growing healthcare infrastructure creates a dual-speed environment. Companies that fail to differentiate their go-to-market strategies across these zones risk leaving revenue on the table or overinvesting in low-yield segments. Our full report deconstructs these layers to reveal the specific growth pockets and saturation risks that aggregate data obscures.
Segmentation Dynamics and Demand Drivers
Demand for medical pressure transducers is fundamentally tied to the criticality of hemodynamic monitoring and fluid management in acute care settings. The market is structured around distinct product configurations that serve different clinical workflows, ranging from single-channel solutions for straightforward monitoring to multi-channel systems designed for complex patient management. Each configuration carries different cost structures, manufacturing complexity, and clinical value propositions.
Applications span the spectrum of critical care and perioperative monitoring. Blood pressure monitoring remains a cornerstone application, driven by the ubiquity of invasive arterial pressure measurement in intensive care units and operating rooms. Respiration systems represent another significant demand center, particularly as ventilator management and respiratory support continue to evolve in complexity. Infusion pumps and related fluid delivery systems also rely heavily on accurate pressure sensing to ensure dosing accuracy and patient safety. Beyond these primary uses, specialized applications in surgical and interventional settings contribute to the broader demand picture.
Medical Pressure Transducers Market
From a regional perspective, the market exhibits a diversified footprint. North America continues to hold a substantial share, reflecting high healthcare spending, established critical care infrastructure, and a strong base of domestic manufacturers. Europe maintains a significant presence, though it faces unique regulatory and reimbursement dynamics that influence product adoption cycles. The Asia Pacific region represents a rapidly evolving landscape, where expanding hospital networks, growing medical tourism, and localized manufacturing initiatives are reshaping competitive dynamics. Latin America and the Middle East and Africa, while smaller in absolute terms, present growth opportunities tied to healthcare modernization efforts and increasing access to advanced monitoring technologies.
The strategic implication for 2026 is clear: a one-size-fits-all approach to product launches, pricing, and distribution is increasingly inefficient. Stakeholders must align their portfolios with regional clinical preferences, procurement cycles, and regulatory expectations. The detailed segmentation analysis in our full report provides the specific revenue allocations and growth rates that allow companies to prioritize investments with precision.
Competitive Landscape and Strategic Positioning
The competitive environment in the medical pressure transducers market is characterized by a mix of established multinational players and specialized manufacturers, each carving out niches through product differentiation, clinical evidence, and supply chain reliability. Market concentration metrics indicate that while the top players command meaningful share, the market remains sufficiently fragmented to allow for targeted strategic moves. The combined share of the top three and top five firms underlines the presence of scale advantages, yet also suggests room for agile competitors to capture value in specific applications or regions.
Several key companies define the current competitive benchmark. Edwards Lifesciences Corporation, based in Irvine, California, maintains a prominent position with its TruWave disposable pressure transducers, which are widely recognized for invasive hemodynamic monitoring applications. Their product lineage reflects a focus on integration with broader hemodynamic monitoring ecosystems, appealing to institutions that prioritize workflow compatibility and clinical standardization.
Smiths Medical, headquartered in Minneapolis, Minnesota, offers the TranStar disposable pressure transducer systems, which are designed for hemodynamic monitoring and emphasize reliability in high-acuity settings. Their portfolio underscores the importance of disposable systems in infection control and operational efficiency, a theme that resonates across modern critical care procurement criteria.
ICU Medical, Inc., located in San Clemente, California, provides the Transpac integrated and disposable pressure transducer systems tailored for critical care. Their offering highlights the convergence of sensor accuracy, ease of setup, and compatibility with existing monitoring platforms, factors that are increasingly weighted in hospital buying decisions.
Merit Medical Systems, Inc., based in South Jordan, Utah, contributes the Meritrans pressure transducers and Meritrans DTXPlus disposable systems, expanding the range of options available for procedural and critical care monitoring. Their presence illustrates how diversified medical device companies leverage pressure transducer portfolios to support broader interventional and diagnostic workflows.
Argon Medical Devices, Inc., operating from Plano, Texas, focuses on pressure monitoring lines and transducer kits for interventional procedures. Their specialization points to the growing demand for Procedural-specific monitoring solutions that address the unique requirements of catheterization labs, interventional radiology, and hybrid operating environments.
Competitive dynamics are further shaped by recent developments that signal shifts in accessibility and safety scrutiny. In September 2025, Shanghai Draeger Medical Instrument Co., Ltd. received FDA 510(k) clearance for an IBP transducer adapter cable compatible with multiple major brands, including Argon/BD/Ohmeda, Edwards, and Smiths/TranStar. This clearance highlights a trend toward interoperability and cross-compatibility, which can reduce dependency on single-vendor ecosystems and increase flexibility for hospital procurement teams. At the same time, Edwards Lifesciences' December 2025 adverse event report related to the TruWave disposable pressure transducer, documented in the FDA MAUDE database, serves as a reminder that post-market surveillance and device reliability remain critical differentiators. Incidents of this nature can influence purchasing confidence, quality assurance protocols, and risk management frameworks across the industry.
Regulatory and Operational Pressures Reshaping the Value Chain
Regulatory frameworks are exerting an increasingly pronounced influence on market entry timelines, cost structures, and product lifecycle management. The certification landscape has become more demanding, particularly within the European context. Analysts' insights indicate that the average certification timeline for the EU Medical Device Regulation 2017/745 has expanded from nine months to 18 months between 2021 and 2025. This elongation is accompanied by a cost increase ranging from 35 to 50 percent, placing greater strain on product development budgets and time-to-revenue expectations. For companies planning launches or refreshes in the European market, these shifts necessitate earlier regulatory engagement and more robust documentation strategies.
In parallel, FDA Class II clearance continues to govern the global blood pressure transducers market, ensuring biocompatibility and calibration accuracy. Compliance with these standards is a baseline requirement, but the competitive edge often lies in how manufacturers demonstrate consistency, traceable calibration practices, and post-market performance data. ISO 80601-2-34 governs transducer performance, yet actual calibration practices differ by hospital, manufacturer, and even individual clinician. This variability introduces both a quality assurance challenge and an opportunity for companies that can standardize calibration workflows, provide clear guidance, and reduce ambiguity in clinical settings.
On the supply side, the raw material procurement landscape adds another layer of complexity. The manufacturing of pressure transducers involves the pouring and processing of materials such as silicon, stainless steel, specialty alloys, and plastics sourced from various suppliers. Fluctuations in material availability, pricing, and supplier reliability can affect production continuity and cost margins. Companies that build resilient supplier networks, maintain strategic buffer stocks, and qualify alternative sources are better positioned to navigate supply chain disruptions without compromising delivery commitments.
These operational and regulatory factors combine to create a market environment where success is not solely determined by product performance but also by organizational agility, compliance readiness, and supply chain robustness. The detailed analysis in our report maps these dynamics against market segments and regional profiles, enabling stakeholders to anticipate bottlenecks and align resources accordingly.
What the Full Report Delivers for 2026 Decision-Making
The Medical Pressure Transducers Market study is designed to move beyond surface-level statistics and provide actionable intelligence for strategy formulation, portfolio planning, and competitive positioning. The report integrates demand-side analysis with supply-side dynamics, offering a 360-degree view of the market that supports both short-term tactical adjustments and long-term strategic investments.
Key components of the study include a comprehensive segmentation breakdown that isolates revenue contributions, growth rates, and trajectory patterns across product types, applications, and regions. Rather than presenting static snapshots, the analysis tracks the evolution of each segment over the historical period and projects forward through 2032, highlighting inflection points, saturation risks, and emerging demand pockets. This allows readers to identify which segments offer the most attractive risk-adjusted returns and which require defensive strategies or withdrawal considerations.
The competitive profiling section goes beyond corporate descriptions to assess market positioning, product differentiation, and strategic moves that indicate future intent. By mapping recent regulatory clearances, adverse event disclosures, and compatibility expansions, the report provides early signals of shifting competitive advantages and potential vulnerabilities. This level of detail helps manufacturers refine their value propositions, anticipate competitor responses, and identify partnership or acquisition opportunities that align with market needs.
Additionally, the study embeds regulatory and operational context into the market analysis, ensuring that growth projections are interpreted through the lens of real-world constraints. Certification timelines, cost escalations, calibration variability, and raw material procurement challenges are not treated as peripheral issues; they are integrated into the strategic narrative, showing how they influence product economics, launch sequencing, and regional prioritization. This approach enables readers to stress-test their plans against plausible scenarios and make more informed resource allocation decisions.
Ultimately, the report is structured to answer the questions that matter most to executives, product leaders, and commercial teams: Where is sustainable growth concentrated? Which competitive moves are most likely to disrupt current share distributions? How do regulatory and supply chain dynamics alter the profitability of different segments? And what specific actions should be prioritized in 2026 to capture value while mitigating exposure?
Conclusion: The Case for Comprehensive Market Intelligence
The medical pressure transducers market is entering a phase where growth is achievable but increasingly contingent on strategic precision. Aggregate expansion masks divergent segment trajectories, regional nuances, and shifting competitive threats that can materially affect outcomes if left unaddressed. Companies that rely on high-level summaries or outdated assumptions risk misallocating capital, misreading competitor intent, and underestimating the operational hurdles that shape market access.
Our full Medical Pressure Transducers Market report provides the depth, granularity, and forward-looking context required to navigate this environment with confidence. By revealing the specific revenue distributions, segment growth patterns, and competitive benchmarks that underpin the market's trajectory, the study equips stakeholders with the intelligence needed to optimize product portfolios, refine geographic strategies, and strengthen operational resilience.
Medical Pressure Sensors Market
For organizations preparing for 2026 and the forecast decade ahead, the difference between reactive positioning and proactive leadership lies in the quality of the information guiding critical decisions. Access to the complete market analysis ensures that strategy is built on evidence rather than inference, and that growth opportunities are pursued with clarity, discipline, and a realistic understanding of the landscape. We invite you to explore the full report to unlock the detailed insights that will inform your next strategic moves.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


