



PW Consulting: AIN Market Hits $166.02M in 2025, Projected 5.5% CAGR Through 2032

The Thermal Imperative: Why Aluminum Nitride Market Intelligence Defines Strategic Advantage in 2026
At PW Consulting, we recognize that in advanced thermal management, material performance is no longer just a technical specification, it is a strategic differentiator. As power densities climb, semiconductor packages shrink, and electrification accelerates across mobility and infrastructure, Aluminum Nitride has emerged as the substrate material of choice for engineers who cannot compromise on thermal conductivity, electrical insulation, or long-term reliability. Our latest Aluminum Nitride Market market research is designed to convert this complex, fast-moving landscape into a clear, decision-ready intelligence asset for executives, product leaders, and supply chain strategists operating in 2026 and beyond.
This report is not a generic market scan. It is a structured strategic navigation tool built to help organizations anticipate demand shifts, assess competitive positioning, evaluate supplier risk, and align portfolio investments with the trajectory of a market that is evolving under both technical and geopolitical pressure. Below, we outline the framing, scope, and strategic logic behind this analysis, while preserving the detailed segmentation and quantified forecasts for the full study.
The Strategic Context for 2026 Decision-Makers
The timing of this research is deliberate. By 2026, the Aluminum Nitride market operates at the intersection of rising end-use demand and increasing supply-side complexity. From an aggregate perspective, the global market reached an estimated USD 166.02 million in 2025, building on a multi-year expansion that traces back to a 2020 baseline of USD 131.42 million. This trajectory reflects sustained, measurable growth rather than a transient cycle. Looking forward, our forecast period for this study spans 2026 through 2032, with the CAGR projected at 5.5%.
Why the Numbers Matter, Even When They Do Not Tell the Whole Story
Executive teams often ask a simple question: is this material category gaining structural momentum, or is growth being inflated by a narrow application pocket? The macro trend answers that question with clarity. The market has moved from USD 140.56 million in 2021 to USD 145.47 million in 2022, then USD 149.79 million in 2023, followed by a more pronounced step-up to USD 164.44 million in 2024. That sequence matters because it shows resilience across different demand environments and suggests that adoption is broadening rather than concentrating only in a single hype-driven segment.
Our forecast model continues this arc, projecting the market at approximately USD 170.03 million in 2026, advancing to USD 184.71 million in 2027, USD 200.95 million in 2028, USD 206.42 million in 2029, USD 213.70 million in 2030, USD 225.94 million in 2031, and USD 239.11 million by 2032. These figures form the analytical backbone of the study, but they are only the starting point. The strategic value lies in understanding the forces shaping each phase of that path and in identifying where commercial opportunities will be won or lost.
Aluminum Nitride (AIN) Market
Where Real Decision Insight Comes From
For a market defined by high-performance ceramics, substrate engineering, and application-specific thermal requirements, broad market sizing alone is insufficient. PW Consulting built this report to help leaders answer the questions that actually drive capital allocation and product strategy:
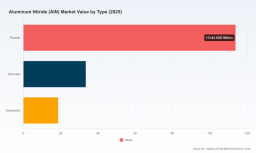
- Which material forms are gaining traction for different engineering constraints, and how should manufacturers think about capacity mixed across powder, granules, and substrates?
- Where is demand intensifying most strongly across power electronics, microelectronics, and adjacent application pools, and what does that mean for downstream sourcing priorities?
- Which geographic markets are expanding on the strength of local end-use demand, industrial ecosystems, and supplier proximity, and where do logistics, regulation, and export control dynamics reshape the playing field?
- How concentrated is the competitive base, and what does supplier concentration mean for procurement resilience, technology access, and negotiation leverage?
The report addresses these issues through an integrated analytical framework that connects market structure, application requirements, regional dynamics, and company-level positioning. Our intent is to give readers a usable map of the market, one that supports scenario planning, supplier evaluation, and go-to-market decisions without forcing them to infer relationships from disconnected datasets.
Aluminum Nitride Ceramic Heaters Market
Market Structure and Concentration: The Hidden Risk Layer
One of the most important themes in this research is the degree of market concentration. A market can grow steadily on paper yet still expose buyers and investors to concentration risk if a small group of suppliers controls a disproportionate share of high-quality output. In this study, we examine a landscape in which the top three companies account for an estimated 65.2% of market revenue, while the top five companies reach approximately 71.5%.
From a strategic standpoint, this concentration changes the nature of the buying and partnering conversation. It affects lead-time reliability, qualification cycles, technical support depth, and the negotiation dynamics around proprietary formulations or substrate grades. It also raises the stakes for organizations that depend on differentiated thermal performance and cannot afford disruption in supply consistency. Rather than treating concentration as a static statistic, the report uses it as a lens for assessing supplier viability, technology access, and the practical implications of building a sourcing strategy in a market where a limited number of players shape a large portion of available supply.
Competitive Landscape: Capability, Focus, and Timing
The Aluminum Nitride competitive set is not a homogeneous group. It spans established ceramic manufacturers, substrates specialists, and companies pushing single-crystal material development into commercial applications. The study profiles several core participants whose activities help define the market's direction, including CoorsTek, CeramTec GmbH, KYOCERA Corporation, Crystal IS, HexaTech Inc., Tokuyama Corporation, Precision Ceramics, and Accumet Materials Co.
Each of these companies brings a distinct angle to the market. CoorsTek develops custom-engineered aluminum nitride ceramics and substrates tailored for thermal management, semiconductor, and electronics applications. CeramTec GmbH offers Alunit aluminum nitride substrates and heat sinks designed for high thermal conductivity and electrical insulation, with emphasis on power electronics and microelectronics. KYOCERA Corporation manufactures aluminum nitride substrates and packages with a strong focus on design flexibility and thermal and electrical properties for semiconductor and electronic components. Tokuyama Corporation supplies high-purity aluminum nitride powder and granules used in sintered bodies and heat-dissipation materials for semiconductors and electronics. Precision Ceramics machines aluminum nitride components and prototypes across multiple grades for thermal management and electrical insulation uses. Accumet Materials Co. supplies aluminum nitride powders and materials for technical ceramic applications.
Beyond the established substrate and powder supply base, the research also tracks the growing relevance of single-crystal development. Crystal IS produces bulk single-crystal aluminum nitride substrates, including 100 mm diameter options, for UVC LEDs, RF, and power semiconductor applications. HexaTech Inc. develops and produces single-crystal aluminum nitride substrates for power and RF device technologies. These capabilities matter because they point toward higher-performance substrate classes that can reshape qualification windows, device performance ceilings, and competitive differentiation over time.
Recent Moves That Signal Strategic Direction
Market intelligence is most useful when it connects company actions to forward-looking implications. In this study, we incorporate a set of notable recent developments that illustrate how suppliers are scaling, refining, and repositioning their offerings. In February 2026, HexaTech Inc. launched a 3-inch, or 76.2 mm, diameter single-crystal aluminum nitride substrate product for commercial-scale power and RF device technologies. That announcement signaled a move from development-scale output toward broader commercialization. In July 2025, HexaTech also introduced an optimized nitrogen-face aluminum nitride substrate for power and RF device development, reinforcing a pattern of iterative performance optimization rather than one-time product launches.
In April 2026, Crystal IS announced an expanded focus on AlN substrates and a new pilot production line for 100 mm aluminum nitride substrates, pointing to increased emphasis on scalable single-crystal supply for high-value device applications. In the same month, KYOCERA Corporation released a comprehensive guide to aluminum nitride packages and substrates highlighting properties and applications, an action that reflects both technical positioning and customer-facing education in a market where material selection is closely tied to engineering confidence.
These developments are not isolated news items. They are indicators of where capability investment is going, which form factors are being prioritized, and how suppliers are preparing for higher-performance and higher-volume device requirements. The report uses this evidence to help readers assess which players are building near-term commercial momentum and which are betting on longer-horizon differentiation.
Demand Dynamics and Application Realities
The core demand story for Aluminum Nitride is tied to thermal management in environments where conventional materials struggle to keep pace with heat flux, miniaturization, and reliability expectations. In the study, we analyze how demand distributes across application areas such as power electronics and microelectronics, along with a smaller pool of other uses. The report examines how these application categories create different purchasing behavior, qualification requirements, and performance thresholds.
Power electronics and microelectronics, in particular, place distinct demands on substrate quality, surface characteristics, thermal performance, and consistency. The research explores the strategic consequences of that split: how application requirements shape preferred material forms, influence supplier selection, and affect the balance between standardized volume supply and application-specific engineering support. By linking application context to supply logic, the study helps readers understand why demand growth is never merely a function of end-market size. It is also a function of technical fit, development cycles, and the maturity of manufacturing and qualification pathways.
Regional Dynamics and the Supply-Regulation Intersection
In a market of this nature, geography matters not only because demand is distributed unevenly, but also because supply chains and regulatory environments differ sharply by region. The report assesses regional market structures and the implications of localized demand, manufacturing presence, and industrial ecosystem development. Rather than treating regional splits as isolated revenue buckets, the analysis connects them to practical questions of sourcing proximity, logistics exposure, and the strategic value of regional supplier relationships.
At the same time, the study integrates an increasingly important layer of market dynamics: regulatory and export-control pressure. Aluminum Nitride substrates are subject to licensing considerations in certain contexts, particularly where end uses intersect with military applications or sanctioned-entity exposure. The research highlights that suppliers and buyers alike must navigate US export administration requirements, with AlN substrates classified under the Export Administration Regulations as controlled items requiring licensing for certain military and sanctioned applications. Relatedly, Japanese and US export licensing requirements for AlN substrates have become material considerations for international trade, especially for sensitive end uses.
The regulatory environment is further complicated by broader supply-chain pressures. High-purity aluminum and nitrogen raw materials face volatility linked to supply-chain disruptions, and US-China tensions along with export restrictions on critical raw materials such as high-purity aluminum and nitrogen compounds influence how supply chains are configured. The market is also affected by the limited global supply of high-purity raw materials, which can constrain share capture and shape competitive outcomes. These are not background issues; they are operational realities that affect cost structure, lead times, supplier selection, and long-term market access.
Why This Research Is Built for 2026 Strategy
PW Consulting developed this research to support decisions that have to hold up under uncertainty. In 2026, organizations are not simply asking where the market is going. They are asking how to position for growth while managing concentration risk, raw-material volatility, regulatory exposure, and the increasing performance demands of end applications. The report is structured to help with exactly those questions.
It provides a cohesive view of market scale and trajectory, segmentation logic across type and application, regional context, competitive concentration, company-level positioning, and the operational dynamics that shape procurement and product strategy. Equally important, it is designed to be actionable. Readers can use it to pressure-test assumptions about demand durability, supplier reliability, and the commercial meaning of technical advances such as larger-diameter single-crystal substrates or optimized substrate faces.
What the Full Study Delivers
In the complete report, these themes are developed with the depth and specificity required for executive and operational use. The study combines market sizing and forecast analysis with segmentation evaluation, competitive assessment, and a structured review of the forces reshaping supply and demand. It is built to serve multiple internal audiences at once: strategy teams evaluating market entry or expansion, procurement leaders assessing supplier risk and concentration exposure, product teams aligning roadmaps with material availability and performance trends, and investors or advisors seeking a rigorous view of market structure.
The full research also preserves the detailed quantitative architecture behind the analysis. That includes historical performance from 2020 through 2025, forward projections across the 2026 to 2032 forecast window, and the underlying segmentation and company-level context needed to interpret those figures with confidence. The goal is not to overwhelm with data, but to provide a disciplined evidentiary foundation for decisions that depend on more than directional intuition.
Conclusion: A Market Where Intelligence Determines Execution
Aluminum Nitride is no longer a niche thermal material in search of a market. It is a strategically important substrate and material category whose growth is being shaped by device performance requirements, supplier concentration, raw-material constraints, and regulatory complexity. In that environment, strategic advantage belongs to organizations that understand not just the headline numbers, but the structure beneath them.
PW Consulting's Aluminum Nitride Market study is designed to give decision-makers that structural understanding. It translates a multi-year growth trajectory and a 5.5% forecast CAGR into a practical intelligence framework for 2026 and the years ahead. For leaders who need to move from general awareness to specific, defensible action, the full report provides the segmentation, company-level detail, competitive context, and market-dynamic analysis required to act with confidence.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride (AIN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


