



PW Consulting: Combine Harvesters Market to Reach $180 Million by 2032 Amid 4.5% CAGR

Navigating the Combine Harvesters Market: Strategic Intelligence for 2026 and Beyond
The global agricultural machinery sector stands at a critical inflection point, driven by the convergence of labor shortages, regulatory incentives, and rapid technological adoption. As we move through 2026, understanding the trajectory of the combine harvesters market is essential for stakeholders ranging from equipment manufacturers to large-scale farming enterprises. PW Consulting's latest market research study offers a comprehensive roadmap of this evolving landscape, providing the granular intelligence necessary to navigate volatility and capitalize on emerging opportunities.
This article serves as an executive overview of the study's strategic value. It highlights the macro-economic trajectory, the competitive forces reshaping the industry, and the operational dynamics that will define profitability over the next seven years. By synthesizing historical performance with forward-looking analysis, this research equips decision-makers with the context needed to align capital allocation, product development, and market entry strategies with realistic growth expectations.
Market Trajectory: From Recovery to Sustained Growth
The combine harvesters market has demonstrated resilience through recent economic fluctuations, transitioning from a period of post-pandemic adjustment into a phase of steady expansion. Historical data from 2020 to 2025 reveals a market that has consistently grown in value, reflecting the agricultural sector's ongoing need for efficiency and scale. The total revenue generated by the global combine harvesters market has shown a robust upward trend, setting a strong foundation for the forecast period extending to 2032.
Our analysis projects that this momentum will continue, with the market expected to reach substantial valuation levels by the end of the forecast horizon. The compound annual growth rate (CAGR) during the 2026-2032 period is estimated at 4.5%, indicating a healthy, sustained expansion rather than a speculative bubble. This growth is not merely a function of price inflation but is underpinned by tangible increases in unit deployment, technological upgrades, and expanding agricultural output in key regions.
Combine Harvesters Market
For enterprise strategists, this trajectory suggests a long-term opportunity window. The market size in the base year of 2025 establishes a significant benchmark, and the progression through 2026, 2027, and beyond indicates consistent year-over-year increments. However, capturing this value requires more than passive observation. The study delves into the nuances of this growth, examining how shifts in commodity prices, trade policies, and farm consolidation rates influence demand cycles. By understanding the velocity of this growth, companies can better time their investment cycles and production scheduling to match market absorption rates.
Navigating Competitive Dynamics and Industry Concentration
The competitive landscape of the combine harvesters market is characterized by a mix of established global giants and specialized regional players. Our research provides a detailed profiling of key market participants, analyzing their strategic positioning, product portfolios, and recent operational milestones. Understanding the maneuvering of these core enterprises is vital for assessing market share potential and identifying gaps in the current offering landscape.
Leading the pack is John Deere, headquartered in Moline, Illinois. The company continues to push the boundaries of precision agriculture with its S-Series and X9 combine harvesters. Recent developments highlight their focus on automation and diverse crop support. For instance, in February 2026, John Deere showcased the S4 combine harvester at the Show Rural Coopavel 2026, targeting small properties and rugged terrains with features like Machine Sync autopilot. This move underscores a strategy to penetrate niche segments while maintaining dominance in high-volume sectors through AI-driven harvesting support.
In Europe, CLAAS KGaA mbH, based in Harsewinkel, Germany, remains a formidable force. The company celebrated a significant production milestone in October 2024, with the 500,000th combine harvester rolling off its global production lines. Their portfolio, including the Lexion, TRION, and Dominator series, emphasizes scale and reliability. This anniversary edition and the volume achievement signal strong brand loyalty and manufacturing capacity that competitors must account for when planning regional expansions.
CNH Industrial N.V., operating from Amsterdam, Netherlands, continues to leverage the New Holland brand to serve large-scale farming operations. Their CR10 and CR11 models are positioned around high power and efficiency, addressing the needs of growers who prioritize throughput. Similarly, AGCO Corporation, based in Duluth, Georgia, maintains a strong presence through its Massey Ferguson and Gleaner brands, offering a diverse range of solutions that cater to varying farm sizes and crop types. These brands are integral to the market fabric, and our study analyzes their specific strengths and potential vulnerabilities in the face of changing consumer preferences.
In the Asia Pacific region, Kubota Corporation of Osaka, Japan, occupies a unique strategic position. Specializing in rice and wheat combine harvesters, Kubota has sold over 30,000 units annually, demonstrating deep penetration in specific crop markets. Their focus on unmanned autonomous models highlights the region's rapid adoption of labor-saving technologies. This regional specialization contrasts with the global breadth of Western manufacturers, creating a complex competitive environment where local expertise and global scale often intersect.
Market concentration data indicates that the top three players hold a significant portion of the market, while the top five collectively command nearly half of the total revenue. This concentration suggests high barriers to entry and the importance of scale, yet it also leaves room for specialized players who can offer differentiated technology or superior service networks in underserved areas.
Key Market Drivers and Operational Risks
A successful strategy in the combine harvesters market requires a clear understanding of the forces propelling demand and the risks that could impede it. Our study integrates recent industry context to provide a holistic view of the market dynamics that will influence performance in 2026 and beyond.
Technological Adoption and Labor Constraints
Labor availability remains a pressing constraint for the agricultural sector. Recent reports indicate that US farmers face a labor shortfall of approximately 20% for harvesting operations. This deficit is a primary driver for the increasing demand for autonomous and semi-autonomous combine harvester systems. Manufacturers like Kubota are responding with unmanned models, while others are integrating advanced autopilot and AI features to maximize the efficiency of existing labor pools. For buyers, this trend shifts the value proposition from simple mechanical performance to total operational efficiency and labor cost mitigation. Investing in technology-rich machinery is becoming a strategic imperative to ensure harvest completion amidst workforce instability.
Grain Combine Harvester Market
Regulatory Incentives and Sustainability
Regulatory frameworks are increasingly shaping procurement decisions. In the United States, the Environmental Quality Incentives Program (EQIP) provides subsidies for machinery upgrades, including combine harvesters, to encourage the adoption of eco-friendly models. This program effectively reduces the total cost of ownership for compliant equipment, incentivizing farmers to upgrade older fleets. Strategic planners must account for these subsidies when modeling market demand, as policy changes or funding availability can create sudden spikes in specific segments. Furthermore, the push towards sustainability is influencing design requirements, with emissions standards and fuel efficiency becoming key differentiators in competitive tenders.
Cost Structures and Maintenance Economics
Capital expenditure and ongoing operational costs are critical considerations for both manufacturers and end-users. The average price of a new self-propelled combine harvester typically ranges significantly depending on specifications and brand, representing a major investment for agricultural businesses. Beyond the purchase price, ownership costs are substantial. Studies suggest that annual maintenance costs for high-end combine harvesters can exceed $15,000. This reality places a premium on durability, serviceability, and parts availability. Companies that can offer lower total cost of ownership through robust engineering or predictive maintenance solutions gain a competitive edge. Our research examines how these cost factors influence buyer behavior across different farm sizes and economic regions.
Sales Volatility and Market Sentiment
While the long-term trend is positive, short-term volatility can impact planning. Recent data from the Association of Equipment Manufacturers showed that US retail sales of self-propelled combine harvesters in April 2026 were reported at 428 units, a significant decrease compared to the previous year's figures. Such fluctuations highlight the sensitivity of the market to broader economic conditions, commodity prices, and seasonal factors. Understanding the root causes of such dips—whether they stem from inventory adjustments, financing costs, or temporary demand shifts—is crucial for accurate forecasting. Our study provides the analytical framework to distinguish between noise and structural shifts in sales patterns.
Report Scope and Strategic Utility
To support these strategic insights, the PW Consulting market research study offers a depth of analysis designed for immediate operational application. The report goes beyond high-level summaries to provide actionable intelligence across multiple dimensions.
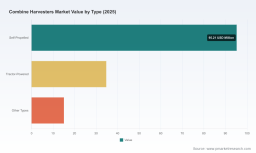
The analysis covers a comprehensive segmentation structure, allowing stakeholders to isolate performance drivers within specific categories. We examine the market by type, distinguishing between self-propelled units and tractor-powered alternatives, as well as other specialized configurations. This breakdown is essential for manufacturers targeting specific technological segments and for buyers evaluating the right equipment class for their operations. Furthermore, the study analyzes application segments, detailing how demand varies across cereal crops, corn, and other agricultural outputs. This granularity helps in aligning product features with crop-specific harvesting requirements and in identifying high-growth application areas.
Geographic analysis is another cornerstone of the research. We provide a detailed view of market performance across key regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities, from infrastructure maturity and subsidy landscapes to crop mix and farm structure. By understanding regional nuances, companies can tailor their go-to-market strategies, optimize supply chains, and prioritize investments where returns are most likely.
The report also includes a thorough competitive landscape assessment. Beyond the profiles of major players, we analyze market concentration metrics to gauge the level of competition and the potential for consolidation. This data helps in benchmarking performance and understanding the market power dynamics. Additionally, the study incorporates recent developments and news intelligence, ensuring that the analysis reflects the most current events, such as product launches, production milestones, and sales reports that may impact market perception and strategy.
Conclusion: Making Data-Driven Decisions in 2026
The combine harvesters market offers significant potential for growth, but realizing this potential requires more than intuition. It demands a rigorous understanding of historical trends, competitive actions, and the complex web of drivers influencing demand. The 4.5% CAGR projected for the forecast period underscores the opportunity, but the path to capturing value is paved with specific challenges related to labor, regulation, and cost management.
This market research study by PW Consulting is designed to be a strategic asset for leadership teams, investors, and product managers. It provides the evidence base needed to validate assumptions, identify risks, and uncover hidden opportunities. Whether you are evaluating market entry, planning capacity expansions, or refining your product roadmap, the insights contained within this report offer the clarity required to act with confidence.
For a complete view of the data, including detailed segmentation splits, regional revenue figures, and in-depth competitor benchmarking, we invite you to access the full report. The executive summary provided here highlights the breadth of the analysis, but the full intelligence package delivers the specific numbers and strategic recommendations necessary to drive your 2026 decisions. Explore the full study to secure the comprehensive market intelligence your organization needs to lead in the evolving agricultural machinery landscape.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


