



PW Consulting: Modular Data Centers Hit \$36.37B in 2025, Forecast 17.11% CAGR to \$109.88B by 2032

Modular Data Centers Market 2026: Strategic Intelligence for Enterprise Decision-Making
The digital infrastructure landscape is undergoing a structural transformation. As enterprises confront exponential data growth, AI-driven compute demands, and persistent supply chain volatility, traditional data center construction models are increasingly misaligned with operational realities. Modular data centers have emerged not as a convenience, but as a strategic imperative. Our latest comprehensive market research on the Modular Data Centers Market is designed to translate this inflection point into actionable intelligence for executive decision-makers, infrastructure planners, and investment strategists.
Drawing on historical data spanning 2020 through 2025 and a forward-looking forecast horizon extending to 2032, this report maps the trajectory of a market that has evolved from a niche deployment alternative to a mainstream architectural standard. The narrative is clear: modularization is no longer reactive. It is reshaping how organizations approach capacity planning, risk mitigation, and scalability in an era where speed-to-deployment and infrastructure agility determine competitive positioning.
The Structural Inflection Point: Why 2026 Is a Defining Year
The market has demonstrated consistent, compounding growth over the past half-decade, with revenue expanding from approximately 16.51 billion USD in 2020 to an estimated 36.37 billion USD in 2025. The trajectory does not plateau. Forecasts indicate a continued acceleration, with the market projected to reach 43.82 billion USD in 2026 and climbing toward 109.88 billion USD by 2032. This growth reflects a compound annual growth rate of 17.11 percent across the 2026–2032 period, underscoring a sustained shift rather than a temporary cycle.
Several converging forces are compressing traditional procurement and construction timelines. AI and high-performance computing workloads demand higher power density and more sophisticated thermal management. Geographic dispersion of compute, driven by edge computing requirements and data sovereignty considerations, favors deployable, standardized infrastructure over ground-up construction. Simultaneously, regulatory frameworks and industry standards are maturing to accommodate prefabricated and containerized systems, reducing historical friction around compliance, safety certification, and interoperability.
Modular Data Centers Market
For enterprise leaders, the implication is straightforward: modular data centers are no longer a contingency option. They are becoming the default architecture for organizations that must balance speed, scalability, and capital efficiency. Understanding the nuances of this shift requires more than headline growth figures. It requires a rigorous, segment-level understanding of how deployment models, application drivers, and regional dynamics interact to shape risk and return.
Decoding the Market Architecture: What This Research Uncovers
Our Modular Data Centers Market research is structured to move beyond macro trends and deliver operational clarity. The report dissects the market across multiple dimensions, enabling stakeholders to evaluate strategic fit, investment prioritization, and competitive exposure with precision.
Prefabricated And Modular Data Centers Market
Deployment Models and Architectural Strategy
The market is segmented by deployment architecture, reflecting fundamentally different approaches to scaling infrastructure. Containerized systems offer highly mobile, self-contained environments optimized for rapid deployment and constrained footprints. Prefabricated data centers provide a modular, repeatable construction methodology that blends factory-controlled quality with site-specific adaptability. All-in-one datacenter configurations consolidate power, cooling, IT, and management layers into unified deployments designed for efficiency and accelerated commissioning. Each model presents distinct trade-offs in terms of lead time, scalability limits, capital intensity, and operational complexity. The research evaluates these architectures not in isolation, but in the context of workload requirements, site constraints, and lifecycle economics.
Application-Driven Demand Patterns
Demand is not uniform across industries. Telecommunications continues to drive significant adoption as network architectures evolve toward distributed, low-latency infrastructure. Finance, healthcare, education and research, and a broad set of other enterprise applications each impose unique requirements around reliability, compliance, density, and expansion flexibility. By mapping application-level demand dynamics, the report reveals where modular deployments are gaining structural advantage and where traditional build-out models still compete effectively.
Regional Deployment Dynamics
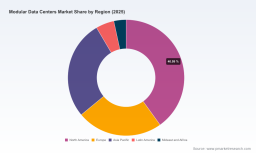
Geographic variation plays a critical role in shaping deployment strategy. Different regions exhibit distinct maturity curves, regulatory environments, supply chain conditions, and capital availability. North America reflects a mature, technology-forward market with strong enterprise and AI-driven demand. Europe demonstrates steady adoption shaped by sustainability mandates and infrastructure modernization priorities. Asia Pacific captures rapid growth driven by digital expansion, data localization trends, and expanding cloud and edge footprints. Latin America and the Middle East and Africa represent emerging opportunities where modular deployment can mitigate construction risk, address infrastructure gaps, and accelerate time-to-operation in environments where conventional development cycles face heightened friction. The report contextualizes these regional differences without reducing them to static figures, instead emphasizing the strategic implications for site selection, partnership models, and deployment sequencing.
Competitive Landscape: Strategic Positioning and Market Concentration
The modular data center ecosystem is characterized by a mix of established infrastructure leaders, specialized modular integrators, and technology providers expanding into converged infrastructure solutions. Market concentration indicates a moderately consolidated environment, with the top three competitors collectively capturing a substantial share of revenue and the top five extending that influence further. This concentration reflects both the capital and engineering intensity of modular offerings and the advantage held by players with integrated capabilities across power, cooling, IT, and deployment services.
Leading Competitors and Strategic Differentiation
Several core companies define the current competitive landscape, each pursuing distinct strategic angles:
- Vertiv emphasizes prefabricated modular data center solutions that integrate power, cooling, and IT modules for rapid deployment, with a clear focus on high-performance workloads and AI/HPC requirements.
- Schneider Electric positions EcoStruxure modular data center solutions around adaptable, high-performance designs capable of addressing complex infrastructure needs across diverse locations and operating environments.
- ABB offers modular, scalable, and prefabricated solutions aimed at accelerating colocation deployment and improving return on investment while preserving flexibility for future scaling.
- Eaton delivers SmartRack modular data center solutions that consolidate IT rack, cooling, and service enclosures within a single enclosure to optimize performance and reduce deployment timelines.
- Flex focuses on AI infrastructure platforms with pre-engineered modular designs that integrate power, cooling, and compute, targeting accelerated deployment timelines.
- Dell Technologies supports modularized integrated racks designed for edge and high-density environments, extending modular data center concepts beyond traditional facility constraints.
- M.C. Dean contributes specialized modular support rack systems and installation methods for overhead-mounted electrical and telecommunications components, addressing deployment efficiency at the infrastructure layer.
- Haskell Modular Solutions provides custom modular data center solutions built on factory-controlled fabrication, emphasizing efficiency, flexibility, and scalability.
The competitive narrative is not simply about who offers modular products. It is about who can responsibly integrate design, fabrication, deployment, and ongoing operational support while aligning with workload-specific performance demands. The research evaluates these players through the lens of technology positioning, deployment speed claims, scalability frameworks, and strategic alignment with the fastest-growing demand drivers.
Recent Strategic Movements Shaping 2026 Dynamics
Market momentum is being reinforced by concrete product and partnership developments. Eaton expanded its modular data center offering in collaboration with Flexnode to accelerate AI factory deployment, integrating power backup, racks, and cable management with the stated goal of reducing deployment schedules by a meaningful margin. Vertiv introduced a global solution built around modular design for high-performance data centers, targeting deployment scales relevant to AI and HPC requirements. Siemens launched a turnkey modular edge data center in partnership with other infrastructure providers, supporting deployment timelines suited to both permanent and interim operational needs. These moves reflect a broader industry shift: modular data centers are increasingly being engineered as integrated, workload-aware platforms rather than standalone enclosures.
Regulatory, Standardization, and Supply Chain Forces Redefining Deployment Risk
Strategic planning in this market must account for more than technology and pricing. Regulatory evolution, standardization efforts, and supply chain realities are actively shaping deployment risk and time-to-value.
Evolving Standards and Safety Expectations
The revised UL 2755:2025 outline of investigation for prefabricated modular data center systems and related modular units reflects an industry response to the operational profile of modern modular deployments, including AI-driven workloads. Updated safety and performance expectations influence design choices, certification pathways, and procurement validation. Firms that align early with emerging standards can reduce compliance friction and accelerate project approval cycles.
Intellectual Property and Deployment Method Innovation
Innovation is not limited to product hardware. Patent activity around modular support rack systems and installation methods highlights a growing focus on streamlining electrical configuration and accelerating delivery on large-scale campuses. Such developments matter because deployment efficiency is increasingly a competitive differentiator. When capacity must scale rapidly, the speed and repeatability of installation methodology can determine whether modular infrastructure delivers on its strategic promise.
Supply Chain Resilience and Standardization-Driven Efficiency
Modular deployments can reduce construction risk in regions facing supply chain constraints by shifting a greater share of fabrication and integration into controlled factory environments. At the same time, open standardization initiatives are working to improve interoperability and deployment speed across power, cooling, IT, and all-in-one modules. These factors are especially relevant for organizations planning multi-site rollouts or operating in environments where project predictability is as important as final performance.
Strategic Applications for Enterprise Decision-Makers
This research is intended to support decisions across multiple organizational functions. For infrastructure and facilities leaders, it provides a framework to evaluate deployment models against workload roadmaps, site constraints, and expansion scenarios. For procurement and sourcing teams, it contextualizes supplier capabilities, integration depth, and the strategic implications of concentration in the supplier base. For investment and corporate strategy teams, it clarifies where demand is structurally strengthening and where adoption remains contingent on regulatory, capital, or operational conditions.
Crucially, the report avoids the temptation to reduce a complex market to oversimplified segmentation percentages or isolated dollar figures. Enterprise decisions in this space depend on understanding the relationship between architecture, application demand, regional conditions, deployment speed, and long-term scalability. That is the analytical lens this research applies throughout.
Navigating the Path Forward Through Precision Intelligence
The Modular Data Centers Market is expanding at a pace that rewards organizations capable of making informed, timely decisions. Growth to 43.82 billion USD in 2026 and further expansion toward the end of the decade signals more than market opportunity. It signals a structural reordering of how compute infrastructure is designed, deployed, and scaled.
The full research report provides the detailed segmentation analysis, competitive benchmarking, regional and application-level insight, and forward-looking scenario context necessary to act with confidence. It is designed for leaders who need more than directional trends. It is built for those who must justify capital allocation, choose deployment architectures, anticipate supplier and regulatory shifts, and align infrastructure strategy with enterprise growth plans. The complete intelligence package is available through our full report, where the core segmentation data, detailed competitor analysis, and deployment scenario frameworks can be reviewed in full.
In a market defined by speed, scale, and structural change, precision intelligence is not optional. It is the foundation of sound strategy.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


