



PW Consulting Reveals 5.15% CAGR for Hydrofluoric Acid Market to Hit $4.4B by 2032

Industrial Precision Meets Market Uncertainty: Positioning Hydrofluoric Acid Strategies for 2026
The global market for Hydrofluoric Acid is entering a phase of structural reconfiguration. As industrial manufacturing, semiconductor capacity expansion, and specialty fluorochemical production converge, demand for both anhydrous and diluted grades is being reshaped by shifting raw material dynamics, evolving regulatory frameworks, and deliberate regional capacity adjustments. Over the 2026–2032 forecast horizon, the market is projected to expand at a 5.15% compound annual growth rate, with total revenue expected to scale from approximately 3.24 billion USD in 2026 to above 4.40 billion USD by 2032. This trajectory underscores a market that is growing steadily in absolute terms, yet operating against a backdrop of operational complexity that requires disciplined strategic planning.
For corporate decision-makers, procurement leaders, and investment committees, the critical question is no longer whether hydrofluoric acid demand will rise, but how to align sourcing architectures, pricing strategies, and long-term capital allocations with a supply landscape that is simultaneously consolidating in some corridors and fragmenting in others. Our latest market research study was designed to translate macro growth indicators into actionable intelligence, equipping executives with the visibility required to navigate this environment with precision.
A Market Profile Built on Measured Expansion and Concentrated Capability
Historical performance from 2020 through 2025 demonstrates a market that has consistently added value year over year, moving from 2.50 billion USD to 3.09 billion USD. The acceleration observed in 2024 and 2025 reflects broader industrial recovery, sustained downstream demand for fluoropolymers and refrigerants, and continued utilization in electronics and glass processing applications. Yet growth alone does not reveal the full strategic picture. The market’s competitive intensity, regional production footprints, and reliance on specific upstream inputs all shape the risk-return profile for buyers and producers alike.
Our analysis highlights a market structure in which a relatively small group of global participants commands a significant share of total output, reinforcing the importance of supplier selection, contract design, and geographic diversification. For enterprises relying on hydrofluoric acid as a feedstock or process chemical, understanding where capacity is concentrated, how logistics corridors operate, and which production sites are expanding or contracting is essential to managing continuity risk. Rather than treating hydrofluoric acid as a commoditized input, leading organizations are beginning to approach it as a strategically managed material with direct implications for product quality, schedule reliability, and compliance posture.
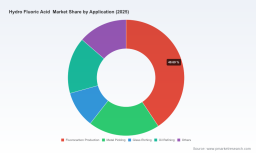
The report maps these structural realities across multiple analytical lenses. It examines the balance between anhydrous and diluted product streams, evaluates the principal industrial applications driving consumption, and contextualizes regional demand patterns within broader manufacturing and regulatory environments. By integrating these dimensions into a single framework, the study enables readers to anticipate how shifts in one part of the value chain may cascade into cost structures, availability, and sourcing strategies elsewhere.
Strategic Content Designed for Executive Decision-Making
A robust market study should do more than report numbers. It must translate market behavior into decision-ready insight. Our research is organized to support a range of corporate use cases, from capacity planning and supplier negotiations to M&A screening and regulatory risk assessment. The report combines quantitative forecasting with qualitative analysis of the operational and policy forces shaping the industry.
Hydro Fluoric Acid Market
Readers will find detailed evaluations of market size and growth trajectories, segment-level demand patterns, and the competitive positioning of leading producers. Equally important, the study examines the forces that introduce volatility and opportunity into the market, including upstream fluorspar availability, transboundary trade flows, plant-level capacity decisions, and regulatory initiatives that affect end-use product classification. This multi-layered approach ensures that executives are not left to infer relationships between separate data points, but are instead presented with an integrated view of how supply, demand, and policy interact over the forecast period.
Aluminium Fluoride Market
In practical terms, the report supports scenarios such as evaluating whether to secure long-term supply agreements, identifying where regional price dynamics may create sourcing advantages, and assessing how changes in production footprints could alter lead times or logistics costs. It also serves as a reference point for understanding how major participants are positioning themselves across applications and geographies, which can inform partnership strategies and competitive benchmarking.
Competitive Landscape and Capacity Realignment
The hydrofluoric acid market is defined by a blend of globally scaled producers and regionally focused manufacturers, each with distinct operational strengths and downstream linkages. Several multinationals anchor the market with large-scale production sites that serve fluorochemical, refrigerant, aluminum, and electronics applications. Their presence shapes pricing expectations, supply reliability, and technical service capabilities across multiple regions.
At the same time, a notable set of regional specialists contributes important capacity in specific markets, often with strong positioning in high-purity grades, custom blends, or application-specific formulations. These participants play a critical role in meeting localized demand and can provide strategic flexibility for buyers seeking to diversify their supplier base or reduce exposure to single-source dependencies.
Recent corporate and operational developments illustrate how active this landscape is becoming. Capacity adjustments at select European facilities, ongoing focus on North American production advantages, and sustained investment in Asian manufacturing nodes all point to a market where geographic sourcing strategy matters more than ever. For procurement and operations leaders, the key is to understand not only who the major players are, but how their production footprints, product grades, and downstream integration strategies align with specific application requirements and regional demand profiles.
The study evaluates these competitive dynamics in detail, including company profiles, facility contexts, and the strategic implications of recent industry actions. By connecting corporate activity to broader market movement, the report helps readers identify where competitive pressure is most likely to influence pricing, where service differentiation may create supplier loyalty, and where structural shifts could open opportunities for alternative sourcing approaches.
Regulatory Signals, Raw Material Constraints, and Trade Flow Shifts
Market growth does not occur in a vacuum. The hydrofluoric acid sector is being influenced by a series of concurrent forces that affect both supply security and downstream demand elasticity. On the regulatory front, authorities in key jurisdictions are intensifying scrutiny of products and applications that incorporate hydrofluoric acid. Notably, a rulemaking process initiated in mid-2026 in California is examining cleaning products containing hydrofluoric acid for potential classification as a Priority Product. While this action targets a specific end-use category, it reflects a broader trend in which chemical safety, product stewardship, and consumer-facing regulations are becoming more prominent in market planning.
On the supply side, raw material conditions remain an important consideration. Global fluorspar production has experienced modest contraction, with total mine output decreasing slightly in 2025. This matters because fluorspar is a foundational input for hydrofluoric acid production, and changes in mining output, safety inspections, and export patterns can influence domestic and international pricing dynamics. In parallel, import behavior in major consuming regions has shown significant movement, including a sharp increase in certain fluorspar import volumes during the first half of 2025 as market participants navigated domestic mining inspections and rectification measures.
Trade patterns are also evolving. In North American supply channels, a substantial share of hydrofluoric acid imports has been traced to neighboring sourcing corridors, with Mexico accounting for an outsized portion of U.S. import volume during 2025. This concentration has implications for logistics reliability, tariff exposure, and supply chain resilience, particularly for organizations that depend on consistent availability across multiple manufacturing sites.
Compounding these dynamics are deliberate capacity actions by established producers. Some European operations are scaling back or restructuring specific hydrogen fluoride activities by the end of 2026. Such moves can reroute demand to alternative suppliers, alter regional price balances, and prompt downstream users to reassess their sourcing continuity plans. Our report integrates these developments into a cohesive dynamics section, helping readers interpret how policy, raw material conditions, and facility-level decisions may interact over the forecast window.
Translating Forecasts into Operating Decisions
For executives, the practical value of market research lies in its ability to reduce uncertainty in high-stakes decisions. The hydrofluoric acid market presents a clear example of why top-line growth figures must be paired with segment, regional, supplier, and regulatory context. A company evaluating expansion in fluorochemical production, for example, needs to understand more than aggregate demand trends. It must consider which product grades are most relevant, how regional availability may differ, and which suppliers offer the strongest combination of scale, reliability, and technical support.
Similarly, procurement teams must weigh the trade-offs between consolidated sourcing and diversified supply chains, especially in a market where a handful of large producers hold significant share. Contract structures, inventory strategies, and logistics planning may need to be adjusted as capacity realignments and regulatory developments reshape the availability landscape. The report is built to support these decisions by offering a structured assessment of where growth is concentrated, where risks emerge, and where strategic flexibility can be created.
Why This Study Matters for 2026 Planning Cycles
The 2026 planning cycle arrives at a time when industrial markets are being tested by overlapping pressures: material input constraints, shifting trade flows, regulatory recalibration, and competitive repositioning. In this environment, organizations that rely on fragmented or outdated intelligence risk making sourcing, pricing, and investment decisions with incomplete visibility. A comprehensive market study provides the baseline needed to separate short-term noise from structural change.
Our research is designed to give decision-makers a clear, evidence-based foundation for action. It connects historical performance, forward-looking forecasts, competitive dynamics, and regulatory developments into a single analytical narrative. This allows leadership teams to evaluate scenarios with greater confidence, identify early indicators of change, and align commercial strategy with operational realities.
How to Use the Full Analysis
This introduction highlights the strategic contours of the market and the analytical approach behind the study, but the complete research contains the detailed segmentation, supplier evaluations, regional comparisons, and scenario-based insights required for execution-level planning. The full report is structured to support immediate operational use while also informing longer-term strategic direction.
Readers seeking a deeper understanding of hydrofluoric acid market dynamics, competitive positioning, and forward demand pathways are encouraged to access the complete publication. There, the full dataset and interpretive analysis provide the granularity necessary to convert market intelligence into concrete decisions across sourcing, capacity planning, risk management, and growth strategy.
Conclusion
The hydrofluoric acid market is expanding, but its growth is unfolding within a complex and actively changing operating environment. Supply concentration, raw material variability, regulatory attention, and regional capacity realignment all influence how organizations should plan for 2026 and beyond. By integrating market size projections with competitive and regulatory context, this research offers a practical foundation for strategic decision-making. For executives who need more than headline numbers, the full study provides the depth, structure, and actionable insight required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Hydro Fluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


