



PW Consulting: Specialty Paper Market to Hit $486.17M by 2032 with 5.1% CAGR; Asia Pacific Leads at $125.41M

Navigating the Specialty Paper Market in 2026: A Strategic Imperative for Forward-Looking Enterprises
The global specialty paper market is entering a decisive phase of structural transformation, shaped by shifting supply chains, evolving regulatory frameworks, and an accelerating demand for high-performance fiber-based materials. As organizations across packaging, pharmaceutical, retail, and industrial sectors recalibrate their procurement and innovation strategies, access to precise, forward-looking market intelligence has transitioned from a tactical convenience to a core strategic necessity. This market research report is designed to equip executive teams, commercial leaders, and supply chain planners with the analytical depth required to make informed, resilient decisions throughout the 2026-2032 forecast horizon.
What makes this research particularly relevant for 2026 decision-making is its deliberate focus on the intersection of macro market trajectories and micro-level competitive dynamics. Rather than presenting a superficial overview, the study maps how historical growth patterns, capacity reallocations, raw material fluctuations, and product innovation cycles converge to create both margin pressure and new value-creation opportunities. The findings are structured to help decision-makers identify where to invest, where to consolidate, and where to reposition portfolios before market signals become widely visible to competitors.
Below, we outline the core analytical architecture of the report and explain why it serves as a critical navigation tool for enterprises operating in an increasingly complex specialty paper ecosystem.
The 2026 Market Landscape: Trajectory, Scale, and Structural Shifts
Understanding the specialty paper sector today requires a clear view of its recent growth arc and the momentum carrying it into the mid-decade period. Drawing on a comprehensive historical baseline spanning 2020 through 2025, the analysis traces a consistent expansion pattern that reflects both secular demand drivers and cyclical supply-side adjustments. The market has demonstrated a compound annual growth rate of 5.1 percent across the forecast window extending to 2032, a trajectory that underscores the durable appeal of specialty grades even as broader pulp and paper segments face periodic volatility.
Specialty Paper Market
This growth is not occurring in a vacuum. By the base year of 2025, the overall market had reached a valuation of 343 million USD, and momentum is projected to carry that figure to approximately 372.9 million USD in 2026. Looking further ahead, the forecast sequence indicates continued upward progression, reaching an estimated 486.17 million USD by 2032. These figures are more than aggregate statistics; they represent the combined effect of premiumization trends, replacing conventional paper grades with higher-margin specialty solutions, and broadening application scopes across regulated and performance-sensitive industries.
Worldwide Specialty Ink Market
Crucially, the research frames these headline numbers within a broader narrative of market recalibration. The period between 2026 and 2032 will be defined not simply by growth, but by how growth is distributed across product types, end-use sectors, and geographies. Because the report deliberately avoids diluting its strategic message with exhaustive segment-level breakdowns, readers are guided toward the complete intelligence package where these nuances are fully mapped. This approach preserves strategic clarity while preserving the analytical rigor that procurement and commercial teams need when evaluating long-term commitments.
Core Report Architecture: What Decision-Makers Will Gain
A market study earns its place on the executive dashboard only when it translates data into action. This report is built around that principle. Its architecture is organized to support multiple decision-making functions simultaneously: market sizing and forecasting, segmentation logic, competitive positioning, regulatory and input-cost dynamics, and strategic scenario interpretation. Each section is designed to feed directly into commercial planning, product portfolio reviews, and supply chain risk assessments.
Comprehensive Market Sizing and Forward Forecasting
At the foundation of the report lies a rigorously constructed market model that reconciles historical performance with forward-looking estimates. The forecast framework extends through 2032, allowing readers to evaluate not just the next twelve months, but the multi-year arc that shapes capital allocation, capacity planning, and partnership strategy. The modeling methodology accounts for the interplay between volume expansion, pricing behavior, and substitution effects, ensuring that projections do not rely on simplistic extrapolations.
Segmentation Logic Built for Strategic Application
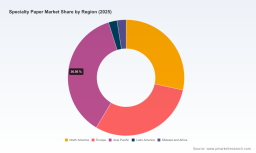
One of the most actionable dimensions of the study is its segmentation approach. The analysis disaggregates the market along multiple axes that matter to commercial leaders, including product type, application end-use, and regional distribution. Rather than presenting these dimensions as isolated tables, the report explains how each segment behaves under different economic and regulatory conditions, and where structural shifts are most likely to alter competitive standings over time.
Within the type-based view, the report examines how packaging-related specialty papers, release liner papers, decor papers, thermal and carbonless papers, industrial specialty grades, and other niche categories are evolving in response to application requirements and manufacturing economics. In parallel, the application lens explores how demand patterns differ across food and beverage, pharmaceutical, retail and e-commerce, building and construction, and additional end-use categories. The regional dimension further enriches the analysis by highlighting where demand intensity, capacity deployment, and competitive pressure converge. Full segment-level breakdowns, including detailed revenue distributions and comparative growth profiles, are reserved for the complete report to preserve the depth that subscribers and strategic users require.
Competitive Dynamics: A Contested but Structurally Stable Arena
The specialty paper market is characterized by a competitive landscape that balances concentrated leadership with active consolidation and capability expansion. According to the report's market concentration assessment, the top three players command approximately 35 percent of the market, while the top five collectively hold around 50 percent. This distribution suggests a sector where scale advantages matter, yet where mid-tier and specialized manufacturers can still compete through product differentiation, technical grade specialization, and regional service strength.
Several established players anchor this landscape, each bringing distinct positioning and technical capabilities. Neenah Paper, headquartered in Wisconsin, manufactures premium packaging and specialty paper products tailored for packaging applications. Pixelle Specialty Solutions, based in Pennsylvania, produces a broad portfolio of specialty papers serving commercial printing, labels, and technical applications. UPM, operating from Finland, offers specialty papers under its specialty papers division with a focus on flexible packaging and industrial uses. International Paper, a major global player headquartered in Tennessee, integrates specialty paper offerings within its broader cellulose fibers and packaging segments. Stora Enso, also Finnish, specializes in renewable materials and high-strength specialty paper grades used in packaging and labeling. Mondi, based in Vienna, manufactures specialty papers for industrial and consumer packaging applications, while Sappi, headquartered in South Africa, produces specialty papers including those used in textiles and dissolving pulp applications.
The landscape also includes Ahlstrom, which develops fiber-based specialty materials for filtration, food packaging, and technical uses; Burgo Group in Italy, producing communication, specialty, and packaging papers; Twin Rivers Paper in the United States, continuing operations in specialty paper manufacturing following acquisition activity; and Ivex Specialty Paper, which manufactures specialty grades including crepe and kraft papers for industrial and technical uses. Together, these companies illustrate a competitive field defined by product specialization, geographic reach, and ongoing investment in processing capability.
Recent Developments Redefining Strategic Postures
Competitive positioning in the specialty paper market is not static. Recent transactions and commercial moves signal where incumbents are placing bets on future capability and where market structure may continue to tighten. In May 2026, Twin Rivers Paper completed the acquisition of Potsdam Specialty Paper Inc., a move designed to expand specialty paper production capabilities. That same month, Ahlstrom acquired Pixelle's Stevens Point mill to expand technical-grade specialty paper capacity. Both developments underscore a pattern of targeted consolidation aimed at strengthening technical throughput and broadening product portfolios.
Beyond M&A, product and pricing actions are also shaping near-term market conditions. In February 2026, Stora Enso expanded its barrier-coated paper range for food packaging using advanced fiber-based materials, reinforcing the trend toward performance-enhanced, fiber-based alternatives in regulated end-markets. Earlier in the year, in March 2026, Sun Paper announced a price increase of CNY 300 per tonne for its white kraft paper products, effective 5 March. These moves reflect both demand resilience and the pricing pressure linked to input cost dynamics.
Industry Dynamics: Input Costs, Regulation, and Regional Rebalancing
A deeper understanding of the specialty paper market requires attention to the forces that influence pricing power, capacity deployment, and competitive intensity. Several contextual developments recorded in early 2026 illustrate the operating environment that firms must navigate. Pulp price hikes have triggered price increases across specialty paper products, including kraft grades, adding complexity to margin management and procurement planning. At the same time, environmental protection policies and capacity expansions in China are intensifying competition in specialty paper production, altering the balance between established export-oriented supply and domestic demand growth.
These pressures interact with strategic capacity decisions elsewhere in the market. For example, Mondi ramped up its FunctionalBarrier Paper Ultimate line at its Solec plant in Poland to support European and Asian markets, signaling continued investment in functional, barrier-enhanced grades that align with packaging and regulatory demands. In parallel, International Paper closed two Georgia mills in August 2025 to streamline operations and focus on higher-value specialty paper segments, a clear example of portfolio rationalization in favor of more profitable niches.
On a macro level, China accounted for approximately 30 percent of global specialty papers capacity in 2025, with a measurable shift toward export markets. This structural fact has important implications for price formation, supply availability, and competitive strategy across regions. The report integrates these dynamics into a cohesive analytical narrative, helping readers assess how input volatility, regulatory intervention, and regional capacity reallocation will affect sourcing decisions and market positioning through the forecast period.
Why This Research Matters for 2026 Enterprise Decisions
Executive teams face a common challenge in markets like specialty paper: the need to distinguish durable structural trends from short-term noise. Price fluctuations, isolated capacity announcements, and product launches can all create temporary signals, but only a disciplined analytical framework can separate transient events from strategic inflection points. This report is built to serve that function.
For procurement and sourcing leaders, the study provides a structured basis for evaluating supplier stability, capacity reliability, and pricing trajectories across types and applications. For product and portfolio teams, it offers insight into where performance-driven demand is expanding and where substitution risk may emerge. For corporate strategy and planning functions, the forecast architecture supports scenario analysis around growth rates, regional demand shifts, and competitive consolidation. And for investors and market analysts, the combination of concentration metrics, company profiles, and recent developments creates a reliable foundation for assessing sector momentum and value creation pathways.
Importantly, the report is designed to be used, not merely read. Its segmentation logic, competitive mapping, and dynamic context enable cross-functional alignment around a shared understanding of market mechanics. This is especially valuable in 2026, when enterprises must coordinate sourcing, innovation, and regulatory compliance strategies in environments where input costs and capacity geography are increasingly intertwined.
What the Full Report Delivers
This overview has outlined the strategic lens, market scale, competitive structure, and industry dynamics that frame the specialty paper market as it moves through 2026 and beyond. The complete research document goes further, providing detailed segmentation distributions, granular regional and application analysis, extended company profiles, and a fuller integration of the recent developments and industry context shaping competitive outcomes. Readers seeking full segment-level revenue breakdowns, comparative growth profiles, and comprehensive regional intelligence will find the complete edition structured to support direct application in commercial planning and strategic review sessions.
To access the complete dataset, segmentation matrices, and detailed competitive intelligence, visit the source page for the full Specialty Paper Market research. The full report transforms this high-level strategic framing into an operational toolkit, ensuring that your 2026 decisions are grounded in market intelligence that is both current and actionable.
For detailed analysis of this topic, please visit the official page: Specialty Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


