



PW Consulting: Intranasal Drug Delivery Devices Market to Hit $3,435.95M by 2032, 8.98% CAGR

Navigating the 2026 Landscape: Why Strategic Intelligence on Intranasal Drug Delivery Devices Matters
The global landscape for intranasal drug delivery devices is undergoing a structural transformation. As therapeutic pipelines increasingly target rapid onset, patient-centric administration, and alternative routes to systemic circulation, device engineering has moved from a supporting function to a core strategic differentiator. For executive teams, innovation directors, and market access strategists, understanding the mechanics of this shift is no longer optional. The decisions made in 2026 around platform selection, partnership structuring, and regulatory positioning will directly shape commercial viability through the end of the decade.
This article outlines the strategic rationale behind our latest market research release and demonstrates how granular, forward-looking intelligence can be translated into actionable corporate strategy. The analysis aligns with a forecast horizon spanning 2026 through 2032, anchored in a five-year historical baseline that captures the market’s acceleration from 2020 onward. Rather than offering high-level abstractions, the research is structured to support capital allocation, product roadmap planning, and competitive positioning with precision.
Macro Trajectory and the 2026 Decision Context
The market’s growth arc over the past half-decade has been defined by consistent expansion and rising structural complexity. Revenue progression from the early 2020s through the 2025 base year reflects sustained commercial adoption, alongside incremental breakthroughs in formulation-device compatibility. Looking forward, the trajectory points toward a compound annual growth rate that underscores both the market’s maturation and its ongoing capacity for value creation. The implication for 2026 decision-makers is clear: growth is no longer a lagging indicator but an active planning parameter that shapes R&D investment cycles, commercial scaling timelines, and partnership economics.
At this stage, the market’s scale and momentum create a dual imperative. Organizations must simultaneously defend existing device portfolios while evaluating next-generation platforms that address unmet clinical needs, such as improved deposition consistency, dry powder handling, and nose-to-brain targeting. Navigating this tension requires more than industry headlines. It demands a structured view of how device architectures, regulatory pathways, and reimbursement environments intersect across therapeutic categories.
Structural Shifts Defining Competitive Positioning
Several interrelated dynamics are reshaping how companies evaluate intranasal delivery opportunities. Regulatory frameworks continue to evolve, with classification pathways and clearance mechanisms influencing time-to-market for both established and novel device configurations. At the same time, reimbursement environments are creating differentiated commercialization pathways, particularly where approved nasal spray products and clinical-use devices benefit from established coverage structures. These dynamics are not isolated; they interact with manufacturing scale-up requirements, device reliability expectations, and formulation constraints.
Saline Nasal Mist Market
For device manufacturers and biopharma partners alike, the strategic challenge lies in anticipating where regulatory and reimbursement clarity will create entry opportunities, and where device differentiation will become the decisive commercial lever. Reports that map these forces against actual device types, application categories, and regional adoption patterns equip leadership teams with the context needed to prioritize resource deployment with confidence.
What the Research Delivers: Operational Depth for Real-World Strategy
Our newly released study is designed to convert market complexity into decision-ready intelligence. Rather than stopping at headline figures, the research examines the structural components that determine where value is created and captured across the intranasal delivery ecosystem. The analysis is built to support cross-functional planning, enabling teams to compare platform strategies, assess adoption trajectories, and evaluate competitive pressure points with a shared evidence base.
- Comprehensive market sizing and forward projections that define the revenue environment through 2032, providing a clear quantitative frame for investment and commercialization planning.
- A device-centric segmentation lens that distinguishes between multi-dose systems, unit-dose systems, and other delivery configurations, enabling platform-level benchmarking and portfolio alignment.
- An application-focused view that maps device deployment across therapeutic use cases, supporting formulation strategy, indication prioritization, and target product profile development.
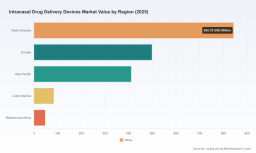
- Regional market assessment that contextualizes geographic adoption patterns without reducing the analysis to superficial share breakdowns, helping teams gauge where infrastructure, clinical practice, and channel readiness differ.
- Competitive profiling of leading device manufacturers and development partners, including capabilities, platform focus, and recent strategic activity that signals where the market is heading.
- Regulatory and reimbursement context that ties device classification, clearance pathways, and coverage dynamics to commercialization feasibility.
- Scenario-ready interpretation for planning around partnerships, licensing, manufacturing scaling, and device adoption in both branded and generic-adjacent environments.
Competitive Landscape: Device Capability as Strategic Currency
The companies shaping this market are increasingly competing on platform versatility, formulation compatibility, and speed of execution. The leading device manufacturers and development organizations in this space reflect a market that values precision delivery, scalability, and integration across the drug-device lifecycle. Their strategic activity provides an early signal of where device innovation is concentrating and how commercial partnerships are being structured.
Aptar Pharma continues to reinforce its position as a broad-platform provider, offering single-dose, two-dose, and multi-dose nasal spray pump solutions designed for liquid and powder formulations. Its recent utilization in a Phase II clinical study for an investigational nasal spray illustrates how device performance is increasingly tied to clinical-stage credibility and downstream commercialization readiness. In parallel, the market is seeing targeted expansion from specialists and innovators. Teleflex remains associated with mucosal atomization devices that support atomized intranasal delivery, an approach that has become relevant in specific clinical and emergency-use contexts.
Bespak brings a strong focus on drug-device combination products, spanning multi-dose aqueous nasal sprays and specialized unit-dose systems. Silgan Dispensing contributes additional dispensing and pump technology designed for intranasal delivery, reinforcing the importance of mechanical precision in everyday administration. Hovione represents the integrated CDMO angle, linking API-to-device solutions with single-use dry powder devices and emphasizing how development partnerships can shorten device-platform qualification cycles. Kindeva Drug Delivery adds further combination-product depth across nasal spray and MDI-type delivery configurations, while Nemera engages with dry powder and drip-dose-style platforms that connect intranasal delivery to broader nose-to-brain applications. Aero Pump rounds out the competitive field with spray pump and device engineering geared toward precise delivery needs.
Recent 2026 developments reinforce how rapidly strategic activity is accelerating. Zeteo Biomedical introduced metered-unit-dose dry powder and biologics delivery devices intended for nasal and nose-to-brain administration, highlighting the growing importance of precision dosing in emerging formulation categories. Nemera’s partnership expansion to strengthen intranasal applications demonstrates how platform fit is becoming a deliberate partnership criterion. At the same time, Hovione’s announcements around integrated intranasal drug delivery platform availability point to a broader trend in which commercial readiness and device accessibility are increasingly bundled together as value propositions.
These moves matter because the market’s concentration profile indicates that a relatively small group of participants holds a substantial share of industry revenue. That concentration creates both pressure and opportunity. New entrants and incumbent challengers must determine whether to compete through platform differentiation, niche clinical applications, regional strength, or partnership leverage. Without detailed device-level and application-level analysis, those decisions risk being misaligned with actual market economics.
Where 2026 Strategy Meets Tactical Execution
As organizations plan for the remainder of this year and beyond, several strategic questions repeatedly surface. Should a company prioritize a multi-dose platform for chronic or repeat-use settings, or build capability around unit-dose and specialized delivery formats that support simplified administration and controlled dispensing? How should device strategy align with formulation ambitions, especially in dry powder, biologic, and rapid-onset rescue scenarios? Which partnership models will accelerate device qualification, manufacturing readiness, and market access without compromising differentiation?
The answer to each question depends on more than general market growth. It depends on how device adoption, therapeutic demand, and commercial viability intersect across segments and regions. A comprehensive research framework allows leadership to test assumptions, compare platform economics, and identify where competitive exposure is highest. It also supports more disciplined conversations with internal R&D, external partners, and commercialization teams by replacing speculation with evidence-based reference points.
The highest-value applications of this research typically emerge in three areas. First, in portfolio strategy, where organizations need to decide which device architectures deserve incremental investment and which require redesign or exit. Second, in partnership and outsourcing planning, where companies evaluate device suppliers, CDMOs, and combination-product collaborators based on capability fit and development timelines. Third, in commercial and regulatory sequencing, where device classification, clearance expectations, and reimbursement readiness influence launch planning and indication prioritization.
Intranasal Drug Delivery Devices Market
In each case, the value lies not in a single number but in the relationship between numbers, segment characteristics, and strategic context. That is precisely the level of analysis required for 2026 planning and beyond.
Why the Full Report Is the Strategic Next Step
Market summaries can establish direction, but they rarely provide the resolution needed for investment decisions, partnership evaluation, or product roadmap alignment. This study is built to close that gap. It combines forward-looking market sizing with device-type, application, and regional context, then ties that structure to competitive activity and regulatory dynamics. The result is an evidence base that can be used to benchmark positioning, test new market entries, and align cross-functional teams around a shared view of opportunity.
For executives evaluating where to commit resources in 2026, the full research offers the practical detail needed to move from strategic hypothesis to operational plan. The complete dataset, segmentation breakdown, and competitive interpretation are available through the original report page, where the full analysis can be reviewed in the context of your organization’s specific priorities.
Conclusion: Intelligence as a Competitive Discipline
Intranasal drug delivery devices are no longer a niche consideration. They are an integral part of how faster onset, improved patient experience, and alternative delivery pathways are being commercialized across multiple therapeutic areas. The companies that succeed in this environment will be those that combine platform technology with disciplined market interpretation. Strategic clarity in 2026 will depend on access to structured, decision-grade intelligence that connects growth dynamics, competitive behavior, and commercial feasibility.
The full research release provides that foundation. For teams seeking to align product strategy, partnership models, and market entry planning with the realities of an expanding and increasingly sophisticated market, the complete analysis is the essential next step.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


