



PW Consulting: Global Boat Insurance Hits $335M in 2025, Projects 5.85% CAGR to $475M by 2032

Navigating Swells and Headwinds: The Strategic Imperative of the 2026 Boat Insurance Market
The global marine insurance landscape is entering a decisive inflection point. As recreational boating rebounds, commercial maritime activity accelerates, and regional regulations reshape liability expectations, insurers, investors, and maritime service providers must recalibrate their strategies for the years ahead. Our latest Boat Insurance Market research delivers a comprehensive, data-driven blueprint for 2026 decision-making, tracing the market's trajectory from a 2025 baseline of 335.0 million USD through a forecast horizon that extends to 2032. With a projected compound annual growth rate of 5.85 percent, the industry is not merely expanding—it is restructuring around new risk profiles, digital distribution models, and tightening compliance frameworks. This article previews the strategic architecture of the full report, highlights the competitive dynamics that will define the next cycle, and outlines why precise, forward-looking intelligence is no longer optional for organizations operating in or adjacent to the marine sector.
Why 2026 Demands a Fresh Strategic Lens
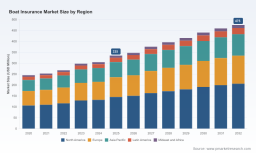
Market evolution rarely follows a straight line, and the boat insurance segment is a textbook example of how macroeconomic shifts, regulatory interventions, and consumer behavior converge to create new value pools. The historical window from 2020 to 2025 tells a story of resilient recovery: revenue climbed from 245.0 million USD to 335.0 million USD, reflecting both pent-up demand for recreational watercraft and a steady normalization of commercial marine operations. Yet the forward view—spanning 2026 through 2032—signals more than continuation. The market is expected to reach approximately 475.0 million USD by 2032, a trajectory that will reward players who can balance underwriting discipline with innovative product design and distribution agility.
For enterprise strategists, the critical insight is that growth will be uneven across risk categories, vessel types, and geographies. The macroeconomic narrative alone obscures the operational realities that separate outperforming carriers from those that merely participate. Premium pricing structures are being recalibrated in high-exposure coastal markets, where storm-related risks and reinsurance pressures have driven rate adjustments in the range of 15 to 25 percent for boaters in certain jurisdictions. At the same time, regulatory mandates are beginning to codify minimum liability thresholds for specific horsepower classes and watercraft categories, fundamentally altering risk pools and compliance costs. These are not peripheral developments; they are the structural forces that will shape portfolio performance, loss ratios, and customer acquisition economics over the forecast period.
Our report is built to help decision-makers navigate this complexity without getting lost in aggregated noise. It maps the market's growth arc, interrogates the segmentation drivers that matter most, and connects high-level trends to actionable priorities in pricing, product mix, channel strategy, and geographic expansion. The full document delivers the granular breakdowns necessary to benchmark against peer positioning, while this overview establishes the strategic context that every leadership team should internalize before setting 2026 objectives.
Anatomy of the Report: What Decision-Makers Will Find Inside
A market research asset earns its place in the C-suite only when it translates macro trends into operational clarity. The Boat Insurance Market study is structured to serve that purpose across multiple functional domains, from underwriting and actuarial planning to market entry, partnership evaluation, and capital allocation. The following elements define its practical orientation:
- Historical baseline and forecast architecture: The analysis anchors its projections in a rigorously documented historical dataset covering 2020 through 2025, then extends forward through 2032. This dual lens enables readers to test whether current strategies are aligned with observed momentum or whether adjustments are needed to capture the next phase of growth.
- Segmentation deep dives: The report disaggregates the market across coverage types, vessel applications, and regional dynamics. Rather than presenting static snapshots, it examines how each segment contributes to overall revenue momentum, where concentration risk is building, and which subsegments are poised to outpace the market average.
- Competitive landscape mapping: Profiles of leading carriers and specialty providers are integrated with an assessment of market concentration, giving stakeholders a clear view of how incumbency, specialization, and digital capability influence share dynamics. The analysis is designed to support competitive benchmarking, partnership screening, and white-space identification.
- Regulatory and risk environment scanning: Because marine insurance sits at the intersection of asset protection, liability exposure, and jurisdiction-specific compliance, the report incorporates recent regulatory developments and pricing signals. These insights help organizations anticipate shifts in minimum coverage requirements, policyholder expectations, and loss-cost trajectories.
- Operational and commercial implications: Beyond description, the study connects market structure to practical decisions—how to price in environments where homeowners policies offer only limited boat damage coverage, how to position products for recreational versus commercial segments, and where technology-enabled underwriting can create differentiation in a market that remains meaningfully concentrated.
Each component is calibrated to reduce the gap between insight and execution. Readers will find not only the quantitative scaffolding required to model scenarios, but also the qualitative framing needed to interpret what those numbers mean for product strategy, risk appetite, and go-to-market timing.
Market Structure and Competitive Dynamics
The boat insurance market is characterized by a distinctive blend of scale players, specialty specialists, and emerging technology-forward entrants. Concentration remains significant, with the top three carriers accounting for approximately 62.5 percent of market revenue and the top five reaching roughly 74.2 percent. This level of consolidation signals both the barriers to broad-based entry and the opportunities for focused differentiation. Organizations that can combine underwriting expertise with targeted product design, efficient digital quoting, and strong affinity or membership relationships are well positioned to capture share even in a crowded field.
Several established carriers illustrate the strategic diversity that defines the current landscape. Progressive has built recognition around personal watercraft and recreational vessel policies, emphasizing online quoting and safety-course discounts that appeal to cost-conscious, digitally native boaters. Markel focuses on boat and yacht coverage that spans fishing boats, runabouts, and commercial use, offering tailor-made policies for unique vessels and discounts of up to 35 percent—an approach that speaks directly to niche risk profiles and high-value customer relationships. Chubb provides boat and yacht insurance for vessels valued up to 3 million USD, supported by recreational marine specialists who serve pleasure boats with a premium-service orientation. Travelers extends coverage up to 80 feet and includes special event coverage, broadening its appeal to owners who require flexible protection for seasonal or situational exposure. Liberty Mutual delivers quotes and coverage for both recreational and commercial watercraft, reinforcing the importance of cross-segment capability. Cincinnati Insurance supports a wide vessel size range, from boats under 20 feet to those over 80 feet, with agreed value options and equipment or towing endorsements that address common owner concerns. Ahoy! Insurance represents the tech-driven flank of the market, offering admitted and excess/surplus marine insurance for vessels up to 95 feet and 2.5 million USD in value. BoatUS anchors a member-focused model with policies underwritten by GEICO Marine Insurance Company for recreational vessels, while Foremost specializes in personal watercraft and PWC coverage, reflecting the ongoing demand for category-specific underwriting.
What ties these profiles together is not uniformity but strategic segmentation. The market rewards carriers that can articulate a clear value proposition for a defined risk pool, whether that means superior digital convenience, tailored commercial coverage, high-value yacht specialization, or membership-based trust. At the same time, the concentration data suggests that scale advantages in distribution, claims handling, and reinsurance negotiation remain powerful. The report examines these dynamics in detail, helping leaders understand where incumbent strength is most entrenched and where differentiated offerings can still punch above their weight.
Travel Insurance Market
The competitive picture is also being reshaped by recent moves that signal where the market is heading. In February 2025, Ahoy! Insurance expanded its admitted and excess/surplus marine insurance offerings into Florida, widely recognized as the world's largest boating market, with flexible policies for vessels up to 95 feet and 2.5 million USD in value. This geographic expansion underscores a broader pattern: carriers are increasingly targeting high-density, high-exposure regions with products designed to address both admitted and surplus lines needs. The move also reflects the growing importance of regulatory-aware underwriting in states where storm risk, reinsurance dynamics, and owner expectations converge to create complex pricing environments.
On the regulatory front, January 2025 saw the South Carolina Department of Natural Resources introduce Bill 26, which requires liability insurance for watercraft over 70 horsepower, personal watercraft, and specialty propcraft, with minimum coverage of 50,000 USD. Proof of insurance must be provided at title and registration, and violations carry misdemeanor penalties, with fines directed into boater training programs. This type of mandate is emblematic of a wider shift toward formalized liability requirements in select jurisdictions. It directly affects risk pools, compliance workflows, and consumer awareness, and it reinforces the strategic value of carriers that can integrate regulatory clarity into their product design and customer communication.
Risk, Regulation, and the Pricing Environment
Insurance strategy in the marine sector cannot be separated from the risk and regulatory context in which it operates. Several developments from the current cycle highlight why 2026 planning must incorporate a forward view of compliance and pricing rather than a backward-looking assumption of stability.
One important structural reality is the limitation of homeowners policies for boat owners. According to guidance from the Texas Department of Insurance, most homeowners policies provide only limited coverage for boat damage—typically no more than 1,500 USD—and generally do not include liability. This gap creates a persistent need for separate boat policies and shapes how owners perceive the value of dedicated marine coverage. It also influences how carriers position bundled services, endorsements, and educational content to ensure that policyholders understand their exposure. In practice, this means that product design and customer messaging must address both asset protection and liability clarity, especially for owners who may assume their existing coverage is sufficient.
Boat Insurance Market
Premium pricing is another area where the market is showing meaningful variation. Industry market data indicates that average annual premiums for recreational boat insurance commonly range from 250 to 1,200 USD. While that range reflects differences in vessel type, usage, location, and coverage structure, it also underscores the sensitivity of affordability and policyholder retention to rate adjustments. In states with high coastal exposure, such as Florida, boaters have faced premium increases in the range of 15 to 25 percent due to reinsurance pressures and storm-related risks. These dynamics are not isolated; they are signals of a broader environment in which loss-cost expectations, reinsurance capacity, and regional risk concentration interact to shape pricing strategy. Carriers that can model these pressures with granularity will be better equipped to set rates that are both competitive and sustainable.
Regulatory mandates add another layer of strategic consideration. Requirements such as South Carolina's liability threshold for higher-horsepower watercraft illustrate how policy can expand the addressable market for certain coverage types while simultaneously raising the compliance bar for owners and insurers alike. For carriers, this creates opportunities to design products that align with minimum standards and to build customer journeys that simplify proof-of-coverage processes. For investors and strategic planners, it highlights the importance of monitoring legislative trends in states with significant boating activity, since regulatory change can quickly alter the competitive and operational landscape.
What the 2026 Outlook Means for Strategy
The convergence of steady top-line growth, concentrated competition, evolving regulation, and region-specific pricing pressures creates a market environment that rewards precision. Organizations that treat boat insurance as a generic ancillary line may find themselves outpaced by specialists who have built clearer value propositions for specific vessel categories, usage profiles, and local risk conditions. At the same time, the forecast trajectory suggests that the aggregate opportunity remains substantial, particularly for players who can balance growth ambition with disciplined underwriting.
Strategically, several themes merit attention. First, segmentation clarity is essential. The market's growth will not be evenly distributed across coverage types or vessel applications, and the ability to identify which subsegments are expanding fastest—and why—will inform product prioritization, channel investment, and pricing strategy. Second, geographic nuance matters. Regional dynamics ranging from coastal storm exposure to state-level liability mandates will continue to shape both demand and cost structures, making localized intelligence a critical input to expansion and pricing decisions. Third, competitive differentiation will increasingly depend on how well carriers integrate digital convenience, tailored coverage options, and regulatory responsiveness into a coherent customer experience. Scale remains important, but specialization and service design are proving to be powerful complements in a market where customer expectations and risk profiles are diversifying.
The full report extends these themes into detailed segmentation analysis, competitive benchmarking, and forward-looking scenario framing that can be directly applied to planning cycles. It is designed to support a range of strategic questions: where to allocate underwriting resources, how to position products in markets facing rate pressure, which competitive moves signal broader industry shifts, and how regulatory developments may reshape the risk landscape over the forecast horizon.
Begin the Conversation with Complete Intelligence
The boat insurance market is entering a phase in which strategic advantage will belong to organizations that can read the signals early and act with precision. The combination of a 5.85 percent CAGR, a market projected to approach 475.0 million USD by 2032, and a competitive field marked by both concentration and specialization creates a rich environment for informed decision-making. Yet the real value lies beneath the headline numbers—in the segmentation dynamics, the regulatory triggers, the pricing sensitivities, and the competitive maneuvers that will determine which organizations capture disproportionate value over the next several years.
This article provides the strategic framing, but the full report delivers the depth required to translate context into execution. It contains the segmentation structures, regional interpretations, competitive profiles, and forward-looking analysis that leadership teams need to build resilient 2026 strategies and beyond. For decision-makers ready to move from awareness to action, the complete market intelligence awaits. Accessing the full study will unlock the granular insights necessary to benchmark your position, stress-test your assumptions, and identify the highest-leverage moves for the forecast period.
For detailed analysis of this topic, please visit the official page: Boat Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


