



PW Consulting: Security Screening Market Hits $8.5B in 2025, Projects 7.8% CAGR Through 2032

Navigating the Security Screening Systems Market: Strategic Intelligence for 2026 and Beyond
The landscape of global security is undergoing a paradigm shift, driven by escalating threat vectors, technological breakthroughs in imaging and artificial intelligence, and an evolving regulatory environment. For executives, procurement leaders, and investors, the Security Screening Systems Market represents a critical nexus of defense, aviation, and public safety infrastructure. PW Consulting's latest comprehensive market research offers more than just data points; it provides a strategic roadmap for navigating the complexities of this sector through the forecast period of 2026 to 2032. This article outlines the strategic imperatives revealed by our analysis, highlighting why deep, actionable intelligence is essential for decision-making in the current fiscal year and beyond.
The market has demonstrated robust resilience and expansion over the past half-decade. Our historical analysis from 2020 through 2025 traces a trajectory of steady capitalization growth, reflecting increased global spending on infrastructure protection and modernization of legacy checkpoint technologies. As we project forward, the momentum continues, with 2026 marking a significant inflection point where strategic investments begin to compound. For 2026 enterprise decision-makers, understanding the magnitude of this growth is not merely an academic exercise but a prerequisite for capital allocation, supply chain planning, and competitive positioning.
Macro Market Trajectory and Value Drivers
The overarching narrative of the Security Screening Systems Market is one of sustained expansion. The total market revenue has climbed significantly since 2020, reflecting a compounded growth pattern that underscores the inelastic demand for security solutions in high-risk environments. By the end of the forecast horizon in 2032, the market is poised to reach a valuation that represents a substantial increase from the base year of 2025. This trajectory is underpinned by a forecasted Compound Annual Growth Rate (CAGR) of 7.8 percent, a metric that signals healthy, structural demand rather than transient spikes.
For strategic planners, this growth rate implies that the market is moving beyond a phase of pure replacement and into an era of capability enhancement. The transition from 2025 to 2026 alone suggests a meaningful increase in revenue potential, with the market size expanding into the range of billions of USD by the close of the decade. This expansion is not uniform; it is shaped by distinct technological shifts, regulatory mandates, and regional dynamics that our report deconstructs in granular detail. However, the macro view confirms that security screening is no longer a cost center but a value-driving component of operational efficiency and risk mitigation for aviation authorities, border agencies, and critical infrastructure operators.
Product and Application Dimensions
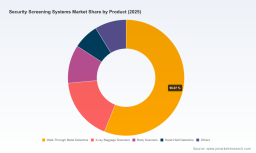
The market's complexity lies in its segmentation, where different product categories and application verticals respond to unique drivers. Our research delineates the revenue contributions across key hardware and software solutions, including walk-through metal detectors, X-ray baggage scanners, body scanners, hand-held detectors, and other specialized systems. The distribution of value among these segments reveals where innovation and procurement focus are concentrated. For instance, the prevalence of certain detection technologies highlights the ongoing balance between throughput efficiency, detection accuracy, and user experience.
Similarly, the application landscape is bifurcated between passenger screening, baggage and cargo screening, and vehicle and other inspection modalities. Each vertical presents distinct operational challenges. Passenger screening demands high throughput with minimal friction, driving the adoption of advanced imaging and non-intrusive technologies. Baggage and cargo screening, conversely, grapples with the volume and density of items, necessitating higher-resolution imaging and AI-assisted threat recognition. Vehicle and other inspection sectors often require ruggedized, mobile solutions capable of operating in diverse environments. Our report analyzes the interplay between these segments, helping clients identify where their products or services align with the highest growth opportunities and where cross-segment synergies might be leveraged.
Regional Dynamics and Market Structure
Geographically, the market spans a diverse array of regions, each with its own regulatory frameworks, threat profiles, and procurement cycles. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa each contribute to the global revenue pool, but their growth rates and dominant use cases vary significantly. In some regions, government-led infrastructure modernization programs are the primary catalyst, while in others, private sector adoption in venues such as stadiums, corporate campuses, and transportation hubs is accelerating. Our analysis maps these regional nuances, enabling clients to tailor their market entry or expansion strategies based on localized demand signals rather than relying on global averages.
The competitive structure of the market further informs strategic planning. The industry exhibits a moderate level of concentration, with the top three players capturing a specific share of total revenue and the top five firms accounting for a slightly larger portion. This structure suggests a market that is neither a monopoly nor a fragmented commodity space, but rather one where established players compete on technological differentiation, service ecosystems, and compliance capabilities. Understanding this concentration is vital for assessing barriers to entry, potential for consolidation, and the leverage that large buyers may possess in negotiations.
Competitive Landscape: Key Players and Strategic Moves
The battle for market share is being waged by a cadre of sophisticated technology companies that blend hardware engineering with software intelligence. Our report profiles the strategies and offerings of leading firms that define the competitive frontier.
Smiths Detection, headquartered in the United Kingdom, continues to set benchmarks in baggage, cargo, and vehicle inspection. Their HI-SCAN CT X-ray and SDX series scanners represent the integration of high-fidelity imaging with operational intelligence. A standout development in early 2026 is the deployment of their fully automated International Remote Baggage Screening System (IRBS), leveraging HI-SCAN 10080 XCT CT scanners between Incheon International Airport and the U.S. Customs and Border Protection. Operational since August 2025, this system integrates DICOS V3.0 and demonstrates how remote screening and data interoperability are redefining operational models, allowing for centralized threat assessment while maintaining physical separation between screening and adjudication.
OSI Systems, better known through its Rapiscan Systems brand in the United States, remains a powerhouse in non-intrusive inspection (NII) solutions. Their focus on high-throughput CT and X-ray capabilities for cargo, vehicle, and baggage screening positions them strongly in high-volume logistics and transport corridors. Recent contract awards in mid-2026, totaling significant value for cargo and vehicle inspection systems and services, as well as orders to support the deployment of non-intrusive inspection solutions, underscore the sustained demand for their core competencies. These wins highlight the reliability and scalability of their offerings in government and commercial contracts.
Leidos and Analogic Corporation represent a compelling convergence of enterprise software and imaging hardware. Leidos, with its Pro:Vision mmWave and AI-powered detection systems, addresses passenger and baggage screening for airports, borders, and critical infrastructure. The formation of a joint venture between Leidos and Analogic in April 2026 is a strategic milestone, combining Security Enterprise Solutions with advanced imaging technologies. This collaboration aims to deliver integrated security screening systems that bridge the gap between detection hardware and enterprise-level management, potentially offering end-to-end solutions that enhance operational coordination and data analytics.
Nuctech Company Limited from China continues to expand its footprint with advanced X-ray and CT screening systems for cargo, vehicle, and passenger inspection, increasingly integrating AI to improve detection rates and reduce false positives. CEIA S.p.A. of Italy maintains a strong position in walk-through and handheld metal detection, catering to airports, borders, and public venues with a focus on reliability and form factor. L3Harris Technologies, formerly L3, offers integrated detection and imaging systems tailored for airport and border passenger screening, leveraging its broader defense and technology heritage.
Meanwhile, newer approaches are reshaping the passenger experience. Evolv Technologies, based in the United States, has pioneered the Evolv Express AI-powered walk-through weapons and contraband detection system, deploying it in airports, schools, and critical infrastructure. This technology eliminates the traditional stop-and-wave paradigm, offering a seamless flow that aligns with modern expectations for speed and convenience. American Science and Engineering (AS&E) rounds out the competitive set with its expertise in non-intrusive inspection systems for cargo, vehicle, and parcel screening, providing specialized solutions for high-value asset protection and logistics security.
These competitive dynamics illustrate a market where differentiation is increasingly tied to software capabilities, data integration, and ecosystem partnerships. Firms that can offer not just hardware but also remote screening, AI-assisted analytics, and compliance with cross-border data protocols are gaining a strategic edge.
Regulatory and Technology Dynamics Shaping 2026
No strategic assessment of the Security Screening Systems Market is complete without a rigorous examination of the regulatory and technological forces that constrain and enable innovation. Our report integrates these dynamics into a cohesive view of market viability and risk.
Radiation safety standards remain a foundational constraint for systems utilizing ionizing radiation. The Radiation Safety Standard for personnel security screening systems using X-ray or gamma radiation, ANSI/HPS N43.17-2009, limits the dose per screening to 0.25 µSv (25 µrem) reference effective dose for general-use full-body security screening systems. Compliance with this standard is non-negotiable for manufacturers and operators, influencing system design and operational protocols. Similarly, the Radiation Safety Standard for millimeter wave security systems, defined by IEEE C95.1-2005, ensures safety levels with respect to human exposure to radio frequency electromagnetic fields, 3 kHz to 300 GHz. These technical standards shape the engineering landscape and affect the cost and timeline of product development.
On the funding and procurement side, the TSA FY 2026 budget allocates approximately $300 million for Computed Tomography (CT) checkpoint baggage systems (CPSS). This dedicated allocation signals a strong government push toward upgrading checkpoint infrastructure with CT-based solutions, which offer enhanced threat detection and the potential for reduced physical bag searches. For vendors and implementers, this budget information provides a window into the scale of available procurement opportunities and the priority assigned to CT technology.
Operational requirements for public venues also dictate market specifications. The DHS National Urban Security Technology Laboratory market survey of walk-through weapons screening systems for public venues requires systems to meet 28.3 to 32.3 inch passage width and 100 lb portal weight with support for up to 30 international standards. These specifications reflect the need for systems that are portable, adaptable, and compliant with a broad array of protocols, particularly relevant for temporary deployments or multi-site operators.
Security Screening Market
Furthermore, data handling and transmission protocols are becoming critical in an era of remote and automated screening. All data handling and transmission in automated remote baggage screening systems must comply with Korea's Personal Information Protection Act and U.S. CBP security and cybersecurity protocols. The IRBS deployment exemplifies the complexity of managing cross-jurisdictional data flows, where privacy laws and security mandates intersect. For technology providers, this means that cybersecurity, encryption, and regulatory compliance are no longer ancillary features but core components of the value proposition.
The Strategic Value of Our 2026 Market Research
In a market characterized by rapid technological evolution, regulatory nuance, and intense competition, superficial market summaries are insufficient for making high-stakes decisions. PW Consulting's Security Screening Systems Market research is designed to provide the depth and granularity that executives, strategists, and investors require to act with confidence in 2026 and throughout the forecast period.
Our report goes beyond high-level aggregates to deliver actionable intelligence across multiple dimensions. Readers gain access to a detailed examination of the market structure, including precise segmentation data that reveals how revenue is distributed across regions, product categories, and application verticals. We avoid the trap of aggregated generalizations by providing a clear view of where value is being created and how different segments are evolving. This allows clients to benchmark their position, identify white spaces, and anticipate shifts in demand.
The competitive analysis section offers deep dives into the strategies, product portfolios, and recent developments of key market participants. By tracking events such as contract awards, product deployments, joint ventures, and technological launches, we provide a real-time pulse on the competitive landscape. This intelligence helps clients assess the threat posed by rivals, identify potential partnership opportunities, and understand the strategic priorities of leading firms. For example, the joint venture between Leidos and Analogic or the remote screening deployment by Smiths Detection are not isolated news items; they are indicators of broader trends toward integration, automation, and cross-border operational models that will reshape the market.
Security Screening Systems Market
Moreover, our research contextualizes regulatory and technology dynamics within the broader market framework. We analyze how standards like ANSI/HPS N43.17-2009 and IEEE C95.1-2005 impact product design and market access, and how budget allocations like the TSA's $300 million for CT CPSS create procurement tailwinds. We also examine the implications of data privacy and cybersecurity requirements on system architecture and vendor selection. This holistic view enables clients to navigate compliance risks proactively and align their product development or procurement strategies with regulatory trajectories.
For investors, the report provides a clear assessment of market growth potential, competitive intensity, and the factors driving long-term value creation. The forecasted CAGR of 7.8 percent and the market's progression toward a multi-billion-dollar valuation by 2032 offer a backdrop for evaluating investment opportunities in hardware, software, services, and enabling technologies. For procurement and operations leaders, the research offers insights into emerging technologies, vendor capabilities, and best practices that can optimize screening efficiency, reduce operational costs, and enhance security outcomes.
Ultimately, the strategic value of this research lies in its ability to transform information into insight and insight into action. Whether you are expanding into new geographic markets, launching a next-generation screening solution, evaluating M&A targets, or optimizing an existing security infrastructure, the detailed intelligence provided in our report is tailored to support your specific objectives. We invite you to access the full source page to obtain the complete dataset, proprietary analysis, and executive summaries that will empower your decision-making in 2026 and beyond. The Security Screening Systems Market is evolving, and those who leverage comprehensive, forward-looking intelligence will be best positioned to lead.
For detailed analysis of this topic, please visit the official page: Security Screening Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


