



PW Consulting: Global Hydraulic Bolt Tensioner Market Hits $211.1M in 2025, Projecting 5.5% CAGR to 2032

Precision Under Pressure: Strategic Intelligence for the Hydraulic Bolt Tensioner Market 2026–2032
In an era where asset integrity, operational safety, and predictive maintenance define competitive advantage, the hydraulic bolt tensioner market stands at a critical inflection point. As heavy industry, energy infrastructure, and renewable power generation push equipment to higher reliability thresholds, controlled axial force application is no longer a technical afterthought—it is a strategic imperative. Our latest hydraulic bolt tensioner market research delivers a comprehensive, decision-ready intelligence framework designed specifically for executives, category managers, and engineering procurement leaders navigating the 2026–2032 horizon. This report bridges historical performance data with forward-looking market mechanics, offering a clear lens through which to calibrate capital allocation, supplier partnerships, and technology roadmaps.
The market has demonstrated consistent expansion over the past half-decade, reflecting a structural shift toward precision bolting solutions across both traditional energy and emerging clean-power sectors. Historical trajectories from 2020 through 2025 reveal steady revenue growth driven by infrastructure modernization, offshore operational complexity, and the industrial sector’s increasing reliance on standardized flange management. Building on this foundation, our forecast period maps a measured but resilient expansion pathway, with a five-year compound annual growth rate that underscores the market’s maturity while highlighting pockets of accelerated demand. By anchoring 2026 strategic planning in empirically validated sizing, procurement teams can move beyond speculative budgeting and align tender strategies, inventory positioning, and service-level agreements with actual consumption velocities. The research deliberately separates headline trajectory from localized execution variables, ensuring that decision-makers understand both the macro momentum and the operational levers that shape regional and application-specific procurement outcomes.
Decoding Market Architecture and Demand Drivers
Market growth is not uniform; it is engineered by intersecting technical requirements, environmental constraints, and cost optimization mandates. Our analysis dissects the structural layers that determine where demand concentrates, how product configurations diverge, and which operational variables dictate procurement timing. Across industrial ecosystems, the shift toward predictive maintenance and reduced unscheduled downtime has elevated hydraulic tensioning from a reactive repair tool to a standardized joint-integrity practice. This transition is particularly pronounced in sectors where flange leakage, bolt fatigue, or inconsistent preload directly impact safety certifications and operational continuity.
Application segmentation reveals how end-use environments shape product specification requirements and purchasing cycles. Traditional energy infrastructure continues to anchor baseline demand, while power generation and heavy industrial processing expand the addressable use case portfolio. Each vertical presents distinct procurement rhythms, technical validation criteria, and lifecycle cost considerations. For instance, offshore and subsea environments prioritize corrosion-resistant construction, seal integrity, and rapid deployment protocols, whereas onshore industrial and power generation settings often emphasize labor efficiency, repeatable tensioning cycles, and compliance documentation. The research maps these contextual differences without reducing them to static percentages, instead providing a qualitative and quantitative framework that helps procurement leaders anticipate specification drift, evaluate supplier capability matrices, and structure tender requirements that reflect actual field conditions rather than generic catalog descriptions.
Product Architecture and Engineering Divergence
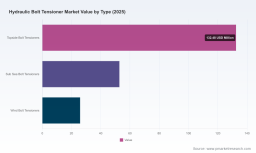
The tensioner product landscape is defined by the operational environment in which controlled bolt preload must be delivered. Topside configurations remain the volume backbone of the market, serving onshore facilities, processing plants, and surface-level energy infrastructure where accessibility, tool interchangeability, and standardized flange compatibility drive purchasing decisions. These systems prioritize modular bridge designs, broad bolt-size coverage, and compatibility with common ANSI, ASME, and API standards, enabling maintenance teams to standardize tooling across multiple joint configurations while minimizing inventory fragmentation.
Subsea tensioning represents a more specialized segment, where underwater pressure, saltwater corrosion, and restricted access fundamentally alter design priorities. Components engineered for submerged applications typically incorporate high-strength stainless steel construction, composite sealing systems, and quick-release mechanisms that balance deployment speed with long-term reliability. The premium associated with these environmental safeguards reflects the heightened risk profile of offshore operations and the cost of failure in inaccessible locations. Meanwhile, wind energy applications introduce a distinct engineering challenge: foundation and tower bolting in geographically dispersed, often remote locations where simultaneous multi-point preload and compact equipment footprints are essential. Single-stage and multi-stage hydraulic configurations have evolved to meet these constraints, enabling crews to apply consistent axial force across restricted work zones while minimizing manual handling and exposure time.
Understanding these architectural divergences is critical for procurement strategy. A tensioner selected for topside refinery maintenance may underperform in wind farm commissioning, just as a subsea-rated unit may introduce unnecessary cost and logistical complexity for onshore industrial use. Our research separates these product families by functional design logic, deployment context, and maintenance cycle expectations, giving buyers a structured approach to matching tooling portfolios with actual operational profiles rather than relying on generalized product categorization.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated supplier base, with a handful of established manufacturers holding meaningful share while a broader field of specialized and emerging players competes on engineering differentiation, regional responsiveness, and application-specific innovation. Leading-quadrant participants typically combine broad product portfolios with standardized compliance documentation, global distribution networks, and integrated pump-and-tensioner ecosystems that reduce procurement friction. These firms often anchor their positioning in repeatable quality assurance, interchangeable adapter systems, and documented preload accuracy, which resonates with buyers managing large asset portfolios and multi-site maintenance schedules.
Alongside these established players, supplementary manufacturers compete by targeting niche operational requirements, regional service coverage, or cost-optimized industrial configurations. Certain suppliers emphasize high-pressure axial force systems, pneumatic pump integration, and heavy-duty tooling for mining, steel, and continuous-process environments. Others differentiate through spring-return mechanisms, manual-return designs with overstroke prevention, or multi-stud tensioning solutions that reduce crew exposure and accelerate cycle times. These design choices are not merely technical features; they are procurement decision drivers that influence total cost of ownership, training requirements, and maintenance scheduling.
Recent industry activity reinforces the pace of capability expansion. Throughout 2025, multiple manufacturers updated technical documentation, expanded product catalogs, and published field-reliability guidance focused on load cell accuracy, pump output consistency, and subsea application performance. Independent wind-energy tooling introductions have also emerged, reflecting the sector’s ongoing need for specialized tensioning configurations suited to foundation and mast assembly environments. These developments signal a market where product refinement, documentation transparency, and application-specific troubleshooting resources are becoming competitive differentiators. For procurement leaders, this means supplier evaluation must extend beyond unit pricing to include technical support maturity, documentation currency, and the ability to adapt product recommendations to site-specific joint integrity requirements.
Regulatory, Cost, and Operational Dynamics Shaping 2026 Decisions
Market behavior is increasingly governed by the intersection of compliance expectations, material economics, and labor efficiency considerations. Standardization frameworks continue to influence product validation and acceptance criteria, with bolt evaluation protocols and yield-strength limits shaping how tensioning equipment is specified and audited. Buyers operating in regulated environments must ensure that selected tensioning systems align with documented axial force control requirements and that supplier documentation supports traceable compliance verification. This is particularly relevant for organizations managing multi-vendor maintenance programs or integrated asset-management contracts, where inconsistent tooling practices can complicate audit readiness and joint-integrity reporting.
Hydraulic Bolt Tensioner Market
Material and construction economics further differentiate cost structures across product families. Subsea and corrosion-intensive applications typically require high-strength stainless steel components and advanced sealing materials, which elevate baseline manufacturing costs relative to standard topside configurations. These material-driven cost premiums are justified by the operational risk profile of offshore and submerged environments, but they also require procurement teams to evaluate lifecycle cost rather than initial acquisition price alone. In parallel, labor exposure and cycle efficiency remain decisive factors in industrial and wind turbine maintenance contexts. Tooling designs that incorporate spring-return functionality, automatic retraction, or multi-stud capability reduce manual handling and streamline on-site workflows, which can materially affect service scheduling, crew safety metrics, and total maintenance cost over the equipment lifecycle.
For 2026 planning, these dynamics translate into a more deliberate procurement posture. Decision-makers must weigh specification fidelity against cost efficiency, evaluate whether premium configurations deliver measurable risk reduction in their actual operating environment, and determine how tooling standardization can reduce spare-parts complexity without compromising joint integrity. The market is no longer driven solely by equipment availability; it is shaped by how well procurement strategies align with compliance calendars, field labor constraints, and the long-term reliability expectations of critical infrastructure.
Report Architecture: What Decision-Makers Will Gain
This market research is structured to translate macroeconomic trajectory and competitive complexity into actionable procurement and strategy inputs. The report opens with a quantified market sizing framework that establishes baseline demand and forward growth expectations, then layers in segmentation logic that explains how product types, end-use environments, and regional operating conditions influence purchasing patterns. Rather than presenting raw splits as isolated figures, the analysis contextualizes each dimension within procurement decision-making, helping buyers understand where demand intensity concentrates and which variables justify specification adjustments.
A dedicated competitive profiling section maps the strategic posture of leading and supplementary manufacturers, highlighting portfolio breadth, engineering focus areas, and recent capability development activity. This enables procurement teams to benchmark supplier offerings against actual application requirements, evaluate differentiation claims with technical grounding, and construct vendor shortlists that reflect operational fit rather than marketing positioning alone. The report also includes a structured examination of market drivers, constraints, and dynamic cost factors, linking regulatory expectations, material considerations, and labor efficiency trends to purchasing and inventory strategy.
To support practical execution, the research integrates application-specific tensioning considerations, product-configuration guidance, and field-reliability themes that help operations and maintenance leaders align tooling selection with joint-integrity objectives. The output is designed for cross-functional use: strategic planning teams can leverage the growth trajectory and concentration insights for market-entry or investment assessment, procurement can use segmentation and supplier profiling to structure tenders and evaluate total cost of ownership, and engineering teams can reference the technical dynamics to validate specification choices against operational constraints. All detailed quantitative matrices, proprietary forecasting breakdowns, and deep-dive supplier benchmarks are reserved for the full report, ensuring that executive readers receive the strategic frame while retaining a clear path to complete, decision-grade intelligence.
Why 2026 Demands a More Disciplined Procurement Posture
As the hydraulic bolt tensioner market moves further into its forecast cycle, the margin for reactive purchasing continues to narrow. Demand growth is being shaped by a combination of infrastructure maturation, specialized offshore and wind-energy requirements, and the industrial sector’s ongoing push toward standardized, repeatable bolting practices. In this environment, organizations that approach procurement with a clear understanding of product architecture, supplier differentiation, and compliance-linked specification requirements will be better positioned to control total cost, reduce joint-integrity risk, and maintain operational continuity across maintenance cycles.
Industrial Belt Tensioner Market
This research provides the structural intelligence needed to make those decisions with confidence. By separating headline market momentum from the operational realities that govern specification, sourcing, and lifecycle cost, the report equips executives and procurement leaders with a planning framework that is both strategically oriented and execution-ready. The full study extends this foundation into detailed sizing tables, segmentation analysis, competitive benchmarking, and scenario-based procurement guidance—offering the depth required to convert market insight into precise 2026 action.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


