



PW Consulting: Lignin Products Market Hits $729.42M in 2025, Projected 4.28% CAGR to $978.1M by 2032

Unlocking the Potential of Lignin: Strategic Insights for the 2026 Market Landscape
The global transition toward a bio-based economy is no longer a theoretical concept; it is a market reality reshaping supply chains, product formulations, and competitive dynamics across multiple industries. At the forefront of this shift is the lignin value chain. Often dismissed as a byproduct of the pulp and paper industry, lignin has emerged as a versatile, renewable alternative to petrochemical-derived materials. However, realizing its full commercial potential requires more than just technological innovation; it demands precise market intelligence to navigate a complex landscape of regulatory hurdles, fragmented supply sources, and evolving application requirements.
Lignin Products Market
PW Consulting is pleased to introduce our comprehensive market research report on the Lignin Products Market. This study is designed specifically for strategic decision-makers who need to allocate capital, identify partnership opportunities, and mitigate risk in the 2026-2032 forecast period. By combining rigorous quantitative analysis with qualitative competitive profiling, this report serves as an essential compass for navigating the next wave of industrial bioproducts.
Market Trajectory and Growth Catalysts
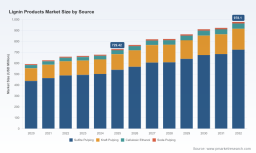
The lignin market has demonstrated steady resilience and growth over the past half-decade, driven by increasing demand for sustainable industrial inputs. Our analysis tracks the market value from 2020 through the base year of 2025, projecting a continued upward trend into the next decade. In 2020, the global market was valued at approximately 591 million USD. By 2025, this figure has risen to an estimated 729 million USD, reflecting a consistent trajectory of adoption across key end-user sectors.
Looking ahead, the strategic opportunity lies in the forecasted growth window. The market is expected to expand from its 2026 starting point of roughly 767 million USD to nearly 978 million USD by 2032. This projection implies a Compound Annual Growth Rate (CAGR) of 4.28 percent over the forecast period. While this growth rate may appear moderate at first glance, it is essential to contextualize it within the broader chemical industry, where volume growth for traditional bulk chemicals often lags behind specialty bioproducts. The steady CAGR indicates a maturing market that is transitioning from niche experimentation to mainstream commercial viability.
Several underlying drivers are fueling this expansion. First, the regulatory push toward carbon reduction and the circular economy is compelling industries to seek renewable feedstocks. Lignin, as the second most abundant biopolymer on Earth, offers a scalable solution for replacing fossil-based phenols, polyols, and dispersants. Second, technological advancements in separation and purification processes are lowering the cost barrier, making lignin-derived products more competitive against incumbent synthetic alternatives. Third, specific application sectors, such as agriculture and construction, are increasingly recognizing the functional benefits of lignin-based additives, ranging from improved feed efficiency to enhanced concrete setting properties.
Competitive Landscape and Strategic Positioning
Understanding the competitive dynamics is critical for any firm looking to enter or expand within this market. The lignin value chain is characterized by a mix of established pulp and paper giants leveraging their existing biomass access and specialized players focusing on high-value application development. Our report provides a detailed profiling of key market participants who are defining the standard for quality and innovation.
In Northern Europe, companies like Borregaard LignoTech and Domsjö Fabriker represent the legacy strength of the sulfite pulping industry. These organizations have long mastered the extraction and refinement of lignosulfonates. Borregaard, headquartered in Sarpsborg, Norway, continues to lead in specialized biopolymers and lignosulfonates, particularly within agriculture for animal feed binders and organic amendments. Their recent regulatory re-authorization for use in animal feed within the EU in February 2024 underscores the importance of compliance in maintaining market access. Similarly, Domsjö Fabriker in Sweden focuses on sulfite lignin products for agricultural and construction uses, leveraging local infrastructure to secure feedstock continuity.
Finnish competitors are also aggressively positioning themselves through differentiation. UPM Biochemicals has carved a niche in lignin-derived renewable functional fillers. Their collaboration with Nokian Tyres to introduce a concept tire using UPM BioMotion Renewable Functional Fillers highlights the potential for lignin to penetrate high-performance rubber applications. Meanwhile, Stora Enso produces kraft lignin products aimed at wood panel resins and feed binders, utilizing their extensive forestry resources to secure a loyal downstream customer base.
In the Netherlands, LignoStar International B.V. operates as a specialized marketer and seller, focusing on calcium lignosulfonates for animal feed pellet binders and organic amendments. This business model emphasizes distribution agility and technical service support rather than heavy vertical integration. Conversely, the Asian market is seeing the rise of integrated agro-chemical players. Green Agrochem, based in Beijing, operates divisions focused on lignin and lignosulfonates for fertilizer binders, pesticide dispersants, and animal feed applications. Their recent release of technical data sheets for magnesium lignosulfonate in June 2025 demonstrates a focus on product specification and market promotion to capture industrial and agricultural demand.
A critical element of our competitive analysis involves assessing market concentration. The report details the market share distribution among the top players, revealing the level of consolidation and the bargaining power held by key suppliers. This data is vital for understanding pricing dynamics and supply security risks.
Segmentation Analysis: Sources, Products, and Applications
To truly grasp where value is created, one must dissect the market along multiple dimensions. Our report segments the market by source, product type, application, and region, providing a granular view of revenue contributions without relying on broad generalizations.
By Source: The supply of lignin is intrinsically linked to pulping processes. The report quantifies the revenue contribution from Sulfite Pulping, Kraft Pulping, Cellulosic Ethanol, and Soda Pulping. Each source yields lignin with distinct chemical properties and impurity profiles, which in turn dictates suitability for specific downstream applications. For instance, sulfite-derived lignosulfonates are historically dominant in dispersant and binder applications, while kraft lignin is gaining traction in resin formulations and carbon fiber precursors. The analysis highlights which source types are driving revenue growth and where future capacity investments are likely to concentrate.
By Product: The product landscape is primarily divided into Lignosulfonate, Kraft Lignin, and Other Product Types. Lignosulfonates continue to command a significant share of market revenue, driven by their established use across multiple industries. However, the report also tracks the growing revenue potential of specialized kraft lignin derivatives as purification costs decline. The differentiation between commodity-grade and specialty-grade lignin is a key theme, as margins vary significantly between bulk dispersants and high-performance functional fillers.
Lignin and Lignin-Based Products Market
By Application: Demand is driven by diverse end-use sectors including Dispersant, Concrete Additive, and Other Applications. The construction industry utilizes lignin-based additives to improve workability and reduce water content in concrete mixes. In the agricultural sector, lignin serves as a binder in animal feed pellets, which reduces pelleting energy use and improves feed conversion efficiency through better pellet durability. Additionally, lignin acts as a dispersant in fertilizer formulations to ensure uniform nutrient distribution. Our analysis breaks down the relative importance of these applications based on their contribution to total market revenue, helping clients identify the most profitable entry points.
By Region: Geographic revenue distribution is another critical component. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Regional analysis accounts for differences in pulp industry maturity, regulatory environments, and local demand for bio-based materials. For example, European markets often prioritize regulatory compliance and sustainability certifications, while Asian markets may focus on cost-effective industrial scale-up. Understanding these regional nuances allows for tailored market entry strategies.
Industry Dynamics: Regulations, Standards, and Innovation
The lignin market does not operate in a vacuum. A significant portion of our report is dedicated to the external dynamics that shape market behavior, including regulatory frameworks and technological breakthroughs.
Regulatory Environment: Compliance is a gatekeeper in key application segments. In the United States, lignin sulfonate is included on the National List as a synthetic substance allowed for use in organic production under the USDA AMS National Organic Program Document. This designation allows its use as a plant or soil amendment for dust suppression and as a chelating agent in crop production, opening access to the premium organic agriculture sector. In Europe, regulatory approvals have been a focal point. The re-authorization of lignin for use in animal feed within the EU, highlighted by developments involving Borregaard, removes a potential barrier to entry. Furthermore, Sappi Europe gained feed safety certification for lignin-based animal feed applications in October 2024, setting a benchmark for quality and safety that competitors must meet to compete in this high-value segment.
Technological Innovation: The pipeline for new lignin applications is expanding. A notable development is the operation of the LigniOx oxidation process demo plant, which started in January 2026 at the Metsä Fibre Äänekoski pulp mill. Capable of producing up to 2 tons of oxidized lignin per day, this pilot plant represents a step toward commercializing tailored lignin chemistry. Such innovations could unlock new performance characteristics, such as improved solubility or reactivity, which are essential for penetrating more demanding industrial applications like advanced materials or biofuels.
These dynamics create a shifting landscape where regulatory milestones and process innovations can accelerate adoption timelines or alter competitive positioning overnight. Our report synthesizes these events to provide a forward-looking view of market readiness and risk factors.
Strategic Value for 2026 Decision-Making
Why is this report essential for your strategic planning in 2026? The lignin market is at an inflection point where the gap between potential and realization is narrowing, but the path is still complex. Decision-makers need more than top-line numbers; they need actionable intelligence that connects market size to competitive reality.
First, the report provides a robust baseline for investment appraisal. By quantifying the revenue contribution of different sources, products, and applications, companies can prioritize projects that align with high-growth segments. Whether you are considering vertical integration into pulping processes or developing downstream formulation technologies, the segmentation data allows for scenario modeling based on realistic demand forecasts.
Second, the competitive profiling offers context for partnership and M&A strategies. Knowing who holds the market share, who is investing in R&D, and who has secured critical regulatory approvals allows you to identify potential allies or threats. For instance, understanding the specific capabilities of players like Green Agrochem in the fertilizer binder space or UPM in functional fillers can inform supply chain diversification or product differentiation strategies.
Third, the analysis of industry dynamics helps in risk management. Regulatory changes can quickly alter the viability of certain applications. By tracking certifications like feed safety standards and organic compliance, you can anticipate shifts in demand and adjust your product portfolio accordingly. Additionally, monitoring pilot plant operations and technological demonstrations provides early signals of future cost structures and performance capabilities that could disrupt current market equilibriums.
Conclusion
The Lignin Products Market offers a compelling value proposition for companies seeking to align with sustainability goals while capturing new revenue streams. However, success requires navigating a landscape defined by diverse feedstock sources, varied product specifications, and a competitive mix of integrated giants and specialized innovators. PW Consulting's market research report provides the depth and clarity needed to make informed decisions in this evolving environment.
While this overview highlights the strategic framework and key market drivers, it only scratches the surface of the comprehensive intelligence available. The full report contains detailed segmentation breakdowns, competitor analysis matrices, and granular data on regional revenue distributions that are essential for tactical execution. We invite you to access the complete study to gain the full picture of market opportunities and competitive dynamics. Discover how your organization can leverage the growing demand for lignin products to drive sustainable growth and secure a competitive advantage in the bio-based economy.
For detailed analysis of this topic, please visit the official page: Lignin Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


