



PW Consulting: Road Transport Refrigeration Equipment Market Hits $4.48 Billion in 2025, Growing at 5.8% CAGR to 2032

Strategic Cold Chain: Navigating the Road Transport Refrigeration Equipment Market from 2026 Onward
The global logistics infrastructure underpinning perishable goods, pharmaceuticals, and temperature-sensitive industrial products relies fundamentally on the reliability of road transport refrigeration equipment. As supply chains grow more complex and regulatory frameworks tighten, the market for transport refrigeration units has evolved from a commodity hardware sector into a strategic battleground defined by electrification, emissions compliance, and operational efficiency. Our recently published market research offers a definitive lens through which organizations can assess the structural shifts reshaping this industry. The findings provide a critical framework for decision-makers who must allocate capital, plan fleet transitions, and position themselves competitively through 2032.
The Trajectory of Growth and Capital Allocation
The sector has demonstrated consistent resilience through the early twenty-first decade, reflecting the indispensable nature of temperature-controlled logistics. Historical revenue data from 2020 through 2025 reveals a steady expansion trajectory, with the global market climbing from approximately 3.38 billion USD to 4.48 billion USD over that five-year window. This upward momentum is not merely a recovery from prior disruptions but a structural expansion driven by increased cold chain outsourcing, cross-border perishable trade, and stricter food safety mandates worldwide.
Looking forward, the forecast period spanning 2026 to 2032 projects the market to approach 6.65 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate of 5.8 percent, signaling a sustained, moderate expansion rather than a speculative boom. For strategic planners, this CAGR represents a reliable baseline for capacity planning, sales pipeline modeling, and investment horizon alignment. The forecast accounts for both organic demand growth and the technological substitution effects expected as legacy diesel fleets face increasing pressure from zero-emission mandates. The revenue curve suggests that while volume will increase, the margin dynamics will diverge significantly between traditional mechanical units and next-generation electric platforms, making operational cost modeling an essential component of any go-to-market strategy.
Regulatory Dynamics and the Electrification Imperative
The regulatory environment has emerged as the single most disruptive force shaping procurement strategies and product roadmaps. The California Air Resources Board has taken a pioneering role, implementing amendments that effectively dictate the pace of technological transition across the United States and influencing global standards through trade and manufacturing alignment. Under the TRU ATCM amendments, newly manufactured truck and trailer refrigeration units must now utilize refrigerants with a global warming potential of 2,200 or lower, or operate without refrigerant entirely. Furthermore, model-year 2023 and newer units must meet stricter particulate standards, raising the bar for emissions compliance across the board.
These mandates carry hard deadlines that require immediate fleet planning. As of December 31, 2025, truck TRU fleets operating in California must achieve a 45 percent zero-emission composition, with the threshold rising to 60 percent by December 31, 2026. The U.S. Environmental Protection Agency granted a partial waiver of federal preemption for these zero-emission requirements in January 2025, simultaneously authorizing the state to enforce the remainder of the rule. This creates a de facto compliance cascade: manufacturers and operators who fail to prepare for the 2026 threshold will face mounting operational fees, registration restrictions, and mandatory reporting burdens. The economic calculus of compliance is shifting from a peripheral concern to a core component of total cost of ownership analysis.
Energy cost differentials further accelerate the incentive to transition. Electric transport refrigeration units consume approximately 8.1 kW per hour, whereas traditional diesel units burn roughly 0.8 gallons of diesel per hour. The resulting average hourly savings of 1.36 USD may appear modest on a per-unit basis, but when scaled across large fleets and factoring in maintenance reductions, the cumulative impact on operating margins becomes substantial. These operational economics must be weighed against the higher upfront capital expenditure of electric platforms and the infrastructure requirements for charging depots, making a phased transition strategy essential for fleet managers.
Competitive Arena and Strategic Positioning
The market exhibits moderate concentration, with the top three players commanding approximately 45 percent of global revenue and the top five consolidating around 65 percent. This structure indicates a competitive landscape where dominant incumbents hold significant sway over pricing, technology standards, and dealer networks, while leaving meaningful room for regional specialists and innovation-driven challengers to capture niche segments. The presence of established multinational manufacturers alongside agile regional players creates a dynamic environment where partnerships, aftermarket service quality, and local regulatory expertise often determine winning positions as much as hardware specifications do.
Road Transport Refrigeration Equipment Market
Thermo King, headquartered in Wood Dale, Illinois, continues to broaden its portfolio across diesel, hybrid, and all-electric transport refrigeration units for trucks, trailers, and vans. Its July 2025 introduction of the V-520 nose-mount unit for small to medium box trucks demonstrates a focused push into segments requiring precise temperature control with compact footprint constraints. Carrier Transicold, based in Minneapolis, maintains a strong position with diesel-powered and electric refrigeration units and integrated cooling systems for road transport. Its Vector 8811MT refrigeration unit for center-divide trailers, also launched in mid-2025, emphasizes reduced maintenance intervals and lower operating costs, directly addressing the total cost of ownership concerns that fleet operators increasingly prioritize.
In Asia, Guchen Thermo has established a strong manufacturing footprint in China, producing diesel, electric, and battery-powered transport refrigeration units tailored for medium and heavy trucks. Its growth trajectory reflects the broader expansion of cold chain logistics in developing economies and the increasing domestic demand for temperature-controlled freight. Zanotti, an Italy-based specialist now operating as a Daikin Industries subsidiary, focuses on refrigerated van and truck refrigeration systems and conversions, leveraging its integration with a global refrigerant and HVAC technology leader to advance low-GWP and zero-emission solutions. Kingtec Group, with headquarters in the United States and global operations, manufactures transport refrigeration and cold storage solutions for trailers, trucks, and recreational vehicles, expanding its addressable market beyond traditional freight into adjacent mobile cooling segments. Hubbard Products Ltd, based in the United Kingdom, serves as a supplier and innovator of commercial and transport refrigeration equipment, bringing specialized engineering capabilities and a strong service network to the European and export markets.
Segment Structure and Demand Drivers
The product landscape bifurcates primarily around temperature control complexity. Single temperature units continue to represent the dominant share of revenue, driven by the extensive volume of dedicated cold-chain and frozen logistics applications where simplicity, lower cost, and proven reliability are paramount. Multi-temperature units, while representing a smaller overall share, deliver disproportionate value in mixed-load operations where a single trailer must simultaneously serve compartments at different thermal setpoints. The flexibility of multi-temperature configurations supports consolidated shipping, reduces empty miles, and appeals to operators managing diverse SKU portfolios, particularly in regional distribution and food service supply chains.
Trailer Refrigeration System Market
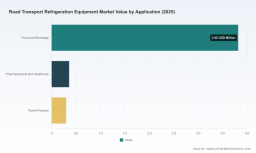
Application-wise, the food and beverage sector remains the overwhelming anchor of demand, reflecting the relentless global consumption of perishable goods and the regulatory and consumer-driven requirements for unbroken cold chains from farm to fork. Pharmaceutical and healthcare applications, while commanding a smaller revenue share, represent a high-value niche where temperature excursions carry severe regulatory and patient safety consequences. This segment demands stricter validation protocols, more sophisticated monitoring integration, and higher willingness to pay for reliability. Floral products constitute a specialized application where short transit windows, seasonal volatility, and precise humidity and temperature control combine to create a demanding operational environment that tests the precision and durability of transport refrigeration systems.
Material Volatility and Operational Realities
Beyond regulatory and competitive pressures, the industry faces ongoing supply chain friction. Steel components used in TRU housings and structural elements have experienced persistent volatility due to fluctuations in global metal markets. These input cost swings directly affect manufacturing margins and delivery lead times, requiring procurement teams to adopt hedging strategies, long-term supplier agreements, or design-for-manufacturing adjustments that reduce material intensity without compromising durability. As the market expands toward 2032, manufacturers that can stabilize their supply base while maintaining quality standards will hold a distinct advantage in a price-sensitive but compliance-driven environment.
The release of the first-ever report on transport refrigeration by the North American Council for Freight Efficiency in late 2024 marked a significant step toward establishing industry-wide benchmarks on efficiency and performance. This kind of third-party benchmarking creates transparency that benefits operators evaluating competing units and pushes manufacturers to demonstrate verifiable performance rather than relying solely on specifications. It also gives fleet managers the data needed to build internal business cases for fleet renewal programs and to compare total cost of ownership across diesel, electric, and hybrid platforms under real-world operating conditions.
Inside the Road Transport Refrigeration Equipment Market Research
Our newly released study goes far beyond top-line market sizing. It delivers a granular examination of the forces that will shape procurement, manufacturing, and sales strategies through the end of the decade. The research unpacks the compliance timeline implications of California's TRU ATCM and evaluates how the partial EPA waiver alters the enforcement landscape for facilities and operators. It maps the competitive positioning of incumbent manufacturers, analyzing product launch cadence, technology roadmaps, and the strategic significance of recent introductions such as the V-520 and Vector 8811MT within their respective target segments.
The report also dissects the structural balance between single temperature and multi-temperature units, identifying where design simplification converges with cost pressures and where multi-zone flexibility drives premium pricing in mixed-load logistics. It examines application-level demand patterns across food and beverage, pharmaceutical and healthcare, and floral products, revealing how risk tolerance, validation requirements, and operational tempo differ across these verticals and how those differences translate into pricing power and service expectations. Supply-side dynamics are explored in detail, including the impact of steel price volatility on manufacturing economics and the infrastructure and charging considerations that determine the pace at which electric TRUs can realistically scale.
Finally, the study integrates the latest regulatory events, including the June 2025 CARB implementation update and FAQ that detail compliance requirements for facilities and operators, the enforcement guidance authorizing operating fees, registration requirements, and reporting for all TRUs, and the broader efficiency benchmarking that is reshaping procurement evaluation criteria. These elements are woven into scenario-based frameworks that allow decision-makers to test their strategies against alternative compliance timelines, energy price trajectories, and fleet renewal cadences.
Strategic Imperative for 2026 Decision-Makers
For executives, procurement leaders, and strategic planners, the window between now and 2026 represents a critical inflection point. The 5.8 percent CAGR provides a reliable backdrop for growth planning, but it is the intersection of regulation, electrification economics, and competitive intensity that will separate leaders from laggards. Organizations that treat zero-emission compliance as a distant checkbox risk abrupt cost shocks and operational disruptions. Those that integrate the 2025 and 2026 California thresholds into multi-year fleet planning, evaluate total cost of ownership across electric and diesel platforms using real hourly savings data, and align product sourcing with the capabilities of manufacturers who have demonstrated recent innovation velocity will secure a durable competitive advantage.
The full report provides the detailed segmentation analysis, regional revenue breakdowns, competitive financial proxies, scenario modeling, and actionable recommendations necessary to convert these macro insights into executable strategy. Readers seeking to validate internal assumptions, benchmark procurement options, or build investment cases for fleet modernization should access the complete market intelligence to inform their 2026 and beyond planning with precision.
For detailed analysis of this topic, please visit the official page: Road Transport Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


