



PW Consulting Report: Manual Motor Starters Market Hits $630M in 2025, Projected 4.5% CAGR Through 2032

Navigating the Next Decade: Strategic Insights into the Global Manual Motor Starters Market (2026-2032)
The industrial landscape is undergoing a profound transformation, driven by the dual engines of automation and electrification. At the heart of this shift lies the fundamental infrastructure of motor control. For enterprise decision-makers, understanding the trajectory of the Manual Motor Starters Market is not merely an exercise in supply chain management; it is a strategic imperative that influences capital expenditure planning, safety compliance, and operational resilience. PW Consulting is proud to introduce our latest comprehensive market research study, designed to equip leadership teams with the actionable intelligence needed to thrive in the forecast period of 2026 through 2032.
This report serves as a critical navigational tool for stakeholders ranging from procurement directors to strategic planners. By analyzing historical performance from 2020 to 2025 and projecting forward, we uncover the underlying currents shaping the industry. The market, valued at approximately 630.0 Million USD in the base year of 2025, is poised for steady expansion. Our forecast models indicate a trajectory moving toward 857.0 Million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5 percent, signaling a mature yet consistently evolving sector where reliability and compliance drive demand rather than volatile speculation.
For organizations operating within or alongside the industrial manufacturing, oil and gas, water management, and mining sectors, these figures represent more than just top-line revenue. They reflect the ongoing replacement cycles of aging infrastructure, the integration of new safety standards, and the increasing complexity of motor protection requirements. This introduction provides a high-level overview of the strategic landscape, but the full depth of this intelligence is contained within the full report. The following analysis highlights the key themes our research unpacks in detail.
Macroeconomic Trajectory and Market Stability
The Manual Motor Starters Market has demonstrated remarkable resilience over the past five years. From 2020 to 2025, the market navigated global supply chain disruptions and economic fluctuations while maintaining a positive growth curve. The jump from 582.19 Million USD in 2024 to 630.0 Million USD in 2025 highlights a period of recovery and accelerated adoption. As we look toward 2026, the market is expected to reach 659.77 Million USD, setting the stage for a decade of incremental but significant growth.
This stability is crucial for long-term planning. Unlike high-volatility technology sectors, the demand for manual motor starters is tied to fundamental industrial output. The forecast period suggests that while the percentage growth may not be explosive, the absolute value addition is substantial. Companies that align their inventory and product development strategies with this steady 4.5 percent CAGR can optimize cash flow and reduce the risk of overstocking or undercapacity. However, realizing these benefits requires a nuanced understanding of where the growth is originating, which varies significantly by technology type and application vertical.
Manual Motor Starters Market
Segmentation Dynamics: Type and Application
A superficial view of the market hides the complex interplay between different product types and end-use applications. Our research dives deep into these segmentation splits to reveal where the highest value opportunities lie. The market is broadly categorized by technology, with AC Manual Motor Starters continuing to dominate the revenue share due to their widespread use in standard industrial power systems. However, the nuances within DC and other types offer specific niches for specialized engineering firms.
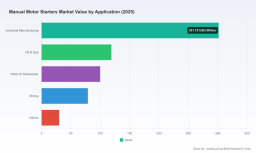
Similarly, the application landscape is diverse. Industrial manufacturing remains a primary driver, reflecting the need for cost-effective motor control in high-volume environments. Yet, sectors such as Oil and Gas and Water and Wastewater are critical growth engines due to stringent safety regulations and the harsh operating conditions that require robust starter solutions. Mining operations also contribute a significant portion of demand, particularly in regions undergoing infrastructure development.
Understanding the revenue contribution of each segment is vital for targeting. For instance, knowing which application vertical is expanding fastest can help manufacturers tailor their sales strategies and technical support teams. However, the specific percentage allocations and exact valuation figures for each region and application are proprietary data points that require the full report to access. This level of granularity allows competitors to benchmark their performance against the market average and identify untapped potential in specific verticals.
Regional Landscape and Distribution Channels
Geography plays a pivotal role in market dynamics. The global footprint of manual motor starters is uneven, reflecting the varying stages of industrialization and infrastructure investment across continents. Our analysis covers key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of challenges and opportunities, from regulatory compliance in Europe to cost-sensitive competition in Asia Pacific.
Motor Control Centers Mcc Market
Europe, for example, often leads in terms of advanced safety standards and premium product adoption, while other regions may prioritize volume and affordability. The distribution of market revenue across these geographies influences where companies should focus their marketing spend and logistical hubs. Supply chain localization is becoming increasingly important as trade policies shift and customers demand faster delivery times.
Our report provides a detailed breakdown of regional market sizes and growth rates. This information is essential for multinational corporations deciding on regional expansion strategies or local distributors looking to partner with global brands. The specific revenue values and growth contributions for each geographic zone are detailed within the full study, enabling precise market entry planning without the guesswork.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate level of concentration, with the top three players holding approximately 35.5 percent of the market share, while the top five control around 48.2 percent. This structure indicates a competitive environment where dominant players coexist with agile regional specialists. Understanding the strategies of these key competitors is essential for maintaining market position.
Leading global entities such as ABB, headquartered in Zurich, continue to strengthen their portfolio with specific series like MS116 and MS132, focusing on compact units that integrate protection and control. Schneider Electric, based in France, maintains a strong presence with the TeSys Deca GV2 and GV3 series, recently updating their catalog with TeSys Deca Advanced solutions in late 2025. Eaton, from Dublin, offers robust options like the PKZM and Cutler-Hammer B100 series, catering to diverse machinery control needs.
Siemens remains a key player with their 3RV2 series, serving the high-standard European and global markets. Meanwhile, specialized players are carving out niches. NOARK Electric, based in California, recently expanded their offering with the Ex9S80 Manual Motor Starter in mid-2025, emphasizing built-in fault indication. Fuji Electric in Tokyo continues to innovate with their Duo Series, while Appleton Electric, part of Emerson in Illinois, focuses on factory-sealed starters for hazardous locations. LS Electric in South Korea contributes with their Metasol MMS series, highlighting the global nature of this supply chain.
Competitive strategy in this market is not just about price. It is about compliance, reliability, and product features. Companies must navigate specifications such as short-circuit breaking capacity up to 100 kA at 400 VAC. Failure to meet these technical benchmarks can disqualify a product from key tenders. Our analysis examines the recent developments and product launches of these key companies to identify trends in innovation and market share shifts. The full report details the specific strategic moves and product portfolios that are defining the competitive edge in 2026.
Regulatory Environment and Technical Standards
Compliance is a non-negotiable aspect of the manual motor starter business. These electromechanical devices serve as the first line of defense for manual isolation, control, and overcurrent protection. They must adhere to rigorous international standards, including IEC and UL certifications. The regulatory landscape is tightening, particularly in hazardous environments.
For instance, starters designed for use in hazardous locations, such as Class I, Division 1 and 2 areas, require specific factory-sealed designs to prevent ignition sources. This creates a barrier to entry for lower-quality manufacturers and rewards established brands with proven certification histories. Furthermore, the average selling price of industrial-grade manual motor starters typically ranges from 150 to 450 USD, depending on current ratings between 10A and 100A and the complexity of protection features.
This pricing structure reflects the cost of compliance and engineering quality. Procurement teams must balance budget constraints with the inherent risks of non-compliance. Our research evaluates how regulatory changes are impacting product design and pricing strategies across the industry. We analyze the compliance requirements that are becoming key differentiators in procurement bids. Detailed regulatory impact assessments for specific regions and application types are included in the comprehensive study.
Investment and Procurement Outlook for 2026
As organizations move into the 2026 fiscal year, capital allocation decisions must be informed by data. The forecast growth to 768.22 Million USD by 2030 suggests a sustained demand environment. For procurement leaders, this means securing supply chains early to mitigate potential shortages or lead time extensions. For manufacturers, it means scaling production capabilities in line with the 4.3 percent to 4.5 percent growth corridors identified in our models.
The period from 2026 to 2032 will likely see consolidation among smaller players and increased investment in product features that enhance safety and diagnostics. Companies that adapt to these trends will capture greater market share. Those that rely on legacy designs without adapting to newer safety standards risk obsolescence.
Strategic planning also involves understanding the cyclical nature of the industries served. While manufacturing may fluctuate with economic cycles, utilities and water management often provide stable, recurring revenue. A diversified portfolio approach is recommended for market players. Our report provides the scenario planning tools necessary to model revenue under different economic conditions.
Why This Report is Essential for Decision Makers
In an era of information overload, clarity is the most valuable commodity. This report cuts through the noise to provide verified data, expert analysis, and forward-looking insights. It is not just a collection of numbers; it is a strategic framework for understanding the Manual Motor Starters Market.
By utilizing this research, your organization can:
- Benchmark your internal forecasts against independent market projections for the 2026-2032 period.
- Identify high-growth segments and regions before competitors do.
- Understand the competitive moves of key players like ABB, Schneider Electric, and Eaton to anticipate market shifts.
- Navigate regulatory complexities with confidence, ensuring product compliance and market access.
- Optimize supply chain strategies based on regional demand nuances and historical performance data from 2020 to 2025.
The market size data provided in the introduction offers a glimpse into the potential, but the actionable intelligence lies in the segmentation, competitive analysis, and regional breakdowns that are fully detailed in our complete study. The specific revenue splits by type, application, and region, along with the in-depth company profiles and recent development timelines, are critical for forming a precise strategy.
Access to the full report unlocks the detailed segmentation splits, such as the specific contributions of AC versus DC starters and the exact market valuation for industrial manufacturing versus other applications. It also provides the granular regional data necessary for local market planning. In a market projected to reach 857.0 Million USD by 2032, knowing exactly where to focus resources is the difference between average performance and market leadership.
Conclusion
The Manual Motor Starters Market offers a landscape of steady opportunity for those equipped with the right intelligence. As the industry moves past the base year of 2025 and into the forecast horizon, the convergence of regulatory pressure, technological refinement, and industrial demand will define the winners. PW Consulting's latest research provides the lens through which to view this future. We invite stakeholders to leverage this comprehensive analysis to drive informed decision-making and secure a competitive advantage in the years to come.
For those ready to transform data into strategy, the full market intelligence report is available for review. Engage with our detailed findings to align your organizational roadmap with the definitive market trajectory.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


