



PW Consulting: Hand Trucks Market Hits USD 1,091M in 2025, Projected 3.85% CAGR Through 2032

Strategic Intelligence Report: The Hand Trucks Market 2026-2032 Outlook
Executive Overview: Navigating a Maturing Sector
The material handling sector stands at a critical juncture as we move through 2026. While often perceived as a commodity category, the hand trucks market represents a complex interplay of material costs, regulatory shifts, and evolving labor dynamics. For enterprise leaders, supply chain managers, and strategic planners, understanding the trajectory of this market is not merely about procurement—it is about securing operational resilience.
This analysis serves as an introduction to the PW Consulting latest comprehensive study on the Hand Trucks Market. The research is designed to equip decision-makers with the granular intelligence required to navigate the forecast period from 2026 to 2032. By examining historical performance trends and projecting future growth vectors, we provide a roadmap for capitalizing on market opportunities while mitigating exposure to volatile input costs and trade policy changes.
Our methodology combines rigorous primary research with advanced modeling techniques to ensure that the insights provided are actionable. In an environment where margin pressure is high and supply chain disruptions remain a constant threat, access to precise market intelligence is a competitive differentiator.
Market Trajectory and Economic Indicators
The historical data reveals a sector that has demonstrated resilience despite macroeconomic headwinds. Between 2020 and 2025, the global market for hand trucks navigated significant fluctuations in demand and supply chain stability. Starting from a base of approximately 935.5 million USD in 2020, the market exhibited a clear upward trajectory, reaching a valuation of 1091.0 million USD by 2025. This growth underscores the essential nature of manual material handling equipment across various industries.
Looking toward the forecast horizon, the momentum is projected to continue, albeit at a measured pace reflective of a mature industry. The market is anticipated to grow from 1167.27 million USD in 2026 to 1390.0 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 3.85 percent over the forecast period. While this growth rate may appear moderate compared to high-tech sectors, it represents substantial volume in absolute terms for manufacturers and investors focused on steady returns and market share consolidation.
It is important for stakeholders to interpret these figures within the context of broader economic conditions. The growth is not uniform across all timelines; there are expected variances as the market adjusts to new manufacturing capacities and shifting demand patterns. Understanding the timing of these peaks and troughs is crucial for capacity planning and inventory management.
Structural Segmentation and Value Chains
A deep dive into the structural composition of the market reveals distinct dynamics across material types, applications, and geographic regions. These segments do not perform in isolation; they are interconnected through supply chains and end-user requirements.
Hand Tools Market
Material Composition and Cost Drivers
The market is primarily divided by the construction material of the equipment. Steel remains a dominant force, reflecting its durability and cost-effectiveness for heavy-duty applications. Aluminum holds a significant position, valued for its lighter weight and corrosion resistance, particularly in scenarios where worker ergonomics and portability are priorities. Additionally, plastic and other composite materials constitute a portion of the market, often utilized for specific lightweight or specialized tasks. The choice of material is increasingly becoming a strategic decision influenced by raw material availability and tariff structures.
Application Verticals
Demand is driven by several key application verticals. Logistics and warehousing continues to be a primary consumer, driven by the need for efficient movement of goods within distribution centers. The retail sector represents another substantial chunk of demand, essential for stocking shelves and managing backroom operations. Furthermore, the industrial and construction sectors maintain consistent requirements for moving heavy equipment and materials on-site. Each vertical has unique specifications regarding load capacity, maneuverability, and durability, influencing the product mix required by manufacturers.
Regional Dynamics
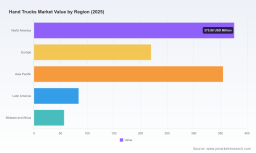
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America and Asia Pacific represent significant portions of the global volume, reflecting strong industrial bases and logistics networks in these regions. Europe maintains a steady demand profile supported by established manufacturing and retail infrastructures. Emerging markets in Latin America and the Middle East and Africa offer growth potential, though often at different scales of maturity. Understanding the regional weighting is essential for companies looking to expand their footprint or optimize their supply chain logistics.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established manufacturers and specialized providers. Market concentration indicates a moderately fragmented landscape, with the top three players holding a combined share of 25.5 percent and the top five holding 38.2 percent. This structure suggests that while there are dominant players, there is still room for niche providers and regional specialists to thrive.
Key Industry Players
Several companies define the current competitive arena, each bringing distinct strengths to the table.
Hand Trucks Market
- Harper Trucks: Based in Wichita, Kansas, this manufacturer is a pivotal figure in the industry, producing a significant portion of hand trucks sold in the United States. Their focus on heavy-duty hand trucks and appliance dollies positions them as a leader in high-volume utility solutions.
- Magliner: Located in Standish, Michigan, Magliner distinguishes itself through innovation. With over 4,000,000 possible custom builds, they offer convertible designs and innovative configurations that cater to specific user needs, emphasizing flexibility and customization.
- Vestil Manufacturing: Operating out of Angola, Indiana, Vestil boasts a massive manufacturing footprint with over 1,000 product lines and extensive square footage. They are a key supplier of industrial material handling equipment, including hand trucks and carts.
- American Cart and Equipment: Since 1997, this Archbold, Ohio-based producer has focused on heavy-duty hand trucks and multi-mover carts, with a strong emphasis on appliance and specialty carts manufactured in the United States.
- B&P Manufacturing: With facilities in the United States, B&P has been manufacturing hand trucks and material handling equipment since 1943. Their ISO 9001:2015 certification underscores a commitment to quality management and consistent production standards.
- Wesco Industrial Products: Based in North Wales, Pennsylvania, Wesco produces American-made hand trucks, including industrial duty, convertible, aluminum, and stair-climbing models, integrating hand trucks into a broader material handling portfolio.
Recent Strategic Developments
The competitive landscape is dynamic, with recent activity signaling shifts in strategy and capacity. In early 2025, Magliner introduced next-generation convertible hand truck models and new powered stair-climbing units, signaling a move toward enhanced functionality and powered solutions. Later in the year, Harper Trucks expanded its presence with advanced manufacturing technology and new product innovations, reinforcing its commitment to production efficiency.
Moving into 2026, strategic partnerships and capacity expansions have come to the forefront. B&P Manufacturing entered into a partnership to expand distribution and market position, aiming to broaden its reach. Simultaneously, Wesco Industrial Products implemented capacity expansion to increase production of hand trucks and related equipment. Vestil Manufacturing also released new innovative products, including hydraulic skid steer booms and electric tuggers, which complement hand truck-compatible material handling solutions. These moves indicate a sector preparing for increased demand and looking to diversify product offerings.
Regulatory and Macroeconomic Pressures
No strategic analysis is complete without addressing the external forces shaping the market. Regulatory changes and raw material costs are currently significant variables that influence pricing, sourcing, and ultimately, profitability.
Tariffs and Input Costs
A critical factor for manufacturers and buyers alike is the status of raw material tariffs. Effective March 2025, US Section 232 tariffs on aluminum and steel imports increased to 25 percent. This adjustment has direct implications for input costs for hand trucks and material handling equipment. For companies reliant on imported metals, this creates pressure on margins unless mitigated through supply chain adjustments or pricing strategies. Conversely, it may provide a protective advantage for domestic manufacturers who source materials locally, potentially altering the competitive balance between domestic and imported goods.
Trade Policy and Antidumping Duties
Trade policy remains in flux. The International Trade Commission initiated a five-year review on February 2, 2026, to determine the revocation of the antidumping duty order on hand trucks and parts from China. The outcome of this review could significantly impact the flow of imports and the pricing dynamics within the US market. Stakeholders must monitor this development closely, as a revocation could lower costs for imported units, while a continuation would maintain the current protective barrier for domestic producers.
Safety Standards and Compliance
Compliance with safety standards is non-negotiable in industrial environments. ISO 3691-5:2014 provides safety requirements for pedestrian-propelled trucks, including hand trucks. With verification standards updated for industrial use, manufacturers and users must ensure that equipment meets these criteria to avoid liability and ensure worker safety. Adherence to these standards is not just a regulatory requirement but also a market expectation, particularly in large logistics and industrial contracts.
Strategic Implications for 2026 Decision Makers
Synthesizing the market size, competitive actions, and regulatory environment, several strategic imperatives emerge for organizations operating in or utilizing the hand trucks market in 2026.
- Supply Chain Diversification: Given the tariff environment and potential trade policy shifts, relying on a single source for materials or finished goods introduces risk. Diversifying suppliers across regions or investing in domestic manufacturing partnerships can buffer against tariff shocks and supply disruptions.
- Product Mix Optimization: The demand for customization and specialized applications is evident from competitor moves. Companies should evaluate whether their current product portfolios align with the needs of high-growth verticals like logistics and warehousing. Investing in convertible designs or powered accessories could open new revenue streams.
- Cost Management and Pricing Strategy: With input costs fluctuating due to metal tariffs, precise cost modeling is essential. Pricing strategies must account for potential volatility in steel and aluminum markets while remaining competitive. Understanding the regional cost structures can help in negotiating better terms with suppliers.
- Monitoring Regulatory Developments: The ongoing antidumping duty review and safety standard updates require active monitoring. Changes in these areas can alter the competitive landscape overnight. Proactive engagement with regulatory updates allows companies to adjust their sourcing and compliance strategies ahead of competitors.
- Capacity Planning: As competitors like Wesco and Harper Trucks expand capacity, market supply may increase. Understanding the timing of these expansions relative to demand growth helps in planning inventory levels and avoiding oversupply or stockouts.
Conclusion: The Value of Deep Intelligence
The hand trucks market is more than a simple transaction of goods; it is a sector influenced by global trade policies, material science, and industrial demand shifts. The data points from 2020 through the 2032 forecast provide a skeleton of growth, but the flesh and blood of strategy lie in the details. Knowing the aggregate market size is useful, but understanding the specific dynamics of steel versus aluminum demand, the nuances of regional regulatory impacts, and the strategic intent of key competitors is where real value is created.
PW Consulting latest report on the Hand Trucks Market delves into these specifics, offering a level of detail that general market summaries cannot provide. From granular segmentation analysis that respects the confidentiality of specific regional percentages to deep dives into the operational strategies of key players, this research is built for action.
For enterprises aiming to secure their supply chains, optimize procurement costs, or identify new market entries, the margin for error is small. The insights contained within this study are designed to reduce that margin. We invite you to access the full research document to unlock the complete suite of data, forecasts, and strategic recommendations tailored to your specific operational context.
For detailed analysis of this topic, please visit the official page: Hand Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


