



PW Consulting: Healthcare Supply Chain Market to Reach $344.8M by 2032, Growing at 6.98% CAGR

Strategic Imperatives in the Global Healthcare Supply Chain Management Market: A 2026 Perspective
As the global healthcare ecosystem accelerates its digital transformation, supply chain management has evolved from a backend operational function to a strategic imperative. The convergence of regulatory pressure, demand for clinical resilience, and the rapid adoption of artificial intelligence is reshaping how pharmaceutical companies, medical device manufacturers, distributors, and healthcare providers orchestrate the movement of critical materials. PW Consulting latest market research provides a comprehensive intelligence framework designed to guide enterprise decision-making through 2032. This briefing outlines the structural trajectories, competitive dynamics, and operational realities defining the healthcare supply chain management landscape, while highlighting the analytical depth available in our full report.
Macro Economic Trajectory and Strategic Context
The healthcare supply chain management market has demonstrated consistent expansion over the past half-decade, driven by heightened visibility requirements, inventory optimization mandates, and the integration of cloud-native platforms across regulated environments. From a base valuation of approximately 163.15 million USD in 2020, the market expanded steadily through 2024, reaching 197.3 million USD, before crossing the 215.0 million USD threshold in 2025. Looking ahead, the market is projected to advance to 231.91 million USD in 2026, with sustained growth trajectories that ultimately push the addressable revenue envelope toward 344.8 million USD by 2032.
This expansion reflects a compound annual growth rate of 6.98 percent across the forecast horizon of 2026 through 2032. For enterprise strategists, this sustained upward curve is not merely a numerical indicator. It signals structural shifts in procurement architecture, real-time inventory governance, and the commercialization of AI-enabled orchestration tools that are redefining operational benchmarks. Organizations that align their investment roadmaps with these growth vectors position themselves to capture margin resilience, reduce clinical supply disruptions, and strengthen compliance postures as regulatory frameworks intensify.
Historical data further contextualizes this momentum. The segment demonstrated steady annual increases from 2021 through 2024, with each successive year reinforcing the market compounding baseline. The 2025 valuation of 215.0 million USD established a decisive inflection point, reflecting accelerated enterprise adoption of integrated supply chain platforms, expanded service engagements, and the broader commercialization of cloud-based deployment models. As 2026 progresses, the projected 231.91 million USD market size underscores how healthcare organizations are transitioning from pilot implementations to scaled, enterprise-wide supply chain architectures.
Core Segment Architecture and Operational Priorities
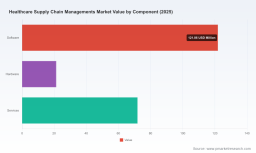
The structural composition of healthcare supply chain management spending reveals where enterprise attention and capital allocation are converging. Software remains the dominant component category, reflecting the industry prioritization of integrated platforms that unify purchasing, inventory, warehouse, and transportation workflows. Alongside software, services command substantial investment, underscoring the continued reliance on implementation expertise, managed operations, and consultative optimization as organizations navigate complex clinical and regulatory environments. Hardware investments, while proportionally smaller, remain essential for facilities that require specialized tracking infrastructure and on-site logistics tooling.
Functionally, purchasing management represents the largest share of operational spend, highlighting the strategic weight placed on supplier relationship orchestration, procurement visibility, and cost-rationalization initiatives. Inventory management follows as a critical operational pillar, driven by the need to balance availability against carrying costs in environments where shortages carry direct clinical consequences. Warehouse operations, transportation coordination, and order management collectively form the execution backbone of healthcare logistics, each addressing distinct pain points ranging from sterile handling requirements to last-mile specimen movement and high-velocity replenishment cycles.
From a product perspective, pharmaceutical and biotechnology supplies dominate managed volumes, reflecting the stringent cold-chain requirements, serialization mandates, and regulatory scrutiny inherent in drug distribution. Medical devices and equipment constitute the next major category, with complex asset tracking, maintenance scheduling, and procurement coordination demanding specialized supply chain capabilities. Additional product categories round out the managed portfolio, ensuring the framework accommodates diverse operational needs across the healthcare value chain.
Deployment architecture further shapes adoption velocity. Cloud-based models lead in deployment preference, driven by scalability, real-time data integration, and the ability to centralize visibility across distributed facilities. On-premise deployments persist where data sovereignty, legacy system integration, or highly controlled environments favor localized infrastructure. Other deployment configurations accommodate hybrid approaches and transitional architectures as organizations modernize at varying paces.
End-user demand is broadly distributed, with manufacturers and healthcare providers each commanding substantial engagement. Manufacturers focus on upstream coordination, demand forecasting, and outbound logistics efficiency, while healthcare providers prioritize internal procurement optimization, clinical inventory control, and supply assurance across departments. Distributors, alongside other end-user categories, complete the ecosystem by enabling intermediary logistics, cross-facility movement, and regional fulfillment capabilities.
Competitive Dynamics and Strategic Positioning
The competitive landscape is defined by a diversified set of specialists and platform-scale vendors, each pursuing distinct value propositions within healthcare supply chain management. Market concentration remains moderate, with the top three competitors collectively accounting for 34.5 percent of market share and the top five reaching 45.2 percent. This fragmentation signals both opportunity and complexity: enterprises can select from a wide spectrum of capabilities, but must also navigate differing integration models, regulatory alignment, and maturity levels across vendor offerings.
Tecsys Inc., headquartered in Toronto, Ontario, anchors its strategy on end-to-end inventory visibility, supplier workflow management, and AI-driven intelligence tailored to regulated healthcare environments. Its Elite Healthcare SCM platform is engineered to reduce costs while preserving continuity of patient care, with recent updates in early 2026 expanding agentic capabilities designed to mitigate shortages, minimize waste, and strengthen compliance risk management. Chooch AI, based in San Mateo, California, pursues a distinctive autonomous vision approach, leveraging agentic AI for automated hospital inventory tracking, real-time replenishment, and ERP integration without reliance on manual counts or traditional barcode workflows. Its recognition with a 2025 AI Breakthrough Award reflects growing enterprise interest in hands-free, vision-based inventory automation.
MedSpeed, operating from Elmhurst, Illinois, emphasizes same-day healthcare logistics and system-wide last-mile movement of specimens, pharmaceuticals, and supplies. Its focus on intra-company supply chain integration addresses the acute operational challenge of moving time-sensitive materials across distributed care networks. Premier Inc., headquartered in Charlotte, North Carolina, combines AI-driven supply chain optimization with group purchasing and real-time insights to strengthen procurement resilience. In February 2026, Premier announced a large-scale, multi-year technology investment program to build an intelligent healthcare supply chain of the future, signaling a long-horizon commitment to platform modernization and network-wide efficiency.
Enterprise-scale platform providers continue to exert structural influence. Oracle Corporation, based in Austin, Texas, integrates clinically aware supply chain capabilities within its Fusion Cloud SCM portfolio, with September 2025 enhancements expanding AI-powered visibility and efficiency tools for healthcare operations. Infor Inc., headquartered in New York, advances CloudSuite healthcare supply chain management with a focus on clinically integrated optimization, targeting shortage reduction and the mitigation of operational friction across provider networks. Manhattan Associates, located in Atlanta, Georgia, positions its AI-native ActivePlatform for unified supply chain orchestration, planning, and execution, with healthcare-specific tailoring for logistics complexity and compliance requirements.
For enterprises evaluating vendor partnerships, the strategic question is not simply which platform offers the broadest feature set, but which combination of intelligence, deployment flexibility, regulatory alignment, and clinical workflow integration best matches an organization operational reality. The report provides a structured comparative lens that goes beyond product descriptions to examine how each competitor approaches integration complexity, change management, and the operational outcomes that matter most in regulated care environments.
Regulatory Architecture and Operating Conditions
Healthcare supply chain management does not operate in a regulatory vacuum. The HIPAA Security Rule requires accurate and thorough assessment of potential risks and vulnerabilities affecting the confidentiality, integrity, and availability of all electronic protected health information. This obligation extends into supply chain software operations, where third-party service providers must be subject to due diligence and ongoing oversight to ensure they do not introduce exposure into the protected data environment.
Recent regulatory developments have further tightened the compliance perimeter. Federal Register proposed modifications to the HIPAA Security Rule in early 2025 sought to strengthen cybersecurity protections for electronic protected health information within healthcare supply chains, signaling heightened expectations for vendor risk management, access controls, and incident readiness. Subsequent guidance from the HHS Office for Civil Rights reinforced that the Security Rule is designed to be scalable and technology neutral, applying across entities ranging from small providers to large cloud service providers engaged in supply chain management. Additional oversight from the New York Department of Financial Services emphasized the necessity of continuous monitoring for third-party providers that access or process nonpublic information.
Healthcare Supply Chain Managements Market
Next Gen Supply Chain Market
These regulatory dynamics create a dual mandate for supply chain leaders. On one hand, digital modernization and AI-enabled automation are essential to achieving the visibility and responsiveness modern healthcare logistics demand. On the other, each technology investment must be evaluated for data governance implications, third-party risk exposure, and alignment with evolving security expectations. The operational consequence is that compliance is no longer a separate initiative from supply chain strategy; it is a design constraint that shapes platform selection, integration architecture, and vendor governance.
What the Full Research Delivers
PW Consulting Healthcare Supply Chain Management Market research is designed to convert macro trends into executable strategy. The report provides a detailed segmentation mapping across region, component, function, product managed, deployment model, and end user, enabling leaders to benchmark their portfolio positioning against the broader market architecture. Rather than presenting data in isolation, the analysis connects each segment to operational implications, investment prioritization, and competitive positioning.
The study includes a thorough competitive profiling framework that evaluates strategic focus areas, technology orientation, and recent development activity across leading vendors. By aligning product capabilities with market demand patterns, the report helps procurement, IT, and supply chain executives distinguish between vendor narratives and measurable operational value. Recent product launches, partnership announcements, and award recognitions are contextualized within broader adoption trends, helping organizations assess which developments represent meaningful capability shifts versus incremental enhancements.
Our research also examines the regulatory environment in depth, translating compliance requirements into practical decision criteria for platform selection, vendor due diligence, and data governance architecture. The analysis addresses how security expectations influence cloud adoption, third-party integration, and the deployment of AI-driven automation in regulated healthcare settings. For organizations planning multi-year modernization roadmaps, this regulatory context is essential for de-risking investment and ensuring that operational efficiency gains do not come at the expense of compliance exposure.
Additionally, the report incorporates scenario-based forecasting that maps growth trajectories across the forecast period, allowing leaders to test strategic assumptions against multiple market pathways. This forward-looking structure supports resource allocation decisions, capacity planning, and vendor negotiation strategies by clarifying where demand is most likely to intensify and which functions will command disproportionate attention as the market matures.
Strategic Takeaways for 2026 Decision-Makers
The healthcare supply chain management market is entering a phase where scale, intelligence, and compliance fuse into a single strategic agenda. Several priorities stand out for executives shaping investment and operating decisions in 2026 and beyond.
- Align technology investments with clinical outcomes. Platforms that connect procurement, inventory, and logistics directly to patient care continuity deliver value that transcends cost reduction, strengthening organizational resilience during supply volatility.
- Treat AI adoption as an orchestration challenge, not a point solution. Autonomous tracking, agentic replenishment, and predictive visibility tools are advancing rapidly, but their impact depends on integration depth, workflow redesign, and governance maturity.
- Embed regulatory readiness into platform selection. As HIPAA-related expectations and third-party oversight requirements intensify, vendors must demonstrate not only functional capability but also defensible data handling, risk management, and compliance alignment.
- Benchmark against segment-weighted demand patterns. Understanding where purchasing management, inventory control, cloud deployment, and pharmaceutical management concentrate spend helps organizations prioritize modernization efforts that reflect actual market momentum.
- Evaluate vendor ecosystems through an outcomes lens. With moderate market concentration and a diverse set of specialists and platform providers, the strategic differentiator lies in measurable improvements to shortage mitigation, waste reduction, and operational friction across care networks.
The full PW Consulting Healthcare Supply Chain Management Market research report provides the detailed segment sizing, competitive benchmarking, regulatory analysis, and strategic scenario frameworks needed to convert these priorities into a structured execution plan. For leaders navigating vendor evaluation, capital allocation, and multi-year supply chain strategy, the complete intelligence package offers the depth required to make decisions with confidence in a market that is expanding steadily and evolving rapidly.
For detailed analysis of this topic, please visit the official page: Healthcare Supply Chain Managements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


