



PW Consulting: Preclinical Tomography Market to Hit $490.93M by 2032, Growing at 9.14% CAGR

Strategic Intelligence for the Preclinical Tomography System Market Through 2032
The preclinical imaging sector is entering a decisive inflection point. Over the past half-decade, tomographic platforms have evolved from specialized academic tools into core infrastructure for drug discovery, toxicology, and translational biology. For executive teams, capital allocators, and R&D leaders, understanding this trajectory is no longer optional. It is a prerequisite for informed investment, pipeline prioritization, and competitive positioning. Our newly published research on the Preclinical Tomography System Market captures this transformation with granular precision, mapping historical performance, forward-looking forecasts, competitive dynamics, and regulatory shifts that will shape enterprise decisions well into the next decade.
Preclinical Tomography System Market
This article offers a strategic preview of the study, illustrating how the analysis connects macro-level market evolution to actionable, boardroom-ready insights. While the full report delivers exhaustive segment-level data, vendor benchmarks, and scenario modeling, the following overview demonstrates the analytical depth, operational relevance, and decision-support architecture that define our methodology.
Historical Trajectory and Forward Growth Architecture
The market has demonstrated consistent expansion from 2020 through the base year of 2025, building on sustained adoption across research institutions, hospital-affiliated laboratories, and pharmaceutical discovery units. Revenue progression over this six-year window reflects compounding demand for high-resolution, in vivo imaging that reduces reliance on terminal histopathology and accelerates iterative study design. The revenue baseline established at the end of 2025 provides a stable foundation for the projection phase, which extends through 2032.
Over the forecast horizon, the market is projected to advance at a compound annual growth rate of 9.14%, measured in USD millions. This trajectory is not purely linear; it reflects accelerating replacement cycles, broader integration of multimodal tomography platforms, and increasing procurement standardization across enterprise research portfolios. The forward curve captures both volume-driven expansion and value migration toward higher-resolution, workflow-integrated systems that reduce total cost of ownership while improving data reproducibility.
For decision-makers, the strategic implication is clear. Budget planning, capital expenditure approval, and vendor evaluation must account for a market that is scaling steadily rather than experiencing speculative spikes. Forecasting through 2032 enables procurement leaders to model phased rollout strategies, R&D directors to align imaging capacity with pipeline timelines, and investors to assess long-term demand resilience across therapeutic and academic end-users.
Structural Drivers Reshaping Procurement and Research Workflows
Several structural forces are converging to amplify demand for preclinical tomography systems. First, the industry-wide shift toward in vivo, longitudinal imaging is reducing study attrition and improving translational fidelity. High-resolution micro-CT and emission tomography platforms now enable repeated measurements in the same subject, supporting pharmacokinetic modeling, bone and dental microarchitecture assessment, soft tissue characterization, and disease progression tracking with greater statistical confidence.
Second, regulatory expectations around imaging biomarkers are becoming more prescriptive. Guidance from major health authorities increasingly positions tomographic imaging as essential for pharmacokinetic and toxicity assessments within investigational new drug frameworks. Parallel recommendations emphasize standardized protocols for good laboratory practice compliance, reproducible data generation, and multimodal assessment strategies for novel therapeutics, including gene therapies and cellular products. For sponsors and contract research organizations, these expectations elevate imaging from a supportive technique to a compliance-critical workflow component.
Third, ethical and documentation requirements governing animal model usage continue to tighten. Legislative frameworks in the United States and European Union impose rigorous oversight on preclinical animal studies, which in turn incentivizes adoption of imaging platforms that enable fewer subjects, richer datasets, and stronger documentation trails. Institutions that standardize on validated tomography systems are better positioned to satisfy oversight requirements while preserving research throughput.
Finally, workflow integration and multimodal convergence are reshaping procurement criteria. End-users increasingly evaluate systems not only on raw resolution, but on interoperability with reconstruction software, informatics pipelines, automated analysis modules, and multi-modality configurations that combine structural and functional imaging. This evolution favors vendors that deliver compact benchtop performance alongside enterprise-grade scalability, clinical compliance alignment, and continuous software enhancement.
Competitive Positioning and Recent Market Developments
The competitive landscape is concentrated, with leading vendors differentiating through hardware innovation, regulatory milestones, and ecosystem partnerships. Three organizations illustrate the strategic directions currently shaping the market.
Bruker Corporation
Headquartered in Billerica, Massachusetts, Bruker has expanded its preclinical imaging portfolio with advanced micro-CT platforms designed for high-resolution in vivo imaging of small animals and biological samples. Its product lineage, including the X4 POSEIDON, SKYSCAN 1273, and SKYSCAN 2214 CMOS Edition systems, targets detailed structural imaging across bone, dental, and soft tissue applications. In February 2025, Bruker launched the X4 POSEIDON advanced X-ray microscope with micro-CT functionality, delivering compact benchtop performance and enhanced image quality for preclinical life-science workflows. This release reinforces a broader competitive shift toward high-performance systems that fit within constrained laboratory footprints while preserving research-grade imaging fidelity.
SCANCO Medical AG
Based in Bassersdorf, Switzerland, Scanco Medical maintains a focused presence in preclinical micro-CT through platforms engineered for in vivo small-animal studies. Its vivaCT 80 in vivo micro-CT scanner is positioned around a large field-of-view and high-resolution imaging capability, supporting longitudinal study designs and detailed structural assessment. Scanco’s strategy reflects sustained emphasis on specialty preclinical imaging where resolution, reproducibility, and workflow consistency carry outsized importance for academic and translational research teams.
Mediso Medical Imaging Systems
Operating from Budapest, Hungary, Mediso has built its competitive identity around multimodal tomography systems that combine structural and functional imaging for molecular preclinical research. The nanoScan family encompasses preclinical PET/CT, SPECT/CT, and multi-modality configurations designed to support molecular imaging applications. In December 2025, Mediso received FDA 510(k) clearance for the AnyScan 3.0 NM Scanner Family, encompassing PET/CT and SPECT/CT systems suitable for preclinical research applications. This regulatory milestone is strategically significant because emission tomography clearances increasingly hinge on recognized performance and safety standards, raising the barrier to entry for new competitors while strengthening the compliant positioning of established vendors.
Beyond these core players, the broader ecosystem includes partnerships and collaborations that expand imaging infrastructure and co-develop advanced workflows. For example, a December 2024 strategic collaboration between Nikon Metrology and Taipei Medical University established a joint micro-CT imaging center and initiated co-development of advanced preclinical imaging workflows. Moves of this kind signal growing institutional investment in shared imaging capacity, standardized acquisition protocols, and cross-functional research integration.
Regulatory and Compliance Architecture as a Market Catalyst
Regulatory and ethical frameworks are no longer peripheral considerations; they are shaping product requirements, procurement criteria, and time-to-deployment. Clearance pathways for emission computed tomography systems, including recent submissions for preclinical scanner families, reference compliance with recognized standards for performance and safety. These expectations influence not only vendor validation processes but also institutional purchasing decisions, where demonstrable compliance reduces operational risk and supports smoother study approval.
Simultaneously, guidance around imaging biomarkers in preclinical studies is pushing organizations toward standardized protocols that support GLP compliance and reproducible data in drug development submissions. Updated international guidelines for preclinical imaging emphasize multimodal assessment strategies for novel therapeutics, reinforcing the value of platforms that can integrate structural, functional, and molecular readouts within consistent workflows. For sponsors, CROs, and academic centers, this translates into stronger demand for systems that minimize protocol variability and help maintain auditable documentation across study phases.
The interaction between regulatory evolution and procurement strategy is particularly important for enterprise buyers. When evaluating platforms, organizations increasingly consider not just immediate imaging performance, but also long-term alignment with evolving standards for safety, biomarker validation, multimodal integration, and animal welfare documentation. In this environment, the ability to forecast which system architectures will remain compliant and adaptable through the end of the decade becomes a genuine competitive advantage.
Why This Research Matters for 2026 Decision-Making
Market intelligence in this sector must do more than describe growth. It must help leadership teams anticipate capital needs, align technology roadmaps, and interpret competitive signals with confidence. Our Preclinical Tomography System Market study is designed for that practical purpose, translating historical performance and forward projections into structured decision support for 2026 and beyond.
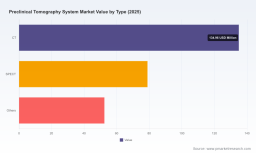
The report provides comprehensive coverage across the full market architecture, including revenue evolution from historical years through the forecast horizon, segment-level breakdowns by region, system type, and application, and competitive profiling of key participants. It examines procurement drivers, regulatory catalysts, technology adoption patterns, and the implications of recent product launches, clearances, and strategic collaborations. Importantly, the analysis is organized to support use cases that matter to executives: budget allocation, vendor evaluation, capacity planning, partnership assessment, and risk-adjusted market entry or expansion strategy.
Several elements distinguish the study from generic market summaries. First, the forecast structure enables multi-year planning under a consistent growth framework, allowing organizations to model different adoption and replacement scenarios rather than relying on point estimates. Second, competitive profiling connects product offerings to real-world strategic moves, including benchtop performance innovations, multimodal system expansions, and regulatory clearances that alter market access dynamics. Third, regulatory context is woven directly into market dynamics, helping readers understand why compliance, standardization, and documentation requirements are influencing demand patterns and procurement cycles.
For 2026 specifically, the research supports several high-value actions. R&D and imaging operations leaders can use the forecast and segmentation framework to justify phased capital deployment and align imaging capacity with pipeline milestones. Procurement teams can benchmark system types and end-user application demand to refine request-for-proposal criteria and evaluate total cost of ownership across competing platforms. Business development and corporate strategy teams can interpret competitive moves, partnership activity, and regulatory timing to anticipate market consolidation, identify white-space opportunities, and prepare for evolving buyer expectations.
By integrating macro growth trends with operational realities, the report helps transform uncertainty into structured planning. Readers gain clarity on how revenue progression, system type adoption, application demand, and regional dynamics interact over the forecast period, while maintaining the flexibility to stress-test assumptions according to internal priorities and research pipelines.
What the Full Study Delivers
While this preview outlines the strategic framework, the complete report provides the detailed intelligence required for precise execution. The full analysis includes:
- Historical market sizing and forward projections through the end of the forecast period, expressed in consistent revenue units to support budget modeling and scenario comparison.
- Segment-level breakdowns that help clarify where demand is concentrated across geography, system type, and end-use application, enabling targeted planning without exposing enterprise strategy to one-size-fits-all assumptions.
- Competitive assessments that connect vendor portfolios, recent launches, regulatory developments, and collaboration activity to actionable positioning insights.
- Regulatory and compliance analysis that contextualizes clearance requirements, imaging biomarker expectations, GLP considerations, and animal welfare documentation within procurement and workflow decisions.
- Strategic interpretation of market concentration and competitive dynamics, helping readers understand how leadership positions, differentiation levers, and ecosystem partnerships shape near-term competition.
This is precisely the type of evidence base that supports confident decisions in 2026, when organizations must reconcile accelerating imaging adoption with compliance expectations, budget discipline, and the need to future-proof laboratory infrastructure.
Moving from Insight to Action
The Preclinical Tomography System Market is expanding with measurable momentum, but the real strategic challenge lies in interpreting that momentum correctly. Growth alone does not dictate successful investment; the value comes from understanding where demand is forming, which system architectures are gaining traction, how regulatory requirements are reshaping procurement, and which competitive moves signal longer-term positioning shifts.
Our research is built to answer those questions with discipline and specificity. It offers the analytical structure needed to plan capital deployment, refine vendor selection, align imaging strategy with R&D timelines, and anticipate compliance-driven changes in buyer behavior. For executives who need more than broad market narratives, the full report delivers the depth, segmentation, and competitive intelligence required to act decisively.
Computed Tomography System Market
To access the complete market analysis, detailed segment data, and executive-ready strategic recommendations, visit the full report page and secure the comprehensive intelligence package designed for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Preclinical Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


