



PW Consulting: Pipe Joints Market Hits $228.6M in 2025, Projected to Reach $327.9M by 2032

Strategic Intelligence for the Pipe Joints Market 2026-2032: Navigating Growth, Competition, and Regulatory Shifts
The global pipe joints market stands at a pivotal juncture as organizations prepare for the 2026 fiscal year and beyond. Infrastructure spending, industrial expansion, and evolving safety regulations are converging to reshape demand patterns across multiple sectors. For executives, procurement leaders, and strategic planners, the ability to anticipate these shifts is not merely an advantage, it is a necessity. Our latest Pipe Joints Market research delivers a comprehensive, data-driven blueprint designed to inform capital allocation, product positioning, and competitive strategy through 2032.
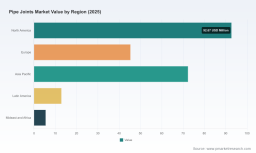
This insight briefing outlines the macro trajectory, competitive architecture, and emerging dynamics that will define the market landscape. It is structured to demonstrate the analytical rigor and actionable depth embedded in the full report, while intentionally reserving granular segmentation figures, regional breakdowns, and application-specific revenue allocations for the complete dataset available on our platform.
Macro Trajectory: A Resilient Growth Arc Across the Forecast Horizon
Drawing on historical performance from 2020 through 2025 and extending into a seven-year forecast period spanning 2026 to 2032, the market demonstrates a consistent upward trajectory. The overall revenue base, measured in USD millions, has progressed from 173.5 in 2020 to 181.33 in 2021, 187.78 in 2022, and 209.06 in 2023. The pace of expansion accelerated notably in 2024 and 2025, with recorded revenues of 209.42 and 228.6 respectively, reflecting stronger industrial activity, renewed construction momentum, and recovering supply chain conditions.
The forecast window projects sustained growth, with the market expected to reach 243.46 in 2026, followed by 255.59 in 2027, 269.9 in 2028, 290.04 in 2029, 293.41 in 2030, 308.93 in 2031, and a projected 327.9 by 2032. This pathway corresponds to a compound annual growth rate of 5.35 percent across the forecast horizon, signaling a market that is expanding at a steady, investable pace rather than experiencing volatile spikes. For strategic planners, this CAGR provides a reliable baseline for capacity planning, inventory forecasting, and long-term partnership structuring.
Importantly, the absolute scale of the market and the consistency of its growth underscore the foundational role that pipe joints and couplings play across critical infrastructure and industrial ecosystems. As organizations map their 2026 objectives, understanding how this trajectory aligns with regional development cycles, application-specific demand surges, and material cost normalization becomes a central component of scenario planning.
What the Report Delivers: Operational Content Designed for Execution
The full Pipe Joints Market study goes beyond top-line projections to equip decision-makers with structured, implementation-ready intelligence. The report is organized around several core analytical pillars, each calibrated to support distinct enterprise functions:
- Market sizing and forward modeling: Historical baselines and forecast pathways are presented with methodological transparency, enabling teams to anchor budgeting and demand planning in validated trajectories rather than speculative estimates.
- Segmentation architecture: The analysis dissects the market across product types, application verticals, and geographic regions. While aggregate growth signals are clear, the report provides the segmented context necessary to identify where demand is concentrating, which product categories are outpacing the broader curve, and how application-driven procurement patterns differ across industries.
- Competitive landscape and concentration metrics: Market structure is evaluated through concentration indicators, revealing the degree of fragmentation versus consolidation. This framework helps organizations assess entry barriers, partnership opportunities, and the strategic implications of operating in a market where the top three players hold a measured share and the top five maintain a slightly broader but still moderate footprint.
- Pricing and cost environment analysis: Unit economics are examined in the context of material inputs, manufacturing complexity, and specification tiers. The report situates price ranges for standard metal and alloy fittings within broader cost dynamics, giving procurement and pricing teams a reference frame for negotiations, margin planning, and make-versus-buy decisions.
- Regulatory and compliance mapping: Emerging codes and installation mandates are tracked to highlight how policy shifts influence material selection, approval workflows, and project timelines. This section is particularly relevant for firms operating in jurisdictions where nonmetallic joint specifications and manufacturer installation protocols are becoming more stringent.
- Recent industry developments and event intelligence: Product launches, trade show activity, and supplier announcements are synthesized to provide a live pulse on innovation cadence and market engagement. This ensures that strategy teams are aware of near-term product introductions and industry gatherings that may influence competitive positioning or procurement cycles.
Competitive Landscape: Key Players and the Structure of Market Participation
The pipe joints sector is characterized by a mix of established manufacturers, specialized engineering firms, and regional suppliers, each competing on dimensions such as joint integrity, installation efficiency, diameter range, and application-specific performance. The report profiles several core companies whose product portfolios and recent moves illustrate the competitive dynamics shaping the market.
Northwest Pipe Company, headquartered in Bellingham, Washington, focuses on engineered steel water pipe solutions with watertight joint systems, including its InfraShield® platform and custom mechanical couplings designed to preserve pipeline integrity under demanding service conditions. Victaulic, based in Easton, Pennsylvania, manufactures grooved mechanical pipe couplings and joining systems that emphasize faster, safer installation across industrial applications, and has continued to expand its fire protection portfolio with recent coupling introductions targeting rigid pipe joints in sprinkler systems. Teekay Couplings, operating from the United Kingdom, produces mechanical pipe couplings spanning a wide diameter range, with an emphasis on space, weight, and installation efficiency for diverse project requirements.
American Cast Iron Pipe Company, located in Birmingham, Alabama, offers restrained joint solutions such as Flex-Ring and Field Flex-Ring designs for ductile iron pipe, addressing endwise separation risks under thrust conditions. Holz Rubber Company, based in the United States, manufactures custom and standard expansion joints that absorb thermal movement and accommodate misalignment in piping systems, supporting reliability across variable operational environments.
These profiles are not isolated company snapshots; they are embedded within a broader concentration analysis that quantifies how market share is distributed and what that distribution implies for competitive strategy. In a market where the top three participants collectively hold approximately 22.8 percent and the top five reach roughly 28.5 percent, the landscape remains relatively fragmented at the top, leaving meaningful room for specialized players, regional specialists, and innovation-driven entrants to compete on performance, service, and application focus rather than scale alone.
Recent activity reinforces this dynamic. In early 2026, Victaulic introduced its style 009v FireLock coupling for rigid pipe joints in sprinkler systems, reflecting continued product development in fire protection and mechanical coupling segments. On the industry engagement front, Iran PIVEX held a January 2026 trade show featuring pipe joints and fittings from international suppliers, while the TUBE Trade Fair in Düsseldorf, scheduled for April 2026, is expected to showcase a broad array of pipe joints and coupling exhibitors. These events signal active supplier participation and sustained interest in cross-border sourcing, technology demonstration, and partnership formation.
Market Dynamics and Contextual Forces Shaping 2026 Decision-Making
Beyond sizing and competition, the research integrates the contextual forces that influence how the market behaves in practice. One notable development is the normalization of raw material costs. Steel prices for pipe joints and couplings are moderating in 2026 following earlier declines, as base metal costs stabilize. This shift has direct implications for manufacturing margins, supplier pricing strategies, and procurement timing, particularly for organizations that delayed purchasing decisions during periods of price volatility.
Pipe Joints Market
Artificial Joints Market
Regulatory evolution is equally consequential. The 2025 Ohio Fire Code mandates that nonmetallic pipe joints must be approved and installed in accordance with manufacturer instructions, reinforcing the importance of compliance documentation, approved product listings, and installer training. For firms operating in or supplying to jurisdictions with similar code trajectories, this type of requirement can affect product selection, project approval timelines, and the relative attractiveness of metallic versus nonmetallic joint solutions in specific applications.
Cost structures also vary meaningfully across specification tiers. General steel or metal pipe joints typically range from approximately USD 30 to over USD 200 per unit, while high-specification alloy fittings can reach between USD 500 and USD 2,000. These ranges illustrate how performance requirements, material grades, and application criticality drive pricing dispersion. For strategic planners, the key insight is that average market growth does not imply uniform profitability across all product categories; instead, value capture often depends on positioning within higher-specification segments, optimizing supply chain efficiency, or differentiating through installation reliability and joint performance.
Together, these dynamics create a market environment where growth is broad-based but execution is highly segmented. Companies that succeed in 2026 and beyond will be those that align their product portfolios with application demand, monitor material cost trends closely, and maintain agility in response to code changes and installation standards.
Why This Research Matters for 2026 Enterprise Decisions
As organizations finalize 2026 strategies, the pipe joints market presents both opportunity and complexity. The projected expansion from 243.46 in 2026 toward 327.9 by 2032, supported by a 5.35 percent CAGR, indicates that demand will continue to grow at a meaningful pace. however, growth at the aggregate level masks important variation across regions, product types, and end-use sectors. Without segmented visibility, companies risk overcommitting to underperforming categories, underestimating regional demand intensity, or misaligning pricing and inventory strategies with actual procurement behavior.
This research is designed to reduce that uncertainty. By combining macro forecasting with structured segmentation, competitive profiling, concentration metrics, and contextual intelligence on materials, regulation, and recent industry activity, the report provides a decision-ready framework for multiple functional teams:
- Strategy and corporate development: Evaluate where to invest, which application verticals offer the strongest near-term tailwinds, and how market concentration shapes partnership and acquisition logic.
- Sales and commercial leadership: Identify high-potential segments, tailor value propositions around joint integrity, installation efficiency, and compliance readiness, and align go-to-market plans with regional demand patterns.
- Procurement and supply chain: Time purchases in response to material cost normalization, assess supplier diversity and concentration risk, and benchmark unit economics against specification tiers.
- Product and engineering: Prioritize development toward mechanical coupling innovations, restrained joint technologies, expansion joint solutions, and fire protection systems where recent launches and trade show activity indicate active market interest.
The full report also contains the detailed regional and application-level segmentation data, granular revenue allocations, and deeper competitive benchmarking that are essential for precise planning. Those specifics are intentionally reserved for the complete dataset, ensuring that teams accessing the full study receive the uncompromised intelligence needed for targeted execution.
Looking Ahead: Positioning for Durable Advantage
The pipe joints market is not simply expanding; it is evolving in ways that reward precision, compliance awareness, and application-specific engineering. As steel costs stabilize, fire and installation codes tighten, and major suppliers continue to introduce specialized coupling and joint technologies, the competitive edge will belong to organizations that can translate market-level growth into segment-level action.
Our Pipe Joints Market research provides the foundation for that translation. It equips leadership with the historical context, forecast confidence, competitive structure, and dynamic intelligence required to make informed decisions throughout 2026 and across the remainder of the forecast period. For teams ready to move from high-level outlook to detailed planning, the complete report offers the segmentation depth, regional specificity, and application-level revenue context necessary to operationalize strategy with precision.
The 2026 market environment will reward those who prepare with data, act with segmentation discipline, and monitor the regulatory and material shifts that shape real-world demand. This study is built to support that preparation from the first strategic review through to execution.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


