



PW Consulting: Industrial Hose Market Hits $14.35B in 2025 with 6.98% CAGR Through 2032

Industrial Hose Market Outlook 2026: Strategic Intelligence for Enterprise Decision Makers
The industrial hose market stands at a critical inflection point as the global economy navigates shifting supply chain dynamics, evolving regulatory frameworks, and sustained capital investment across heavy industry. Our latest comprehensive market research, Industrial Hose Market Analysis 2026, delivers the strategic intelligence needed to navigate this complex landscape. This report is not merely a data compilation, but a decision-support engine designed for executives, procurement leaders, and strategic planners who require actionable foresight rather than retrospective summaries. With a forecast horizon extending through 2032, our analysis captures both the immediate pressures shaping 2026 operations and the structural shifts that will define competitive advantage over the next half-decade.
Market Trajectory and Structural Growth Patterns
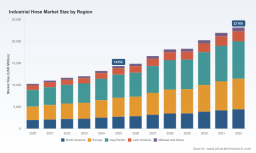
The industrial hose sector has demonstrated consistent revenue expansion over the past half-decade, with historical performance data from 2020 through 2025 establishing a clear trajectory of resilience and demand acceleration. Total market valuation has progressed from a baseline of 10,278.0 million USD in 2020, reaching 11,011.88 million USD in 2021, and advancing through 11,654.77 million USD in 2022, 12,007.18 million USD in 2023, 13,227.84 million USD in 2024, before culminating at 14,352.0 million USD in 2025. This historical arc reflects sustained capital deployment across fluid transfer infrastructure, equipment modernization cycles, and infrastructure development initiatives globally.
The forecast period from 2026 through 2032 projects continued expansion, anchored by a compound annual growth rate of 6.98 percent. Revenue is expected to reach 14,864.94 million USD in 2026, scaling toward 16,623.63 million USD by 2027, 18,166.93 million USD in 2028, 18,307.89 million USD in 2029, 20,276.98 million USD in 2030, 21,952.85 million USD in 2031, and ultimately 23,169.0 million USD by 2032. These figures represent nominal market size in USD millions, reflecting the aggregate value of hose products, assemblies, and associated fluid handling components across all industrial applications. The sustained growth rate underscores a market that continues to expand beyond cyclical recovery, driven by underlying industrial activity and technological modernization.
Importantly, our methodology isolates growth drivers from noise, enabling stakeholders to distinguish between temporary demand spikes and durable structural expansion. The 6.98 percent CAGR encompasses multiple interacting variables, including raw material cost volatility, geographic supply chain reconfiguration, regulatory compliance costs, and the ongoing shift toward high-performance composite and thermoplastic materials. executives who rely solely on headline growth figures risk misallocating resources; our analysis deconstructs these layers to reveal where sustainable value creation resides.
2026 Strategic Context: Pricing Pressures, Standards, and Operational Realities
The current operating environment is defined by intersecting cost and compliance pressures that directly influence procurement budgets, manufacturing margins, and product specification decisions. As of early 2026, stainless steel prices have stabilized near 1,995 USD per ton, a level that directly impacts hydraulic hose production costs and influences the economics of metal-reinforced assemblies. Simultaneously, natural rubber benchmark pricing has fluctuated between approximately 1.61 and 2.23 USD per kilogram, while synthetic rubber FOB pricing in China registered around 2,267 USD per ton in January 2026. These input cost dynamics do not merely affect short-term pricing; they reshape the competitive positioning of material categories, forcing manufacturers and buyers alike to reevaluate specification strategies, inventory management approaches, and total cost of ownership calculations.
Regulatory and standards evolution adds another critical dimension. The newly defined EN 854:2026 specifications establish updated requirements for textile reinforced rubber hydraulic hoses and assemblies intended for industrial and commercial applications, creating a compliance imperative that will influence product selection, certification processes, and market access for suppliers who have not aligned their portfolios accordingly. Concurrently, OSHA regulations continue to set binding workplace safety rules for hose handling and pressure systems in industrial settings, reinforcing the operational importance of durable, compliant assemblies that reduce incident risk and support audit readiness. These standards are not peripheral considerations; they embed themselves into procurement criteria, supplier qualification processes, and liability frameworks across multiple sectors.
Industrial Hose Market
Worldwide Industrial Flexible Hose Market
Trade show activity during early 2026 further illustrates the industry's active engagement with these dynamics. Companies including Salem-Republic Rubber Company, NRP Jones, Tubes International, and Elastohose have all maintained visible booth presences at major industry gatherings such as CONEXPO-CON/AGG 2026 and FLUID POWER 2026, showcasing product innovations, engaging with end-users, and signaling strategic priorities around durability, material advancement, and application-specific engineering. This sustained exhibition activity reflects an industry in active dialogue with its customer base, adapting to technical requirements and competitive expectations in real time.
Core Research Dimensions: What the Report Delivers
Our analysis is structured to provide immediate tactical value alongside long-term strategic orientation. Rather than presenting isolated data points, the report integrates quantitative benchmarking with qualitative assessment to produce a decision framework applicable across corporate functions.
Quantitative Benchmarking and Historical Reconstruction
The research reconstructs historical market performance from 2020 through 2025, calibrating base-year 2025 figures before projecting forward through 2032. This structure allows users to validate internal assumptions against audited market trajectories, identify periods of outperformance or underperformance relative to industry trends, and model scenario-based forecasts with confidence in the underlying baseline. All figures are expressed in USD millions, ensuring consistency with global financial reporting conventions and facilitating direct integration into strategic planning models.
Application and Product Category Landscape
The report maps revenue distribution across hydraulic hoses, air and water hoses, suction and discharge hoses, chemical hoses, and food and beverage hoses, while simultaneously tracking demand intensity across oil and gas, construction and infrastructure, automotive, agriculture, mining, chemicals, and food and beverage applications. By presenting these dimensions as interlocking rather than independent, our analysis reveals how material selection, performance requirements, and end-market purchasing cycles interact to shape revenue concentration and growth velocity within each product and application stream. Readers gain visibility into which categories are structurally positioned for sustained expansion and which face margin compression, substitution risk, or regulatory headwinds.
Geographic Demand Architecture
Market activity spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region, each exhibiting distinct procurement patterns, infrastructure development pacing, and industrial output profiles. Our geographic assessment avoids simplistic ranking exercises in favor of examining how regional industrial structures, trade flows, and local manufacturing capacity interact to produce divergent growth paths. This regional layering enables multinational operators to prioritize market entry timing, distribution investments, and localized product strategies with greater precision.
Competitive Position Mapping and Strategic Posture Assessment
The competitive landscape includes established multinational manufacturers and specialized fabricators whose strategic positioning, product breadth, and regional reach vary considerably. Our analysis profiles organizations including Parker Hannifin Corporation, Gates Corporation, Danfoss, Continental AG, Kuriyama of America, Inc., Flexaust Inc., Southeastern Hose, Inc., and NRP Jones, examining their product portfolios, operational focus areas, and apparent strategic emphasis on fluid transfer, pressure systems, and specialized industrial applications. Rather than providing static company descriptions, we assess how each player's portfolio architecture and market orientation suggest vulnerability to pricing pressure, capacity to capture premium specification opportunities, and likelihood of influencing industry standards adoption.
Supply Chain, Procurement, and Cost Drivers
Recognizing that input costs and logistics realities fundamentally affect commercial outcomes, the report integrates raw material pricing intelligence, production cost considerations, and procurement cycle dynamics into its strategic recommendations. By linking stainless steel and rubber pricing movements to segment margins and product substitution patterns, we equip procurement teams and finance leaders with the context needed to negotiate with suppliers, time purchases, and evaluate make-versus-buy decisions more effectively.
Competitive Dynamics: Concentration, Differentiation, and M&A Potential
Market concentration metrics indicate a moderately fragmented but increasingly competitive environment, with CR3 at 24.6 percent and CR5 at 26.2 percent. These figures signal that while no single entity commands dominant market control, the top tier of suppliers collectively holds meaningful share, and the distance between leading players and the broader tail of manufacturers remains structurally significant. For strategic planners, this concentration profile suggests several actionable implications. First, pricing power is unlikely to be exercised uniformly across the market, meaning that differentiation through application engineering, certification compliance, delivery reliability, and technical support will likely determine which suppliers succeed in capturing premium positions. Second, the moderate concentration leaves room for consolidation, partnership formation, and vertical integration moves that could alter competitive balances over the forecast horizon. Third, smaller and mid-tier fabricators that specialize in custom assemblies, oilfield applications, or niche material configurations may find opportunities to compete on responsiveness and engineering service rather than price alone, particularly as end-users increasingly prioritize specification integrity and operational safety.
The strategic posture of leading and mid-tier players reflects the broader tension between scale economies and specialization. Multinational manufacturers typically compete on portfolio breadth, international distribution reach, and alignment with major industrial standards, while regional or application-focused fabricators often emphasize custom engineering, rapid turnaround, and proximity to specific end markets. Our analysis examines how these strategies are likely to perform as raw material volatility persists and as regulatory updates such as EN 854:2026 raise the baseline for compliance. Companies that have invested in material science capabilities, certified manufacturing processes, and application-specific testing infrastructure are better positioned to defend margins and capture share from less differentiated competitors.
2026 Decision Framework: Translating Market Intelligence into Action
The report is designed to answer the strategic questions that matter most to enterprise decision makers in 2026 and beyond. Rather than offering generic observations, we structure the analysis around actionable decision points.
- Where should procurement and sourcing investments be directed given current raw material pricing, input volatility, and compliance-driven specification requirements?
- Which product categories and application segments present the most attractive risk-adjusted growth exposure over the 2026 to 2032 window, and how should capital allocation reflect those opportunities?
- How do geographic demand patterns affect distribution strategy, local manufacturing decisions, and market entry timing for both incumbent operators and new entrants?
- What competitive vulnerabilities and strengths are embedded in current supplier portfolios, and how should that assessment inform partnership, sourcing, and potential acquisition evaluations?
- In what ways do evolving standards and safety regulations reshape the total cost of ownership calculus for industrial hose systems, and which suppliers are best positioned to support compliance-driven purchasing requirements?
Each of these questions is addressed through integrated quantitative data, qualitative market assessment, and competitive profiling that together provide a coherent basis for strategic planning. Our objective is to enable leaders to move from uncertainty to structured decision making, using evidence that accounts for both near-term operating realities and longer-term structural trends.
Concluding Perspective
The industrial hose market in 2026 is defined by durable growth momentum, material cost complexity, regulatory refinement, and an active competitive landscape that rewards differentiation and technical capability. The trajectory from a 14,352.0 million USD base in 2025 toward an estimated 23,169.0 million USD by 2032 reflects an industry where sustained capital spending, infrastructure development, and fluid handling modernization converge to support demand. Yet beneath these headline figures lies a richer analytical environment, one in which product category dynamics, application-specific demand intensity, regional variation, cost-driven substitution, and competitive positioning collectively determine where value is created and retained. Our full Industrial Hose Market report delivers the detailed segmentation analysis, scenario modeling, competitive profiling, and procurement intelligence required to act on this complexity with confidence. For executives and strategic planners who need more than macro-level summaries, the complete study provides the resolution necessary to inform sourcing strategy, investment prioritization, partnership evaluation, and risk management through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


