



PW Consulting: EQS Market to Hit $195.16B by 2032 with 7.12% CAGR

Navigating the Engineered Quartz Stone Market: Strategic Intelligence for 2026 and Beyond
The global demand for engineered quartz stone (EQS) has transitioned from a niche luxury preference to a mainstream standard in residential and commercial surface solutions. As we move through 2026, industry stakeholders face a complex landscape defined by robust growth trajectories, shifting regulatory frameworks, and intense competitive maneuvering. PW Consulting's latest market research provides a comprehensive navigational chart for executives, investors, and supply chain leaders seeking to capitalize on these dynamics. This executive briefing outlines the strategic value of our analysis, synthesizing historical performance, forward-looking projections, and critical market intelligence to inform high-stakes decision-making.
Market Trajectory: From Recovery to Sustained Expansion
The engineered quartz stone sector has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks revenue performance from 2020 through the base year of 2025, capturing the market's recovery from global supply chain disruptions and its subsequent acceleration. The market valuation has climbed steadily, surpassing the 120 million USD threshold in 2025. This historic performance sets a robust foundation for the forecast period extending through 2032.
Projections indicate a continued upward trajectory, with the market expected to reach valuation levels exceeding 195 million USD by the end of the forecast window. This growth is underpinned by a compound annual growth rate (CAGR) that reflects sustained investment in surface materials across key sectors. For strategic planners, these figures are not merely statistics; they represent the total addressable market expansion that will dictate capacity planning, capital allocation, and geographic focus over the next seven years. Understanding the inflection points within this timeline allows organizations to time their market entry, product launches, and scaling initiatives with precision.
Structural Segmentation: Identifying High-Yield Opportunities
A superficial view of the EQS market obscures the nuanced value pools that drive profitability. Our research deconstructs the market across critical dimensions, providing leaders with the granularity needed to prioritize resource deployment. The analysis examines product types, application verticals, and regional performance, revealing where demand is most concentrated and where growth vectors are emerging.
Within product classifications, the market is dominated by specific formats that align with prevailing construction and renovation trends. The research details the revenue contribution and growth potential of quartz slabs, tiles, and other emerging formats. By mapping the adoption curves of these product types against buyer preferences in different end-use scenarios, firms can refine their manufacturing mixes and inventory strategies. Similarly, the application landscape is dissected to highlight the primary drivers of consumption. While certain applications remain the predominant revenue generators, the research identifies ancillary segments that offer diversification benefits and emerging opportunities for product innovation.
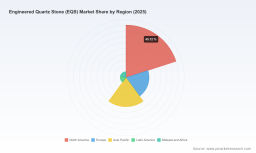
Regional analysis is equally critical. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct demand drivers, regulatory environments, and competitive intensities. For instance, mature markets may offer stability and high per-capita consumption, while developing regions may present higher growth rates driven by urbanization and infrastructure development. Our segmentation analysis equips clients with the insights necessary to tailor regional go-to-market strategies, balancing risk and reward across their global footprint.
Engineered Quartz Stone (EQS) Market
Competitive Landscape: Dynamics Among Key Players
The EQS market features a mix of established global giants and agile regional manufacturers, creating a competitive environment where differentiation is paramount. PW Consulting's report profiles the strategies, capabilities, and market positions of leading entities that are shaping industry standards. Understanding the moves of these key players is essential for benchmarking, partnership evaluation, and competitive positioning.
In North America, family-owned and domestic manufacturers are leveraging local production and strong brand equity to capture market share. Companies such as Cambria have built reputations around high-performance slabs and lifetime warranties, appealing to consumers and contractors who prioritize durability and trust. Similarly, MSI Surfaces has expanded its portfolio significantly, offering a wide array of styles produced through advanced machinery and patent-protected processes at its domestic facilities. These firms illustrate the importance of manufacturing proximity and design variety in securing customer loyalty.
On the global stage, pioneer brands continue to drive innovation in design and sustainability. Caesarstone, a longstanding leader since the late 1980s, maintains a strong presence through continuous product development and adaptation to regional demands. Recent capacity expansions by Caesarstone highlight the strategic focus on supporting growing demand in residential and commercial construction across major markets. Concurrently, the company has responded to industry pressures regarding worker safety by launching innovative quartz surfaces with reduced crystalline silica content, signaling a proactive approach to regulatory compliance and product safety.
European and international players are also advancing the market through technological breakthroughs and global distribution networks. The Cosentino Group stands out as a global leader, with its Silestone brand introducing HybriQ+ technology designed to lower crystalline silica content while maintaining aesthetic and performance standards. VICOSTONE, based in Turkey, has established itself as a leading manufacturer of premium quartz products for residential and commercial use, leveraging extensive collections to meet diverse design requirements. In Asia, manufacturers are expanding their reach and production capabilities. Hanwha L&C and LG Hausys represent major South Korean conglomerates producing high-quality engineered stone surfaces, with Hanwha operating facilities in both South Korea and the United States to serve local and export markets. In India, Techstone Quartz operates as an integrated manufacturer and exporter, focusing on high-quality slabs and prefabricated countertops. Meanwhile, LT Quartz in China specializes in professional quartz surfacing production and marketing, catering to a broad spectrum of applications.
Recent developments underscore the intensity of capacity and product strategy adjustments. Pokarna Limited, for example, announced significant investments to expand its engineered quartz slab production capacity, driven by rising export demand from North American and European construction sectors. These expansions, including new production lines operational in early 2026, reflect the industry's response to market growth and the strategic importance of scaling supply to meet international orders. Our competitive analysis synthesizes these developments to reveal trends in M&A activity, capacity investments, product launches, and sustainability initiatives, providing a holistic view of how the competitive battleground is evolving.
Regulatory and Operational Dynamics: Risk and Adaptation
Market growth cannot be decoupled from the regulatory and operational environment. The EQS industry is currently navigating a period of heightened scrutiny regarding health and safety, particularly concerning crystalline silica exposure during fabrication and installation. Regulatory bodies in key markets are advancing rulemaking and enforcement actions that could fundamentally alter manufacturing processes, product specifications, and liability landscapes.
In California, regulators have moved to prohibit the fabrication of artificial stone countertops with more than one percent crystalline silica, a measure driven by concerns over silicosis cases among workers. Cal/OSHA has tightened silica safety requirements and continues to enforce emergency temporary standards, compelling manufacturers and fabricators to adapt their operations. Australia has taken an even more stringent approach, banning the manufacture, supply, processing, and installation of engineered stone benchtops, panels, and slabs effective mid-2024, with prohibitions on imports added in early 2025. These regulatory shifts create both challenges and opportunities. Companies that proactively develop low-silica or silica-compliant products can turn compliance into a competitive advantage, securing contracts in markets where safety certifications are becoming a prerequisite for doing business.
Beyond regulation, cost dynamics remain a critical factor. Fluctuations in the prices of essential raw materials, such as polyester resins and quartz aggregates, directly impact profit margins. Our report analyzes these cost drivers and their volatility, offering insights into supply chain resilience and pricing strategies. Leaders must understand how material cost fluctuations interact with regional demand and competitive pricing to maintain margin integrity. The research provides frameworks for monitoring input costs, hedging strategies, and optimizing procurement to mitigate margin erosion.
Strategic Frameworks for 2026 Decision-Making
PW Consulting's Engineered Quartz Stone Market report is designed as a practical tool for execution, not just a repository of data. The study integrates quantitative forecasts with qualitative insights to support specific strategic actions. Clients will find detailed 분석의 of market drivers, restraints, and opportunities, enabling them to validate investment theses and identify whitespace. The report includes comprehensive profiles of key companies, analyzing their product portfolios, geographic reach, recent developments, and strategic positioning. This allows competitors to benchmark against industry leaders and new entrants to assess market barriers.
Furthermore, the analysis covers the entire value chain, from raw material sourcing to manufacturing technologies, distribution channels, and end-user preferences. By mapping the value chain, organizations can identify bottlenecks, partnership opportunities, and areas for vertical integration or diversification. The report also examines the impact of macroeconomic factors, construction trends, and consumer behavior shifts on demand patterns. For example, the growing emphasis on sustainable building materials and health-conscious design choices is influencing product development and marketing narratives. Our research highlights how EQS products can be positioned to align with these broader trends, such as through innovations in low-silica content, recycled content integration, and energy-efficient manufacturing processes.
The segmentation data provided in the report allows for precise targeting. Whether a firm is focusing on the dominant application segments or exploring niche applications with high growth potential, the research supports data-driven segmentation strategies. Regional breakdowns enable the calibration of market entry strategies, resource allocation, and risk management plans tailored to local conditions. The inclusion of recent industry developments ensures that the intelligence is current and actionable, capturing the latest capacity expansions, product launches, and regulatory updates that could impact business outcomes.
Engineered Stone Market
Conclusion: The Imperative for Comprehensive Intelligence
As the engineered quartz stone market accelerates toward the 2030s, the margin for strategic error narrows. The convergence of robust demand growth, evolving regulatory requirements, cost volatility, and intense competition demands a holistic and up-to-date understanding of the industry. PW Consulting's market research delivers this intelligence, combining rigorous data analysis with deep industry expertise. By revealing the underlying dynamics of market segmentation, competitive behavior, and operational risks, the report empowers stakeholders to make informed decisions that drive sustainable growth. We invite industry leaders to leverage this comprehensive analysis to navigate the opportunities and challenges of the EQS market with confidence, ensuring their strategies are aligned with the realities of 2026 and the trajectory toward 2032.
For detailed analysis of this topic, please visit the official page: Engineered Quartz Stone (EQS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


