



PW Consulting: Pressure Sensors Market to Hit $22.88B by 2032 at 6.5% CAGR

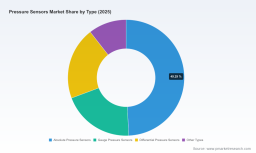
Strategic Intelligence for the Pressure Sensors Market: Navigating 2026 and Beyond
Executive Overview
The global pressure sensors market stands at a critical inflection point as we move through 2026. Following a trajectory of consistent expansion from 2020 through 2025, the sector has matured into a complex landscape where technological differentiation, supply chain resilience, and regional dynamics converge to shape competitive outcomes. Our latest market research provides decision-makers with a comprehensive, data-backed roadmap to navigate this evolving environment, offering actionable intelligence that extends far beyond superficial market summaries.
Understanding the pressure sensors market requires more than tracking headline numbers. It demands a granular appreciation of how type-specific demand shifts, application-driven procurement cycles, regional adoption patterns, and competitive maneuvers interact to create both risk and opportunity. This report is designed for executives, product strategists, procurement leaders, and investors who require precision intelligence to allocate capital, prioritize R&D pipelines, and position portfolios against structural market shifts.
While broader market indicators provide essential context for strategic planning, the true value of this research lies in its operational depth. We examine the underlying drivers that will determine which organizations capture disproportionate value in the years ahead, and which risk being displaced by more agile, technologically adept competitors.
Medical Pressure Sensors Market
Macro Trajectory and Strategic Context
The pressure sensors market has demonstrated robust growth over the past half-decade, with total market revenue expanding from approximately 10.8 billion USD in 2020 to an estimated 14.75 billion USD by 2025. This expansion reflects sustained demand across industrial automation, automotive electrification, medical device innovation, and infrastructure modernization. Looking forward, the market is projected to continue its upward trajectory through the 2026 to 2032 forecast period, with a compound annual growth rate of 6.5 percent. By 2032, total market revenue is anticipated to reach 22.88 billion USD, underscoring the sector's long-term structural momentum.
Such macroeconomic visibility is valuable, but it is only the starting point for informed strategy. Growth rates mask significant variation in how different sensor categories perform, how regional markets evolve at divergent paces, and how application-specific procurement behaviors reshape purchasing patterns. Executives who rely solely on aggregate forecasts risk misallocating resources or misjudging the timing of market entry and exit decisions. Our research dissects these layers of complexity, enabling leaders to build plans grounded in segment-level reality rather than top-line approximation.
Pressure Sensors Market
The forecast period also coincides with a phase of heightened industry volatility. Supply chain reconfiguration, raw material cost pressures, regulatory certification burdens, and tariff-driven production economics are simultaneously reshaping cost structures and competitive positioning. Organizations that anticipate these dynamics and embed flexibility into their operating models will be better equipped to preserve margins and accelerate time-to-market, even as the broader environment grows more challenging.
Key Industry Dynamics Shaping 2026
-
Reciprocal tariff policies across major economies have introduced new cost pressures and forced supply chain reconfiguration decisions for pressure sensor manufacturers. Producers must now weigh the trade-offs between localized production, diversified sourcing, and inventory strategy in ways that directly affect unit economics and delivery reliability.
-
Silicon wafer availability and broader semiconductor material supply constraints continue to influence production timelines for piezoresistive pressure sensor manufacturing. These disruptions ripple through component lead times, capacity planning, and qualification cycles, particularly for organizations dependent on high-volume MEMS fabrication.
-
Stainless steel and ceramic pressure sensor cells face mounting price erosion and margin compression as elevated material and labor costs intersect with high-volume production demands. This environment rewards manufacturers that can optimize bill-of-materials efficiency, streamline assembly processes, and differentiate through performance rather than commodity cost alone.
-
Hazardous area certifications such as ATEX and IECEx add 20 to 30 percent to product development costs for industrial pressure sensors. For companies targeting process industries, oil and gas, and utility applications, certification strategy and time-to-certification have become critical determinants of commercial viability and competitive reach.
These dynamics do not affect every segment equally. Some categories benefit from resilience in high-precision or specialized applications, while others experience intensified price competition as commoditized solutions encounter cost headwinds. The research unpacks which segments are most exposed, which are insulated by technical barriers, and how leading players are adjusting their portfolios to navigate the new cost and compliance reality.
Competitive Landscape and Strategic Positioning
The pressure sensors market features a diverse field of established multinational manufacturers, specialized engineering firms, and technology-focused innovators. Competitive advantage in this environment is increasingly defined not by scale alone, but by the ability to combine material science expertise, packaging innovation, application-specific calibration, and compliance readiness into solutions that reduce total cost of ownership for end users.
Several core companies illustrate the range of strategic approaches shaping the market. Honeywell International Inc. continues to strengthen its industrial, transportation, and HVAC portfolio through heavy-duty pressure sensors, board-mount solutions such as the ABP series, and high-pressure transducers leveraging piezoresistive technology. Its recent introduction of a 13MM pressure sensor tailored for cleanroom semiconductor environments highlights how targeted product development can open doors in highly specialized, standards-driven applications.
TE Connectivity Ltd. maintains a broad technology footprint spanning board-level devices, media-isolated sensors, and pressure transducers built on piezoresistive MEMS and silicon strain gauge architectures. Its ability to serve medical, industrial, automotive, and aerospace sectors with pressure ranges spanning from ultra-low to extremely high values demonstrates the commercial power of versatile platform technologies. Merit Sensor complements this landscape with surface-mount piezoresistive sensors and modules focused on ultra-low-pressure differential and gage measurement for industrial use, reflecting a strategy centered on precision in demanding control environments.
In the industrial and utility segment, ABB Ltd. has expanded its offering with a new P-Series pressure transmitter portfolio designed for high-precision measurement, reinforcing its emphasis on robust, chemically resistant, and ingress-protected devices. Gems Sensors & Controls, Setra Systems, Ashcroft Inc., and SSI Technologies each contribute ruggedized designs and application-focused engineering, targeting demanding fluid measurement, HVAC, material handling, and high-accuracy industrial environments. These firms illustrate how physical durability, environmental resilience, and tailored form factors remain decisive in sectors where failure costs are high.
High-temperature and extreme-environment capability represents a distinct competitive frontier. Sentek Instrument has advanced its position through the NovaPT-E sapphire pressure sensor, which has demonstrated reliable operation at pulse temperatures up to 1500 degrees Celsius and demodulation at frequencies up to 60 kHz. Its recent contract win to supply high-temperature sensors to a major jet engine manufacturer for applications above 1000 degrees Celsius underscores the growing importance of extreme-environment measurement in aerospace and advanced propulsion systems.
On the component and integration side, Amphenol Corporation, Microsensor Corporation, MPI Melt Pressure, and several semiconductor-centric players contribute specialized capabilities ranging from leadless miniature packages to custom melt-pressure measurement solutions. Meanwhile, Bosch Sensortec, NXP Semiconductors, and STMicroelectronics embed pressure sensing functionality within broader IC and MEMS platforms, particularly for automotive and consumer applications. This segmentation between discrete sensor specialists and integrated semiconductor suppliers creates distinct value chains, each with its own cost structure, innovation cadence, and customer engagement model.
Market concentration remains moderate, with the top three firms and top five firms collectively holding meaningful but not dominant shares of total revenue. This structure suggests that while scale advantages and distribution reach matter, there is substantial room for specialized players to win on performance, certification, customization, and service. The research evaluates how these concentration patterns are likely to evolve as consolidation, partnerships, and technology platform strategies reshape competitive boundaries.
Report Scope and Actionable Intelligence
This market research is built for operational decision-making. It moves beyond descriptive analysis to deliver the kind of structured intelligence that product leaders, strategy teams, and commercial executives can translate directly into planning and execution. The report's content is designed to answer the questions that matter most when allocating resources and defining market strategy in 2026 and beyond.
What the Report Covers
-
Market sizing and forecast architecture across the full 2020 to 2032 timeline, with a focused 2026 to 2032 forecast window that supports near-term budget planning and longer-term portfolio strategy.
-
Detailed segmentation analysis by type, application, and region, enabling readers to identify where demand is strengthening, where saturation risk is rising, and where white space remains for differentiated offerings.
-
Competitive profiling of major participants, including technology positioning, product capabilities, geographic reach, and recent strategic actions that signal where each company is placing its bets.
-
Recent industry developments, including product launches, contract wins, and milestone achievements that illustrate the pace of innovation and the practical direction of market demand.
-
Regulatory, certification, and compliance considerations that affect development timelines, cost structures, and market access in industrial, medical, and hazardous-area applications.
-
Supply chain and input-cost dynamics, with attention to materials, semiconductor dependencies, labor economics, and tariff exposure that influence margin outcomes and sourcing strategy.
-
Strategic frameworks for interpreting segment attractiveness, prioritizing investment, and aligning product roadmaps with the most resilient demand vectors.
Who Should Use This Research
-
Corporate strategy and business development teams seeking to assess market entry, expansion, partnership, or acquisition opportunities.
-
Product managers and R&D leaders responsible for sensor portfolio planning, feature prioritization, and technology roadmapping.
- Procurement and supply chain executives evaluating supplier options, cost risk, and resilience strategies in a shifting materials and tariff environment.
-
Investors and market analysts requiring structured, defensible market intelligence to support valuation, due diligence, and sector monitoring.
-
Engineering and operations leaders in end-user industries who need to understand sensor capability trends, compliance requirements, and integration implications.
Why This Research Matters for 2026 Decisions
The pressure sensors market in 2026 is not simply larger than it was five years ago; it is more structurally complex. Growth persists, but the sources of growth are spreading across different sensor types, applications, and regions at uneven rates. At the same time, cost pressures from materials, labor, tariffs, and certification requirements are compressing the economics of commoditized segments while elevating the strategic importance of performance, reliability, and application-specific engineering.
In this environment, effective decision-making depends on understanding not just where the market is going, but why it is going there and what that implies for competitive positioning. A forecast number can inform revenue targets, but only a detailed segmentation and competitive analysis can reveal which product lines deserve investment, which customer segments warrant deeper engagement, and which supply chain assumptions need to be stress-tested.
Our research is designed to provide exactly that level of clarity. It gives executives the evidence needed to challenge assumptions, prioritize initiatives, and reduce uncertainty in planning cycles. By linking market size and growth trajectories to segment-level mechanics and real-world competitive moves, the report helps organizations align strategy with the realities of demand, cost, and technology development.
The complete analysis contains the detailed segmentation data, company-by-company competitive evaluation, and scenario-sensitive interpretation needed to support high-stakes decisions. Readers who require the full depth of market sizing, segment breakdowns, and strategic benchmarking are encouraged to access the complete report through our source page, where the full intelligence package is available for immediate use in strategic planning.
Conclusion
The pressure sensors market offers substantial opportunity for organizations that can combine technological credibility, supply chain discipline, and segment-focused strategy. With sustained growth projected through 2032 and a competitive landscape that rewards differentiation, the window for proactive positioning is open, but it is not unlimited. Tariff exposure, material constraints, certification costs, and evolving end-user requirements will continue to test companies that rely on generic product strategies or rigid operating models.
This report provides the strategic foundation needed to act with confidence in 2026. By translating market-scale trends into operational insight, it enables leaders to make sharper investment decisions, build more resilient supply strategies, and target the applications and regions where the next wave of value creation will emerge. The full research details are available through our source page for teams ready to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Pressure Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


