



Smart Doorbell Market to Hit $1.88B by 2032 at 17.9% CAGR, Says PW Consulting Report

Navigating the Smart Doorbell Market: Strategic Intelligence for 2026 and Beyond
The smart doorbell market has evolved from a niche accessory into a cornerstone of the broader connected home and physical security ecosystem. As we move deeper into 2026, enterprises, investors, and technology strategists must look beyond surface-level adoption narratives and understand the structural forces shaping revenue trajectories, competitive positioning, and regulatory readiness. Our latest market research delivers precisely that analytical architecture. Built on a rigorous historical foundation spanning 2020 through 2025 and extended through a detailed forecast window to 2032, this study transforms fragmented industry signals into a cohesive decision-making framework. For executive teams navigating product roadmaps, channel strategy, or M&A evaluation, the report functions as both a compass and a calibration tool.
Macro Trajectory and the 2026 Inflection Point
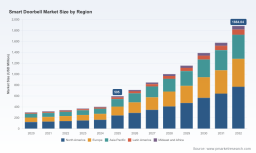
The market's expansion over the past half-decade demonstrates a consistent upward arc, but the true strategic significance lies in how momentum accelerates rather than merely sustains. Historical revenue climbed steadily from approximately $300 million in 2020 to $401.26 million in 2024, reflecting mature consumer electronics adoption curves and incremental smart home penetration. The 2025 baseline of $595 million marks a pronounced step-change, signaling that market maturation has triggered a new growth regime rather than a plateau. Looking ahead, our forecast maps a clear trajectory toward $710.07 million in 2026, accelerating through $1.005 billion around 2028, and ultimately approaching $1.884 billion by 2032.
Underpinning this expansion is a forecasted compound annual growth rate of 17.9 percent across the 2026 to 2032 horizon. For strategic planners, this figure is not merely a growth statistic; it is a timing signal. An expansion rate at this level implies that early-mover advantages in ecosystem integration, manufacturing scale, and regional compliance infrastructure will compound rapidly. Enterprises that treat 2026 as a baseline planning year rather than a continuation of prior-year assumptions will find themselves either capturing disproportionate share or scrambling to retrofit capabilities under tighter margin conditions.
Competitive Architecture: Differentiating in a Crowded Field
The smart doorbell landscape is defined by a diverse set of players, each anchoring their offerings to distinct technological philosophies and ecosystem strategies. Analyzing these positions is essential because competitive advantage in this category no longer stems from hardware specifications alone; it emerges from how product architecture aligns with customer retention models, subscription economics, and interoperability expectations.
Amazon-owned Ring continues to leverage its dominant consumer footprint through both battery-powered and wired video doorbells, emphasizing two-way audio, package detection, and seamless integration within the Amazon retail and services ecosystem. Its scale and brand recognition create a persistent reference point against which rivals measure market entry and feature parity. Meanwhile, TP-Link has pushed differentiation through its Tapo series, offering dual-powered 2K+ video doorbells with AI detection while explicitly addressing a growing consumer preference for no-subscription cloud options.
Ubiquiti Inc. occupies a different strategic niche. The UniFi G4 Doorbell Pro targets prosumer and integrated security environments with advanced package detection, an integrated chime, and tight coupling with the UniFi Protect ecosystem. This positioning reflects a broader market split between mass-market plug-and-play solutions and infrastructure-oriented deployments that value centralized management. REOLINK follows a similar practical differentiation path, offering WiFi and PoE models with 2K+ resolution, local NVR storage, and AI features that eliminate recurring subscription dependencies.
In the residential and smart-home automation segment, Lumi United Technology Co., Ltd. has advanced its Aqara Video Doorbell G4 with facial recognition capabilities, local storage architecture, and HomeKit Secure Video support. This aligns with a consumer base that prioritizes privacy, interoperability within Apple-centric households, and reduced reliance on third-party cloud infrastructure. Anker Innovations Co., Ltd. has pursued a complementary strategy through its eufy Video Doorbell E340 and related models, featuring a dual-camera setup and local storage to appeal to users seeking broader field coverage without recurring fees.
Amazon's Blink brand continues to extend its reach with an emphasis on long battery life, two-way talk, and Alexa integration, while SimpliSafe, Inc. connects its Video Doorbell Pro to professional monitoring and no-contract security system compatibility, effectively bridging DIY smart home devices with traditional security service expectations. Arlo Technologies, Inc. rounds out this competitive field with its 2K Video Doorbell emphasizing wide-angle lens design, color night vision, and Arlo Secure cloud storage.
What makes this competitive mosaic strategically significant is that rivalry no longer operates along a single axis. Differentiation now spans power architecture, storage philosophy, ecosystem lock-in versus openness, professional monitoring compatibility, and privacy-conscious design. The winners in 2026 and beyond will be those capable of aligning product architecture with a clearly defined customer segment rather than attempting to dominate across all dimensions simultaneously.
Market Dynamics: Regulation, Supply Chain, and the Compliance Premium
The operational environment surrounding smart doorbells is increasingly shaped by regulatory and structural forces that reward preparedness and penalize reactive design. Spectrum management remains a foundational consideration, as FCC regulation continues to govern spectrum allocation for Wi-Fi and Bluetooth in smart doorbell devices, requiring manufacturers to prevent interference across the 2.4 GHz and 5 GHz bands. For hardware engineering and product certification teams, this is not a background detail; it is a design constraint that directly affects time-to-market, regional deployment flexibility, and interoperability performance.
Doorbell Market
Data protection requirements have become equally central to commercial strategy. GDPR and data sovereignty laws now require end-to-end encryption and local storage options for smart doorbell video feeds within the European Union. This regulatory posture shifts the competitive calculus for vendors targeting European customers. Companies that have embedded privacy-by-design architectures and local storage pathways into their product roadmaps can position those capabilities as market access enablers, whereas those retrofitting compliance under deadline pressure face both technical and reputational friction.
Cybersecurity management standards further reinforce this compliance premium. The widespread adoption of ISO/IEC 27001 standards across smart home devices, including video doorbells, signals that enterprise-grade security governance is becoming table stakes rather than a differentiator reserved for specialized verticals. For market participants, this means that product security, certification readiness, and transparent data handling are increasingly intertwined with brand trust and channel acceptability.
On the manufacturing and cost side, sector analysis indicates that assembly and testing labor costs for smart doorbell hardware are elevated in regions with skilled electronics manufacturing supply chains. This dynamic has strategic implications for sourcing decisions, margin planning, and product localization. Companies must weigh the trade-offs between manufacturing proximity, labor cost structures, quality consistency, and logistics efficiency, especially as competition intensifies and pricing pressure increases in the mass-market segment.
A recent product-launch signal further illustrates how these dynamics play out in real time. In May 2026, Blink debuted a second-generation video doorbell featuring an expanded field of view and enhanced person detection. This release demonstrates how incumbents continue to iterate on core detection quality and visual coverage to defend share, while also reflecting the broader industry push toward more accurate on-device intelligence. For competitors, such launches are both an operational benchmark and a reminder that feature escalation alone will not sustain differentiation without clear segmentation and ecosystem alignment.
What the Full Research Delivers: Operational Intelligence, Not Just Forecasts
A market summary can establish direction, but enterprise decision-making requires structured, actionable detail. Our Smart Doorbell Market research is designed to convert high-level trajectory into implementable intelligence across product, commercial, and risk functions. The report maps historical performance and forward-looking forecasts within a consistent methodological framework, allowing readers to validate growth assumptions against segmented demand drivers, regional adoption patterns, and application-specific purchasing behavior.
Beyond aggregate sizing, the study dissects how the market is structured across type-based and application-based demand, giving strategists visibility into where wired and wireless architectures are gaining traction and how residential versus commercial use cases shape product requirements, pricing tolerance, and channel expectations. Regional demand distribution is similarly examined to identify where growth concentration, competitive intensity, and compliance environments diverge, enabling more precise go-to-market prioritization rather than broad, undifferentiated global assumptions.
The report also includes competitive profiling that goes beyond corporate descriptions. It situates each key player within a strategic context, connecting product features, ecosystem integration, storage and subscription philosophy, and monitoring or security compatibility to the segments they are best positioned to serve. This approach allows business leaders to benchmark their own product strategy against peer positioning, identify white-space opportunities, and anticipate where competitive pressure is likely to intensify.
Equally important, the research integrates regulatory and operational dynamics into the market narrative rather than treating them as peripheral footnotes. By examining the interplay between spectrum regulation, data sovereignty expectations, cybersecurity standards, and manufacturing cost structures, the study helps organizations assess readiness across multiple dimensions simultaneously. For product teams, this means clearer visibility into design constraints and certification pathways. For commercial teams, it means more realistic margin modeling and market-entry sequencing. For leadership, it means a consolidated view of where operational risk and strategic opportunity converge.
Why This Research Matters for 2026 Decision-Making
Markets that expand at a double-digit CAGR do not reward passive observation. They reward organizations that can convert structural growth into targeted execution. In the smart doorbell category, 2026 sits at a point where historical momentum, regulatory maturation, and competitive fragmentation intersect. The companies that navigate this inflection successfully will be those that treat product strategy, compliance architecture, and segmentation discipline as interconnected rather than sequential concerns.
Our research is built for that challenge. It is intended for executives who need to evaluate whether to deepen existing product lines, enter adjacent segments, restructure supply and cost assumptions, or reposition against ecosystem-driven competitors. It is also intended for investors and advisors who require a defensible view of where demand is concentrating, which competitive models are proving durable, and which operational hurdles will separate scalable players from those constrained by compliance gaps or misaligned product philosophy.
Smart Doorbell Market
The complete report provides the segmented data, competitive benchmarking, regional breakdowns, and forward-looking scenario structure necessary to move from strategic intent to operational plan. If your team is preparing for 2026 planning cycles, channel allocation, product roadmap prioritization, or competitive response planning, the full study offers the granularity required to make those decisions with confidence.
The market trajectory is clear. The strategic question is how precisely your organization intends to meet it.
For detailed analysis of this topic, please visit the official page: Smart Doorbell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


