



PW Consulting: Car Amplifier Market Hits $386.3M in 2025, Forecast 7% CAGR to $620.9M by 2032

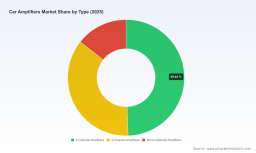
Car Amplifiers Market 2026-2032: Strategic Intelligence for Automotive Audio Decision-Makers
The automotive audio sector is undergoing a structural transformation driven by electrification, premiumization, and standardized performance measurement. For executives evaluating capital allocation, product roadmaps, or supply chain resilience, the Car Amplifiers Market demands a clear-eyed view of where growth premiums are forming and how competitive dynamics are consolidating. Our latest market research publication delivers a comprehensive, data-grounded assessment of this landscape, translating historical momentum and forward-looking projections into actionable intelligence for 2026 and beyond.
Over the 2020-2025 historical window, the global car amplifiers market expanded from approximately 302.5 million USD to 386.3 million USD, reflecting a compound trajectory that has consistently outpaced broader automotive accessory growth. This momentum is projected to sustain through the 2026-2032 forecast horizon, with the market advancing toward a six-hundred-million-dollar revenue threshold by the end of the period. The forecast implies a steady CAGR of 7.0 percent, signaling that amplifier demand will remain resilient even as vehicle architectures evolve and consumer spending patterns recalibrate. For strategy teams, this trajectory is not merely a top-line projection; it is a signal that underlying demand drivers—enhanced cabin acoustics, integrated multimedia systems, and the aftermarket pursuit of differentiated audio experiences—continue to compound.
The strategic value of this research lies in its ability to convert macro growth into operational clarity. While headline figures establish the scale of opportunity, the real decision-making leverage emerges when leaders understand how that growth distributes across amplifier architectures, deployment channels, and regional ecosystems. The report maps these dimensions with precision, enabling organizations to calibrate portfolio focus, pricing strategy, and geographic prioritization without relying on fragmented anecdote or outdated benchmarks. Readers will find that the analysis deliberately isolates structural drivers rather than surface-level fluctuations, ensuring that resource allocation decisions are anchored in durable market mechanics.
Report Scope and Operational Utility
This publication is engineered for practitioners who need more than a market snapshot. It functions as a planning instrument, aligning commercial strategy with technical and regulatory realities that shape the amplifier competitive arena. The report architecture is built around several interlocking components that translate directly into business decision support.
- Comprehensive market sizing and forecast modeling that extends from the 2020 baseline through 2032, providing continuity between observed historical performance and projected market expansion.
- Granular segmentation analysis covering amplifier types, application pathways, and regional demand structures, allowing stakeholders to identify where volume concentration and value premiums diverge.
- Competitive positioning frameworks that evaluate leading manufacturers across product philosophy, channel integration, and innovation cadence, rather than relying on generic brand recognition.
- Regulatory and standards context that clarifies how measurement protocols and certification benchmarks influence performance claims, buyer trust, and competitive differentiation.
- Supply chain and production dynamics that detail manufacturing footprints, labor intensity, and integration patterns affecting cost structures and time-to-market.
- Recent corporate developments, including product catalog updates, trade show showcases, and technology unveilings, offering near-real-time signals on where incumbents are directing engineering and marketing energy.
Each section is designed to feed directly into strategic workstreams such as go-to-market planning, M&A screening, partnership evaluation, and portfolio rebalancing. By embedding macro and micro perspectives within a unified analytical structure, the report reduces the friction between market intelligence and execution planning.
Competitive Landscape: Concentration, Capabilities, and Positioning Signals
The car amplifiers market is characterized by a pronounced concentration of share among established audio and automotive electronics players. The top three firms collectively account for 62.0 percent of market revenue, while the top five extend that share to 75.0 percent. For strategic planners, this concentration pattern matters because it shapes pricing power, channel access, and the feasibility of disruptive entry. It also indicates that innovation leadership and brand equity remain highly correlated with scale advantages in component sourcing, testing infrastructure, and OEM integration relationships.
Incumbents span a diverse set of corporate lineages, from dedicated audio specialists to global consumer electronics groups with automotive divisions. JL Audio, headquartered in Miramar, Florida, anchors its offering in premium car audio amplifiers and extends into marine-rated models that support vehicle integration scenarios where environmental durability intersects with acoustic performance. Rockford Fosgate, based in Tempe, Arizona, emphasizes high-performance amplifiers and mobile audio systems designed for demanding aftermarket and automotive applications. Kicker, operating from Stillwater, Oklahoma, delivers high-performance car audio amplifiers and vehicle-specific audio solutions that align closely with targeted retrofit and performance upgrade segments.
The Japanese cohort—Alpine, Clarion, Kenwood, Pioneer, and Sony—maintains a strong presence across both aftermarket and OEM channels, with product philosophies that blend in-dash integration, amplifier architecture, and cabin audio system design. Alpine and Pioneer, for example, continue to position amplifiers as part of broader vehicle audio ecosystems, while Clarion and Kenwood emphasize compatibility and integration flexibility for both installed and replacement use cases. Sony contributes premium-grade amplifier models intended for automotive audio systems where brand perception and acoustic refinement intersect.
European premiumization efforts are represented by Audison in Italy, which focuses on premium DSP car amplifiers and audio processors that target reference-level performance and advanced signal processing. This emphasis on digital signal processing reflects a broader industry movement in which amplifier value is increasingly tied to tuning capability, integration intelligence, and acoustic customization rather than raw power output alone. On the OEM and luxury integration side, Harman, based in the United States, extends its amplifier footprint through Harman Kardon and Infinity brand portfolios for both OEM and aftermarket vehicles. Bose similarly concentrates on OEM car audio amplifiers embedded within vehicle sound systems, where performance is engineered around manufacturer-specific cabin acoustics and system constraints. Yamaha rounds out the competitive field with amplifier offerings for automotive and OEM applications, reinforcing the breadth of participating lineages.
Strategic observers should note that competitive differentiation in this market is not simply a function of wattage or price point. It increasingly depends on verified performance claims, integration readiness, system-level tuning expertise, and the ability to serve both factory-installed and aftermarket ecosystems. Recent corporate activity underscores this dynamic. In April 2026, Audison released its 2026 catalog, providing detailed documentation of updated technologies, integration solutions, and reference-level audio performance for modern car audio systems. That release was followed in May 2026 by Audison’s participation in Motor Valley Fest in Modena, where the company showcased premium sound systems on a Ferrari 360 Modena demonstration vehicle, combining exclusive listening sessions with a live discussion on lifestyle mobility. These events signal a deliberate emphasis on experiential positioning and high-end integration narratives.
Around the same period, Rockford Fosgate used SEMA to unveil a new amplifier positioned as among the most powerful car audio amplifiers ever produced for aftermarket 12V applications. This showcase highlights the continued relevance of performance escalation in the aftermarket segment, where enthusiasts and installers seek demonstrable gains in output, thermal management, and system reliability. Taken together, these developments illustrate a market in which premium audio specialists and performance-oriented brands are actively redefining the ceiling of what consumers and integrators expect from an amplifier subsystem.
Market Dynamics: Standards, Certification, and Structural Forces
Regulatory conventions and measurement standards have become increasingly consequential in shaping buyer confidence and competitive signaling. The Consumer Technology Association approved the updated CEA-2006 standard for testing and measurement methods of mobile audio amplifiers, and voluntary compliance remains a relevant benchmark across the industry. The standard specifies uniform testing at 14.4 volts into a 4-ohm impedance at 1 percent THD plus noise, with a frequency range of 20 Hz to 20,000 Hz for general-purpose car amplifiers. For manufacturers and buyers alike, this framework helps anchor RMS power ratings and signal-to-noise ratios in a comparable format, reducing ambiguity in product evaluation and making performance claims more defensible across channel touchpoints.
Certification has emerged as an additional lever for differentiating credible performance. Rockford Fosgate became the first company to achieve Klippel Verified certification for an amplifier, a milestone that supports verified power handling and performance in car audio products. This type of verification matters strategically because it ties engineering claims to independent measurement methodology, giving integrators, retailers, and end users a clearer basis for evaluating product integrity. As the market grows, such certification pathways may increasingly influence purchasing decisions in segments where acoustic expectations and system reliability carry premium value.
Beyond standards and certification, structural production dynamics continue to influence cost architecture and scaling capacity. Regional manufacturing footprints remain important, with significant labor deployment in facilities that produce car amplifiers and related automotive audio systems. For instance, Chinese manufacturing operations supporting Harman’s automotive audio production reportedly employ more than 1,200 workers at a Suzhou plant, highlighting the scale of labor-intensive assembly and integration work that underpins certain supply chains. This dimension is particularly relevant for organizations assessing lead-time stability, cost competitiveness, and exposure to regional production shifts.
Market structure also reflects a clear divergence between OEM installation and aftermarket replacement pathways. The OEM axis is tightly linked to vehicle program cycles, manufacturer brand partnerships, and system-level audio integration, while the aftermarket axis is shaped by installer networks, enthusiast demand, retrofit compatibility, and performance expectations. The interplay between these pathways defines how amplifiers move through the market and where competitive advantage is most durable. Organizations evaluating entry, expansion, or partnership opportunities must account for the fact that these channels operate with distinct purchasing logic, margin profiles, and performance assurance requirements.
Guitar Amplifier Market
Why This Research Matters for 2026 Decision-Making
The forecast period beginning in 2026 presents both opportunity and uncertainty. Demand is expected to keep expanding, but the distribution of that growth will not be uniform across segments, geographies, or product categories. Organizations that treat the car amplifiers market as a monolithic category risk misallocating resources, misreading channel priorities, or underestimating the importance of verified performance and integration readiness. Our report is designed to counter those risks by offering a structured, evidence-based view of where value is accumulating and how the competitive field is evolving.
Car Amplifiers Market
For strategy teams, the practical payoff is threefold. First, the report supports portfolio decisions by clarifying how amplifier types and application pathways interact with demand patterns, enabling sharper segmentation focus without overexposing the organization to low-yield categories. Second, it provides competitive context that maps manufacturer positioning, recent innovation signals, and certification or standards developments into a single decision-relevant framework. Third, it connects market growth to operational considerations such as production scale, regional manufacturing dynamics, and channel-specific purchasing behavior, helping leaders translate macro projections into execution assumptions.
The research also serves as a reference point for partnership and sourcing evaluation. In a market where concentration is high and performance credibility is increasingly scrutinized, understanding the distinction between brand visibility and verifiable engineering advantage is essential. Recent events—such as updated product catalogs, premium showcase demonstrations, and landmark certification achievements—provide useful leading indicators of where incumbents are investing and how they intend to defend or expand their positions. By placing these signals into a longer historical and forecast context, the report enables decision-makers to separate short-term momentum from durable strategic shifts.
Access the Full Strategic Assessment
This article serves as an introduction to the full Car Amplifiers Market research publication, which contains the complete segmentation breakdown, regional demand structures, application-level analysis, manufacturer profiles, and forecast detail required for thorough strategic planning. The macro trajectory and competitive themes outlined here establish the analytical foundation, but the complete dataset is necessary for precise market sizing, segment prioritization, and scenario modeling.
Organizations preparing for 2026 planning cycles should treat this intelligence as a prerequisite for informed investment and positioning decisions. The full report provides the depth needed to move from directional insight to operational action, including the segmentation detail and competitor specificity that cannot be fully reproduced here. To obtain the complete forecast, segmentation data, and competitive analysis, access the full market research report on our source page.
For detailed analysis of this topic, please visit the official page: Car Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


