



PW Consulting: Law Enforcement Software Market to Reach $30B by 2032 with 10% CAGR

Navigating the Next Wave: Strategic Intelligence in the Law Enforcement Software Market 2026–2032
A Market at the Crossroads of Technology and Public Safety
The global law enforcement software market stands at a defining inflection point. Between 2020 and 2025, the sector expanded from 9.5 billion USD to 15.4 billion USD, reflecting a decade of sustained investment in digital policing, records modernization, and dispatch automation. Our latest research projects this momentum to accelerate through 2032, with the market reaching 30.02 billion USD and a compound annual growth rate of 10.0 percent over the 2026–2032 forecast period. These are not merely trailing indicators; they are structural signals that public safety agencies, technology vendors, and institutional investors must interpret with precision.
For enterprise decision-makers, the strategic question has shifted from whether to digitize law enforcement workflows to how to architect integrated, compliant, and scalable platforms that can withstand regulatory scrutiny, labor constraints, and evolving threat landscapes. This report delivers the analytical framework required to navigate that complexity. It translates macroeconomic trajectory into actionable intelligence, mapping the pathways through which cloud migration, records management modernization, and AI-enabled digital policing are reshaping procurement, partnership, and competitive positioning.
Why 2026 Demands a Fresh Strategic Lens
The 2026 landscape is shaped by converging pressures that traditional planning cycles rarely capture in unison. Persistent staffing shortages across police departments, federal and state agencies, and municipal correctional facilities are driving rapid automation of routine workflows. Simultaneously, regulatory frameworks continue to tighten around criminal justice information handling, with CJIS compliance, sovereign-data requirements, and regional hosting expectations becoming non-negotiable design constraints for any prospective deployment. These dynamics are not isolated; they reinforce one another. Agencies seeking to do more with fewer personnel are prioritizing platforms that unify dispatch, records, case management, and evidence workflows, while vendors must engineer architectures that satisfy both operational efficiency and jurisdiction-specific privacy mandates.
Our analysis situates these forces within a broader competitive reality: market concentration remains pronounced, with the top three players collectively commanding a significant share and the top five exceeding three-quarters of total revenue. This concentration does not imply stagnation. Rather, it signals a market where incumbents are expanding platform breadth while specialized entrants are carving defensible niches through cloud-native RMS/CAD integration, digital evidence workflows, and real-time intelligence tooling. Understanding where each competitor is vulnerable, where integration gaps persist, and which capability bundles are resonating with end users is essential for any organization seeking to enter, expand, or partner within this ecosystem.
Police Law Enforcement Recorder Market
What This Report Delivers: Operational Intelligence, Not Abstract Projections
This study is designed for practitioners who require granular, decision-ready intelligence rather than high-level summaries. Beyond the headline trajectory, the report dissects the market across deployment models, solution categories, and end-use segments, providing a multidimensional view of where adoption is accelerating and where legacy dependencies still constrain modernization. Readers will gain access to a structured competitive profiling framework covering leading vendors, their core offerings, and the strategic implications of their positioning. Each profile is assessed for product architecture, compliance posture, integration capabilities, and the operational realities of agency adoption.
The report also integrates recent market developments that illustrate how platform functionality is evolving in near-real time. For example, recent feature updates in records management systems have targeted faster pricing decisions and streamlined approval workflows, reflecting a broader industry push to reduce administrative friction and accelerate operational responsiveness. Such updates may appear incremental in isolation, but when mapped against broader deployment trends and end-use priorities, they reveal meaningful shifts in how agencies value speed, transparency, and workflow continuity. Our analysis connects these signals to longer-term adoption patterns, helping readers distinguish tactical enhancements from strategic repositioning.
Mapping the Competitive Field
The vendor landscape is anchored by organizations that have built reputations across the full spectrum of public safety software. Caliber Public Safety provides comprehensive CAD, RMS, mobile solutions, and NIBRS-compliant records management with CJIS-secure cloud hosting, positioning it as a full-stack provider for agencies prioritizing compliance and continuity. Vector Solutions contributes records management, CAD integration, and agency readiness software, emphasizing operational preparedness alongside core records functions. Motorola Solutions brings Spillman Flex CAD and RMS suites tailored for law enforcement records management, dispatch, and multi-agency coordination, leveraging deep domain expertise in dispatch-centric workflows.
Tyler Technologies offers an Enterprise Public Safety software suite encompassing CAD, law enforcement records management, mobile access, and analytics for policing operations, appealing to agencies seeking a unified analytics-enabled platform. Flock Safety has introduced cloud-based Flock Nova public safety software that integrates RMS, CAD, LPR video, and AI tools for real-time crime intelligence and investigations, reflecting the growing convergence of sensor data, video analytics, and records workflows. Axon Enterprise provides Axon Records and Evidence management software with direct CAD integration for digital evidence storage, chain of custody, and officer workflows, targeting the evidentiary and investigative demands that increasingly define modern case handling.
Versaterm contributes cloud-based CAD, RMS, and CommunityConnect solutions for dispatch, reporting, and public safety operations, with a footprint that spans North American deployment models. CODY Systems has developed Pathfinder cloud RMS/CAD software with NIBRS native support, mobile RMS, and cross-platform data sharing, addressing interoperability and compliance requirements that remain central to multi-jurisdictional operations. EIS provides core CAD, RMS, jail, and mobile public safety software solutions, reinforcing the enduring importance of end-to-end coverage across detention and field operations. PsPortal supplies CJIS-compliant cloud software for secure NCIC/NLETS database access and law enforcement records management, highlighting the critical role of secure information exchange in integrated platforms.
Verint focuses on public safety software for emergency call handling, recording, and operational efficiency in law enforcement dispatch and response, complementing broader CAD/RMS ecosystems with specialized communications and recording capabilities. Oracle has developed a Public Safety Suite with CAD, RMS, and jail management systems integrated for secure law enforcement data management, bringing enterprise-scale infrastructure and integration depth to a sector that increasingly values platform durability and data governance. Together, these players illustrate a market where differentiation is no longer defined solely by feature count, but by compliance assurance, interoperability, evidence lifecycle management, and the ability to support multi-agency coordination under constrained staffing conditions.
Market Dynamics Shaping Adoption Trajectories
Several structural dynamics are reshaping how agencies evaluate, procure, and deploy law enforcement software. Cloud adoption continues to gain traction, supported by the promise of scalable infrastructure, reduced on-premises maintenance burdens, and faster access to updated functionality. At the same time, cloud deployment in this sector is not a simple lift-and-shift decision. Agencies and vendors must navigate regional hosting options that satisfy both CJIS sovereign-data requirements and localization expectations, making architecture decisions highly jurisdiction-sensitive. This reality elevates the strategic importance of deployment flexibility, data residency controls, and transparent compliance documentation.
Labor economics are equally influential. Persistent staffing shortages are accelerating the adoption of integrated platforms that automate routine processes, reduce manual data entry, and improve cross-functional visibility. In parallel, federal funding mechanisms such as the Byrne Justice Assistance Grants are helping agencies justify investments in workflow automation and modern records infrastructure. These funding and labor dynamics create a favorable environment for platforms that can demonstrably reduce administrative load while improving response coordination and investigative throughput. Decision-makers should therefore assess vendors not only on feature breadth, but on measurable operational efficiency gains and integration readiness with existing agency ecosystems.
Regulation remains a defining constraint and enabler. CJIS compliance is foundational for any platform handling criminal justice information, and integrated software environments must preserve data sharing integrity, privacy safeguards, and auditability across modules. As platforms become more interconnected, the compliance surface area expands, making it essential for buyers to evaluate end-to-end governance rather than isolated module certifications. The reports framework helps readers map these requirements to vendor capabilities, ensuring that procurement decisions align with both operational ambition and regulatory reality.
How to Use This Research for 2026 Decision-Making
This report is structured to support multiple decision pathways. For technology vendors and aspiring market entrants, it provides a competitive terrain map that clarifies where concentration is highest, where integration gaps create entry opportunities, and which solution categories are gaining relative momentum. For public safety agencies and municipal decision-makers, it offers a structured basis for comparing deployment models, evaluating compliance posture, and aligning platform selection with staffing constraints and funding timelines. For investors and strategic partners, it delivers a forward-looking view of market scale, growth cadence, and the competitive dynamics that will determine which platforms achieve durable share as the market approaches 30.02 billion USD by 2032.
Throughout the analysis, the emphasis is on actionable clarity. Readers will find segmentation discussions that illuminate how deployment preferences, solution adoption, and end-use demand interact across the forecast horizon, without reducing the market to oversimplified ratios. The competitive profiles are designed to support side-by-side evaluation, while the dynamics section connects near-term developments to longer-term structural shifts. By linking macro trajectory to micro decision criteria, the report enables organizations to build strategies that are resilient to regulatory change, staffing volatility, and evolving technology expectations.
Conclusion: Turning Market Scale Into Strategic Advantage
The law enforcement software market is expanding with clarity and conviction, but growth alone does not guarantee advantage. The organizations that will capture value in 2026 and beyond are those that can translate macro momentum into disciplined choices about deployment architecture, compliance readiness, integration depth, and workflow automation. This report provides the intelligence infrastructure required to make those choices with confidence. It combines top-down market trajectory with bottom-up competitive and operational analysis, giving readers a comprehensive vantage point on where the market is headed and how to position within it.
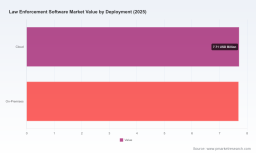
Law Enforcement Software Market
The full study contains the detailed segmentation analysis, competitive benchmarking, deployment and solution-level insights, and forward-looking scenario context needed to move from strategic awareness to execution. For decision-makers ready to align their planning with the realities of a 10.0 percent CAGR market on a path from 17.34 billion USD in 2026 to 30.02 billion USD in 2032, the complete report offers the depth required to act decisively.
For detailed analysis of this topic, please visit the official page: Law Enforcement Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


