



PW Consulting: Soundbars Market to Hit $7.44B by 2032 with 7.08% CAGR

Strategic Intelligence for the Soundbars Market: Navigating Growth from 2026 to 2032
The global home entertainment landscape is undergoing a profound transformation, driven by the convergence of high-fidelity audio, smart home integration, and the enduring demand for immersive content consumption. As the market transitions from a phase of pandemic-fueled expansion into a period of structured, technology-led growth, stakeholders require precise, forward-looking intelligence to inform capital allocation, product roadmap planning, and competitive positioning. Our latest comprehensive Soundbars Market research report offers exactly that: a rigorously constructed, data-driven strategic roadmap spanning the forecast period from 2026 through 2032. This article outlines the foundational market trajectory, the structural forces currently reshaping competitive dynamics, and the actionable intelligence embedded within the full study to equip enterprise decision-makers with the clarity needed for 2026 and beyond.
The Macro Trajectory: A Sustained Growth Arc Validated by Historical Momentum
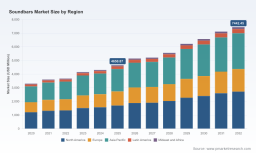
Market evolution is rarely linear, yet the historical record for the soundbars sector during the base period of 2020 to 2025 demonstrates a remarkably consistent upward curve, underscoring the category's transition from a peripheral accessory to an essential component of modern living spaces. Revenue expanded steadily from 3,300 million USD in 2020 to 4,650.87 million USD by the close of 2025. This trajectory reflects not merely volume growth but a fundamental shift in consumer willingness to invest in dedicated audio experiences that complement large-format television displays and streaming platforms.
Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with market valuation anticipated to climb from an estimated 5,144.89 million USD in 2026 to approximately 7,442.45 million USD by the terminal year of the study. This progression translates into a compound annual growth rate of 7.08 percent, a figure that signals healthy, sustainable momentum rather than speculative hype. For executive teams and investors, this CAGR serves as a critical benchmark: it validates the category's resilience against macroeconomic headwinds while highlighting the necessity of strategic agility. The market is not expanding uniformly across all vectors, and the firms that thrive will be those that align product development, pricing architecture, and channel strategy with the underlying structural shifts identified in our full analysis. The detailed forecasting models, scenario planning matrices, and sensitivity parameters that underpin these projections are explored comprehensively in the complete report, offering a transparent view of the assumptions and variables that will dictate performance across different operational horizons.
Structural Segmentation: Where Growth Converges and Diverges
Revenue is generated across multiple dimensions, each carrying distinct growth drivers, margin profiles, and deployment architectures. The historical and projected sizing across these axes reveals how form factor preferences, connectivity standards, application environments, and regional infrastructure maturity are collectively steering the medium-term trajectory. Understanding these structural splits is essential for manufacturers calibrating SKU portfolios, for distributors optimizing inventory depth, and for private equity or corporate venture teams evaluating market entry or consolidation opportunities.
- Form factor architecture continues to dictate acoustic performance trade-offs and installation complexity. The distribution between tabletop configurations, wall-mounted systems, and specialized variants reflects shifting consumer priorities around aesthetics, room acoustics, and integration with existing television mounts and entertainment centers.
- Connectivity protocols have fundamentally redefined the user experience and purchasing decision matrix. The balance between Wi-Fi-enabled ecosystems, Bluetooth-dominant streaming setups, and emerging or niche connectivity standards highlights the tension between local wireless convenience, multi-room synchronization, and high-bandwidth lossless audio expectations.
- Application environments segment the market into residential audio enhancement, commercial deployment scenarios, and specialized or emerging use cases. Each vertical carries unique procurement cycles, performance requirements, and replacement rhythms that influence both top-line volume and aftermarket service strategies.
- Geographic distribution reveals how mature entertainment markets, rapidly digitizing economies, and price-sensitive regions each contribute differently to aggregate growth. Infrastructure readiness, content localization, and brand perception heavily influence how product portfolios must be adapted to capture share in each territory.
The precise valuation breakdowns, share allocations, and forward-looking sensitivity adjustments across these segmentation dimensions are detailed extensively within the full research document. Accessing the complete study provides the granular visibility required to identify white-space opportunities, anticipate substitution effects, and model portfolio performance under varying demand scenarios.
Competitive Dynamics and the 2026 Strategic Reset
The competitive architecture of the soundbars market in 2026 is characterized by concentrated leadership, rapid product cycle acceleration, and a clear divergence between mass-market integration strategies and specialized audiophile-grade interventions. Strategic groupings shaped by headquarters and ecosystem depth illustrate how incumbents and challengers are simultaneously competing on sound quality, spatial processing, and smart-home interoperability.
Ecosystem Leaders and Premium Positioning
At the top of the competitive hierarchy, firms such as Samsung Electronics, LG Electronics, Sony Corporation, and Bose Corporation continue to anchor the market through aggressive premiumization, advanced spatial audio marketing, and deep television or consumer electronics integration. Samsung's Q-Series portfolio leverages multi-channel Dolby Atmos architectures, Q-Symphony synchronization with compatible displays, and expanding multi-device audio ecosystems to reinforce the living-room entertainment anchor. LG has emphasized modular flexibility, utilizing its Sound Suite design philosophy to allow adaptable speaker and subwoofer placement while deploying proprietary processing to refine spatial rendering and dialogue clarity. Sony maintains its traditional home-cinema heritage by pairing accessible entry performers with flagship Atmos-capable models tuned for cinematic reference listening and high-fidelity playback. Bose continues to compete at the intersection of acoustic refinement and convenience, aligning immersive processing with smart-home interoperability and simplified user onboarding.
Platform Players and Ecosystem Scale
Parallel to the traditional consumer electronics leaders, platform-centric players are expanding their footprint through integrated multi-room capabilities and subscription-adjacent ecosystem lock-in. Sonos has extended its architectural approach into the soundbar category, coupling waveguide-based acoustic engineering with wireless multi-room orchestration and enhanced low-frequency extension through dedicated woofer technologies. Harman International, operating through its JBL brand, continues to leverage broad audio ecosystem reach, offering immersive channel configurations and wireless subwoofer options designed to slot into broader Harman-connected environments. These players benefit from network effects, recurring engagement, and cross-device compatibility, but must also navigate the pressure of hardware margins, platform differentiation, and consumer fatigue around ecosystem fragmentation.
Late Entrants and Niche Audio Specialists
A notable strategic development in the current cycle is the consistent movement of specialized high-fidelity and pro-audio-adjacent brands into the soundbar category, targeting consumers willing to pay a premium for acoustic accuracy, calibrated calibration, and scalable home-theater configurations. SVS entered the space with its first soundbar platform, emphasizing onboard room correction, Dolby Atmos support, wireless subwoofer pairing, and expandable channel architectures intended for enthusiasts seeking serious home-theater performance. KEF introduced a single-enclosure approach built around coaxial driver technology, prioritizing spatial coherence and musicality within a compact installation footprint. Yamaha continues to serve the broader upgrade-to-quality segment with compact, balanced entries that emphasize high-resolution audio handling and approachable everyday performance. The arrival of these specialists intensifies the performance arms race and pressures incumbents to justify premium pricing through demonstrable acoustic differentiation rather than brand heritage alone.
Worldwide Sound Cards Market
January 2026 Product Cycle: Strategic Implications
The opening months of 2026 already reflect the acceleration described above. Multiple major manufacturers deployed new product initiatives within a compressed timeframe, signaling that 2026 will be defined by rapid refresh cycles rather than incremental updates. LG's introduction of a modular sound system combining a central soundbar, dedicated subwoofer, and wireless surround elements highlighted a push toward placement flexibility and adaptive tuning. Samsung's simultaneous expansion of its Q-Series lineup, including higher-channel-count configurations and dialogue-shifting processing features, reinforced the ongoing premiumization of mainstream living-room audio. SVS's first-ever soundbar reveal underscored the continued blurring of lines between traditional home-theater subwoofer specialists and integrated soundbar form factors. KEF's compact coaxial-driver soundbar further demonstrated that acoustic accuracy and form-factor restraint can serve as decisive differentiators in crowded retail environments. Collectively, these movements indicate that competitive advantage in 2026 will increasingly depend on the speed of architectural innovation, the credibility of spatial audio claims, and the ability to simplify complex installations without sacrificing performance.
Soundbars Market
Input Constraints, Supply Realities, and Market Resilience
Growth narratives must be evaluated alongside the operational frictions that govern manufacturing, component sourcing, and regulatory exposure. Two intersecting themes are particularly relevant to strategic planning for the 2026 to 2032 horizon.
First, the rare earth supply picture remains a structural variable for audio hardware manufacturers. With the twelve-month suspension of China's expanded rare earth export controls set to expire in November 2026, current supply conditions indicate limited progress in reducing global dependence on concentrated sourcing channels. For soundbars and related audio electronics, rare earth elements influence magnet design, transducer performance, and miniaturization efficiency. Firms that have not diversified supplier relationships, secured forward inventory positions, or engineered component substitutions may face margin compression or delayed product cycles if export conditions tighten.
Second, the broader industrial context around critical minerals continues to reshape input-cost expectations across consumer electronics and adjacent device categories. Lithium's role in the energy transition has intensified attention on both primary extraction and recycled sourcing pathways, and while soundbars are not direct battery-dependent devices in the same sense as portable electronics or electric vehicles, the macroeconomic attention on critical mineral resilience influences component pricing norms, supplier negotiating leverage, and strategic procurement frameworks across the broader electronics value chain. Companies that embed supply-chain scenario modeling into product planning will be better positioned to absorb volatility than those that treat component sourcing as a static cost line.
These dynamics do not negate the sector's growth outlook, but they reframe how leadership teams should approach manufacturing footprints, bill-of-materials strategy, and long-term cost modeling. The complete market study incorporates supply-side sensitivity analysis, sourcing risk assessments, and procurement strategy recommendations that allow organizations to stress-test plans against realistic input-cost and regulatory scenarios.
The soundbars market entering 2026 presents a compelling combination of validated growth, architectural innovation, and intensifying competitive differentiation. Historical momentum through 2025, a projected trajectory toward 2032, and the early-2026 product cycle collectively point to an environment where strategic advantage will be earned through precise segmentation targeting, credible acoustic engineering, ecosystem interoperability, and resilient supply-chain design. Organizations that align product strategy with the structural insights outlined here will be best positioned to capture disproportionate share in a market that is expanding steadily but rewarding only those who execute with discipline.
To translate this high-level intelligence into actionable commercial strategy, we encourage stakeholders to access the full Soundbars Market research report. The complete study provides detailed segmentation valuations, competitive benchmarking, supply-chain scenario modeling, regional deployment analysis, and forward-looking demand indicators calibrated to support board-level planning, product portfolio decisions, and investment prioritization throughout the 2026 to 2032 forecast period.
For detailed analysis of this topic, please visit the official page: Soundbars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


