



PW Consulting: Sawmill Market Hits $93.5M in 2025, Projects 3.23% CAGR Through 2032

Navigating the Sawmill Market: Strategic Intelligence for 2026 Decision-Making
The global sawmill industry stands at a critical inflection point. As we move through 2026, timber processors, investors, and supply chain strategists face a complex matrix of shifting trade policies, evolving raw material economics, and structural changes in how wood products are sourced and manufactured. Understanding where this market is headed requires more than surface-level trend watching. It demands rigorous, data-grounded analysis that connects macroeconomic signals to operational realities.
Our newly released Sawmill Market Research report delivers precisely that level of insight. Spanning historical performance from 2020 through 2025 and extending forward across the 2026 to 2032 forecast horizon, this study provides the foundational intelligence enterprise leaders need to allocate capital, plan capacity, and position for sustainable growth. This article offers a strategic preview of the report's scope, methodology, and decision-ready frameworks, demonstrating why it has become an essential reference for senior executives navigating the timber sector.
Why 2026 Demands a Fresh Market Assessment
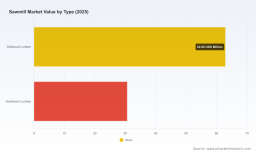
The sawmill sector has demonstrated remarkable resilience over the past half-decade, but resilience is not the same as predictability. Between 2020 and 2025, the global market expanded from approximately 79.55 million USD to 93.5 million USD, reflecting a compound trajectory shaped by post-pandemic construction rebounds, shifting housing demand, and supply chain recalibration. Looking ahead, the market is projected to reach 94.16 million USD in 2026, with growth accelerating toward 116.5 million USD by 2032. This forward path implies a compound annual growth rate of 3.23 percent, a figure that underscores both steady expansion and the nuanced volatility that defines industry cycles.
What makes the 2026 landscape particularly consequential is the convergence of several disruptive forces. Import tariff structures have tightened considerably, reshaping cost dynamics for cross-border lumber flows. Labor availability, natural gas pricing, and insurance premiums continue to pressure operating margins. At the same time, policy interventions are opening new financing channels for mill modernization and capacity restoration. For enterprises evaluating expansion, acquisition, or portfolio optimization, the margin for strategic error has narrowed. Informed decisions now depend on granular visibility into how these intersecting factors will play out across different market segments and regional contexts.
Report Architecture: What Decision-Makers Will Find Inside
This research was designed with practitioner needs at its core. Rather than offering abstract commentary, the report delivers a structured, actionable intelligence framework that translates market data into executable strategies. The following components illustrate the depth and practical orientation of the analysis.
Historical Baseline and Forward Projection
The report anchors its forecasts in a rigorously verified historical dataset covering 2020 through 2025. By examining year-over-year shifts, demand inflection points, and the impact of external shocks, readers gain a clear picture of the structural trends that will carry into the forecast period. The 2026 to 2032 projection window applies scenario-based modeling to map plausible growth pathways, enabling leadership teams to stress-test plans against multiple macroeconomic conditions.
Revenue Composition and Segment Breakdown
Understanding how revenue is distributed across product categories, application areas, and geographic regions is essential for identifying where competitive advantages can be built. The report provides a detailed segmentation analysis that illuminates the relative weight of softwood and hardwood lumber streams, the demand pull from construction and furniture manufacturing, and the contribution of packaging, joinery, and ancillary applications. Geographic distribution patterns are examined to reveal which markets exhibit the strongest momentum and which face structural headwinds.
Competitive Landscape and Enterprise Profiles
Market concentration remains a defining feature of the sawmill sector. The report evaluates the competitive positioning of leading producers, analyzing how scale, geographic footprint, and product specialization influence market share. Detailed profiles cover major North American operators, European forest products firms, and specialized equipment manufacturers, offering a panoramic view of the organizations shaping industry output. These profiles examine operational focus, production capabilities, and strategic orientations, giving readers a reliable reference for benchmarking and partnership evaluation.
Industry Dynamics and Policy Environment
Beyond pure market mechanics, the research integrates an analysis of the forces that are actively reshaping competitive conditions. Tariff escalations, stumpage price movements, log supply constraints, and labor cost inflation are examined in the context of their operational impact. The report also tracks legislative and financing developments that affect capital deployment, including rural development loan programs and proposed legislation aimed at sustaining sawmill infrastructure. This policy-aware perspective ensures that strategic plans account for both market-driven and regulatory-driven change.
Sawmill Market
The Competitive Arena: Key Players and Strategic Positioning
The sawmill market features a blend of large-scale integrated producers, regionally focused operators, and specialized equipment providers. Several organizations stand out for their influence on supply, innovation, and market signaling.
In North America, prominent producers such as West Fraser Timber Co., Weyerhaeuser Company, Canfor Corporation, Interfor Corporation, and Sierra Pacific Industries anchor substantial portions of softwood and hardwood output. These firms operate extensive sawmill networks and have pursued expansion and modernization initiatives that influence regional capacity dynamics. Georgia-Pacific LLC and Hampton Affiliates contribute additional scale within the building products and lumber segments, while Tolko Industries Ltd. and Arauco extend production reach across North American and international markets.
European operations are led by established forest products enterprises including Stora Enso, Södra, SCA, and Moelven Industrier ASA, each bringing distinct capabilities in sawn timber and engineered wood production. The Pfeifer Group, Holzindustrie Schweighofer, Klausner Holz Thüringen, and Ante-holz GmbH represent Germany and Austria's strong hardwood and sawn timber tradition, reflecting the region's emphasis on quality-grade lumber and industrial processing.
Beyond integrated producers, the market includes specialized equipment manufacturers such as Wood-Mizer LLC and Peterson Sawmills, which serve on-site and portable milling needs for agricultural, construction, and decentralized wood processing applications. These companies illustrate the breadth of the ecosystem, where machinery innovation intersects with changing patterns of timber utilization.
Competitive dynamics are not static. Capacity adjustments, asset sales, and operational curtailments are actively reshaping the field. Recent industry activity includes strategic divestitures, facility disruptions, and product demonstrations that signal shifting priorities. For decision-makers, tracking these movements is essential to understanding where supply flexibility is increasing, where consolidation pressure is building, and how rivals are recalibrating their portfolios.
Forces Reshaping the Market: Dynamics That Cannot Be Ignored
No strategic assessment of the sawmill market is complete without a clear accounting of the external forces that drive cost structures, demand patterns, and investment timing. Several developments have emerged as particularly influential.
Trade policy remains a dominant variable. Import duty levels on key cross-border lumber flows have risen substantially, altering the cost calculus for domestic producers and changing the competitive balance between regional supply sources. These shifts affect pricing strategies, margin expectations, and the economics of export-oriented production.
Raw material economics present a mixed picture. While stumpage and delivered log prices have experienced declines in certain regions, other cost inputs, including logging, trucking, labor, natural gas, and insurance, continue to exert upward pressure. The resulting squeeze on operating margins has prompted closer scrutiny of residual sales revenue, processing efficiency, and input procurement strategies. Understanding how these opposing trends interact is vital for projecting profitability under different supply scenarios.
Buttermilk Market
Policy and financing interventions are introducing new variables into the capital landscape. Government-backed loan programs have been deployed to support the reopening, expansion, and modernization of sawmill facilities, particularly those processing byproducts from federal land restoration activities. Proposed legislation aims to make such programs permanent, signaling a longer-term policy interest in sustaining domestic sawmill infrastructure. For enterprises considering facility investment or modernization, these programs can meaningfully affect project economics and timing.
Operational disruptions also warrant attention. Facility damage events, log supply constraints, and market-driven curtailments have intersected to create pockets of capacity tightness alongside broader demand uncertainty. These episodes remind industry participants that resilience planning, supply diversification, and contingency modeling are no longer optional enhancements but core components of operational strategy.
Translating Insight Into Action: How the Report Supports Strategic Decisions
The value of this research lies in its ability to convert complex market signals into clear strategic implications. Executives can use the report to address several high-priority questions.
- Which product segments and application areas are most likely to drive revenue growth over the forecast period, and how should production portfolios be aligned accordingly?
- How are regional demand patterns evolving, and where do the most favorable conditions exist for capacity investment, market entry, or partnership development?
- What competitive moves are leading producers making, and how should organizations interpret expansions, divestments, and operational adjustments when planning their own responses?
- How should enterprises model the impact of tariff changes, input cost volatility, and financing availability on project feasibility and margin projections?
- Which structural trends indicate durable shifts in demand, and which reflect cyclical fluctuations that require differentiated strategic treatment?
By addressing these questions within a unified analytical framework, the report helps leadership teams move from observation to action. Whether the objective is to prioritize capital projects, refine market targeting, assess competitor behavior, or build more resilient supply strategies, the research provides the evidence base needed to support confident decision-making.
Conclusion: Strategic Clarity for an Evolving Market
The sawmill market is neither static nor easy to navigate. Growth is real, but it is uneven. Opportunity is present, but it is accompanied by cost pressures, policy uncertainty, and competitive repositioning. In such an environment, strategic advantage belongs to organizations that ground their decisions in comprehensive, forward-looking intelligence rather than fragmented signals.
This report offers that foundation. It combines verified historical data, carefully constructed forecasts, detailed competitive profiling, and nuanced analysis of the forces shaping industry dynamics. For executives, investors, and strategic planners, it provides the clarity required to act with precision in 2026 and beyond.
To access the complete dataset, full segmentation breakdowns, detailed company profiles, and the complete forecast model, visit the source page for the Sawmill Market Research report. The full intelligence package is available for teams ready to translate market understanding into strategic execution.
For detailed analysis of this topic, please visit the official page: Sawmill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


