



PW Consulting: Messaging Platform Market Hits $89.65M in 2025, Projected 5.7% CAGR Through 2032

Beyond the Inbox: Strategic Intelligence for the Messaging Platform Market 2026–2032
The enterprise communication landscape is undergoing a structural transformation. What was once a utility layer for internal coordination has evolved into a critical orchestration engine for customer engagement, operational resilience, and cross-border data exchange. As organizations navigate an era defined by AI-augmented workflows, fragmented regulatory mandates, and accelerating cloud migration, the ability to separate signal from noise in the messaging platform ecosystem has become a decisive competitive advantage. Our latest research release, Messaging Platform Market 2026–2032: Strategic Intelligence & Forecast , is engineered to provide executives, product leaders, and procurement strategists with the analytical rigor required to allocate capital, position technology stacks, and anticipate market shifts with precision.
The Macro Trajectory: Compound Growth Meets Structural Inflection
Drawing on a comprehensive historical baseline spanning 2020 through 2025, the market has demonstrated consistent upward momentum, with total industry revenue climbing steadily as enterprises embed messaging infrastructure into core operational workflows. The trajectory projects into a robust forecast window through 2032, anchored by a compound annual growth rate of 5.7 percent. This growth is not merely linear expansion; it reflects a market in the midst of platform consolidation, feature compression, and heightened demand for interoperable, secure, and scalable communication architectures. Revenue progression across the forecast horizon signals sustained institutional investment in messaging as a strategic layer rather than a tactical add-on.
The implications for enterprise decision-makers are clear: budgeting for messaging infrastructure must now account for multi-year capability roadmaps, not just license renewals. Organizations that treat messaging as a static utility will find themselves outpaced by competitors who leverage platform elasticity, API-driven integration, and intelligent routing to compress response cycles and improve engagement quality.
Market Architecture: Why Segmentation Matters Without the Noise
Understanding where value concentrates requires more than top-line figures. The research dissects the market across multiple structural dimensions to reveal how demand, capability, and pricing dynamics diverge by segment type, deployment context, and end-user application. Rather than presenting isolated percentages, the analysis contextualizes how each segment interacts with broader enterprise priorities, such as digital transformation maturity, compliance readiness, and channel diversification.
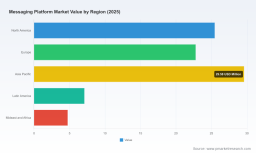
Historical and projected sizing across regional and application categories is examined through a demand-pull lens, highlighting where infrastructure investments are being prioritized and where platform vendors are differentiating on reliability, localization, and integration depth. The report deliberately avoids superficial metric dumping, instead mapping how segment-level behaviors influence procurement cycles, vendor evaluation criteria, and total cost of ownership over the forecast period.
Competitive Dynamics: incumbents, challengers, and the shifting center of gravity
The messaging platform arena is characterized by a tightly concentrated competitive field, with a small group of established players commanding a substantial share of enterprise and provider-facing deployments. The research profiles a curated set of organizations that shape pricing norms, feature expectations, and integration standards across the ecosystem. These include platform providers targeting communication service providers and enterprise buyers, technology conglomerates embedding messaging into broader productivity suites, and specialized vendors offering secure collaboration hubs, API-driven messaging services, and multi-channel engagement platforms.
Messaging Platform Market
Several strategic archetypes emerge from the competitive mapping. Legacy-heavy vendors are accelerating modernization to retain enterprise accounts that demand tighter application integration and compliance assurance. Cloud-native and API-first players are expanding into carrier-grade and business messaging use cases, leveraging developer ecosystems to drive adoption. Meanwhile, regional specialists continue to compete on localization, data residency, and domain-specific workflow support. The report details how these positioning strategies intersect with procurement timelines, risk tolerances, and internal IT capacity, enabling readers to benchmark their vendor shortlists against realistic deployment scenarios.
Recent Momentum: Cross-Industry Signals Reshaping the Landscape
The market does not move in isolation. Recent developments across product launches, regulatory milestones, and infrastructure requirements are actively reshaping how organizations evaluate messaging platforms. In early-to-mid 2026, multiple product and approval milestones captured industry attention. An AI-powered messaging platform secured approval for RCS Business Messaging in the United States, signaling heightened regulatory and carrier readiness for richer, interactive enterprise messaging flows. Simultaneously, enterprise-focused communications providers launched self-healing voice resiliency technology and carrier-grade out-of-band messaging capabilities enhanced with AI and productivity features, underscoring a broader push toward reliability, continuity, and intelligent routing in mission-critical deployments.
At the same time, major exhibition showcases highlighted the emergence of autonomous, AI-enabled messaging architectures, reinforcing the industry's trajectory toward low-friction, context-aware communication layers. These announcements are not isolated product news; they reflect a market-wide shift toward platforms that can operate with greater autonomy, resilience, and cross-channel coherence.
Worldwide Mobile Application Development Platform Market
Regulatory and Infrastructure Undercurrents: The Hidden Cost of Non-Alignment
Beyond product cycles, structural forces are redefining evaluation criteria. The global financial community's completion of the transition to the ISO 20022 messaging standard has established a new baseline for cross-border payment speed, data richness, and interoperability. This shift reverberates beyond banking, influencing how enterprises design message schemas, audit trails, and integration pathways across partners and service providers. Concurrently, financial institutions have finalized critical architecture adjustments to achieve ISO 20022 compliance for 2026 implementation, reinforcing the expectation that messaging standards will increasingly shape vendor requirements and data governance expectations.
On the regulatory front, enterprise messaging platforms are operating under intensifying obligations. Compliance frameworks including GDPR, DORA, and the NIS2 Directives now shape how organizations manage data privacy, incident reporting, and record retention within communication workflows. Procurement teams can no longer treat compliance as an afterthought; platform selection must account for data handling boundaries, logging granularity, regional residency constraints, and auditability. Additionally, infrastructure considerations are gaining prominence. Scalable cloud architectures and specialized materials in hardware components are becoming relevant to reliable data transmission and energy efficiency, particularly as messaging workloads intensify and uptime expectations rise. Strategic buyers are beginning to factor these operational realities into vendor scoring, recognizing that platform endurance is inseparable from underlying infrastructure quality.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
This research is built for execution, not just observation. The full study is structured to translate market complexity into decision-ready frameworks. Readers will find a detailed competitive landscape assessment that maps vendor positioning, capability emphasis, and ecosystem reach across major players. The report examines product and service architectures across the principal platform categories, providing context on how each category serves distinct operational needs and buyer profiles.
Forecast modeling extends across the 2026–2032 horizon, supported by historical trend analysis and scenario-aware projections that help organizations stress-test investment assumptions. The study includes use-case orientation across enterprise and personal communication contexts, highlighting where platform selection criteria diverge and where convergence is accelerating. In addition, the report integrates regulatory, standards-based, and infrastructure developments into a cohesive market dynamics narrative, enabling readers to anticipate compliance burdens, architectural expectations, and procurement risk factors before they become contractual blockers.
To support practical application, the analysis is paired with vendor evaluation considerations, deployment readiness markers, and strategic guidance for aligning messaging investments with broader digital transformation objectives. The goal is to equip teams with a structured lens for comparing platforms, sequencing adoption, and avoiding overinvestment in capabilities that do not match future operating conditions.
Strategic Implications for 2026 Decision-Makers
For leadership teams planning 2026 budgets and technology roadmaps, the messaging platform market presents both opportunity and complexity. The steady growth trajectory indicates durable demand, but the real strategic question is not whether to invest, but how to invest intelligently. Organizations should assess whether their current messaging stack can absorb AI-driven routing, multi-channel orchestration, and resilience requirements without fragmented point solutions. They should evaluate vendor commitments against compliance mandates, data governance expectations, and integration depth rather than feature checklists alone.
Procurement strategies must also account for concentration dynamics. In markets where a limited set of providers dominate enterprise and provider-facing deployments, negotiation leverage, transition risk, and roadmap alignment become central considerations. The research clarifies where competitive intensity is likely to drive differentiation, where pricing pressure may emerge, and where consolidation could reshape available options over the forecast window.
Access the Full Intelligence: Directed Next Steps
The messaging platform market is not a monolith; it is a set of interlocking demand streams, compliance pressures, infrastructure constraints, and competitive maneuvers. Capturing the strategic value of this environment requires a research foundation that goes beyond headline figures and connects market structure to operational decision-making. Our complete report delivers the granular segmentation, vendor profiling, forecast breakdowns, and dynamics mapping necessary to build confidence in 2026 planning and beyond.
For executives seeking the full segmented data, competitive benchmarking, and forecast detail that underpin this analysis, the complete study is available through our market research portal. The full edition provides the structured intelligence required to validate assumptions, narrow vendor shortlists, and align messaging platform strategy with enterprise objectives through 2032.
For detailed analysis of this topic, please visit the official page: Messaging Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


