



PW Consulting: Smoke Evacuation System Market Hits $185M in 2025, Forecasted to Reach $318M by 2032 at 8.1% CAGR

Strategic Foresight in the Smoke Evacuation System Market: Navigating the 2026 Decision Landscape
The operating room has evolved from a purely clinical environment into a regulated, safety-centric ecosystem where invisible hazards demand visible solutions. Surgical smoke, once dismissed as an unavoidable byproduct of modern electrosurgery and minimally invasive techniques, is now recognized as a credible occupational health risk carrying particulate matter, volatile organic compounds, and potential pathogens. For healthcare executives, procurement leaders, and medical device strategists, this shift represents more than a compliance checkbox. It signals a structural realignment in capital allocation, vendor partnerships, and perioperative workflows. PW Consulting's latest Smoke Evacuation System Market research is designed specifically for decision-makers operating in this new reality. By projecting market trajectories from a 2025 base year through 2032, the report translates historical momentum into actionable intelligence, framing 2026 not as a continuation of past patterns, but as a pivotal inflection point for strategic intervention.
Smoke Evacuation Tubing Market
Market Trajectory and the Architecture of Growth
The historical record tells a clear story of accelerated adoption. Between 2020 and 2025, the global smoke evacuation system market expanded from a modest baseline to $185.0 million, reflecting a compound trajectory that outpaces many traditional surgical accessory categories. This growth is not accidental. It is the cumulative result of clinical awareness, regulatory pressure, and the physical expansion of minimally invasive procedural volume. Looking ahead, the forecast period through 2032 projects a sustained expansion pathway, anchored by an 8.1% CAGR that carries the market toward the $318.0 million threshold. These figures do more than chart revenue. They expose the timing of capital windows, the spacing of procurement cycles, and the maturation curve of hospital formulary adoption.
For executives mapping 2026 budgets, this trajectory carries immediate operational weight. The transition from $175.75 million in 2024 to $185.0 million in 2025, and onward to $205.54 million in 2026, signals that institutional demand is moving past early-adopter phases into broader standardization. Facilities that delay equipment evaluation or vendor negotiation risk entering a more crowded, price-sensitive procurement environment. Conversely, organizations that align capital planning with this growth curve can secure favorable terms, lock in service contracts, and position themselves ahead of reimbursement cycles. The report unpacks these timing dynamics without reducing them to static snapshots, instead mapping the cadence at which procurement teams should evaluate total cost of ownership, workflow integration, and sustainability of disposable supply chains.
Regulatory and Reimbursement Currents Reshaping Purchase Logic
The financial calculus for smoke evacuation equipment can no longer be isolated from policy momentum. Across multiple jurisdictions, legislative and administrative actions are converting occupational safety recommendations into reimbursable or mandated expenditures. Washington State, for example, has opened pathways for hospitals to secure reimbursement of up to $1,000 per operating room for qualifying surgical smoke equipment purchases, with registration through a vendor payee number required to capture the funds. Florida's legislative analysis underscores the counterweight of cost exposure, with initial per-room investments reaching up to $2,000 and recurring disposable costs approximating $19 per procedure. At the national level, eighteen U.S. states have enacted legislation requiring hospitals to provide surgical smoke management equipment, and additional states continue to move through legislative pipelines.
These dynamics reshape purchasing behavior in three measurable ways. First, they compress decision timelines, pushing facilities to evaluate equipment before mandates or reimbursement windows close. Second, they elevate the importance of per-procedure economics over upfront sticker price, making disposable efficiency, filter longevity, and tubing replacement cycles central to vendor selection. Third, they increase the strategic value of documentation and compliance readiness, since reimbursement and regulatory adherence frequently depend on verifiable equipment deployment and usage records. Our analysis integrates these policy vectors directly into the procurement narrative, showing how capital planning must now account for legislative timing, reimbursement eligibility, and state-specific cost thresholds. The report details how these pressures alter vendor negotiations, service-level expectations, and the financial modeling that hospital administrators use to justify perioperative upgrades.
Competitive Architecture and the New Differentiation Frontier
The market's competitive structure reflects both consolidation and targeted specialization. Concentration metrics indicate that the top three players command approximately 45.8% of revenue, while the top five extend their reach to roughly 67.2%. This hierarchy matters because it defines the negotiation bandwidth available to procurement teams, the service coverage models likely to be offered, and the pace at which new features migrate from innovation to standard specification. Yet within this consolidated frame, competitive advantage is increasingly determined by integration depth, clearance velocity, and workflow alignment rather than by brand legacy alone.
Smoke Evacuation System Market
Several organizations illustrate how product strategy is evolving under these conditions. I.C. Medical, Inc., based in Phoenix, Arizona, has positioned itself around specialized smoke evacuation instrumentation, including the Crystal Vision surgical smoke evacuator, the PenEvac electrocautery pencil, and filtration accessories engineered for operating room smoke plume management. ConMed Corporation, headquartered in Utica, New York, advances a different integration model with the PlumeSafe X5 Smoke Management System and the VisiClear surgical smoke evacuator, targeting streamlined OR plume control. KARL STORZ SE & Co. KG, from Tuttlingen, Germany, emphasizes compatibility within minimally invasive laparoscopic workflows by developing integrated smoke evacuation systems paired with ENDOFLATOR insufflators. Olympus Corporation, based in Tokyo, contributes a complementary approach through the OR-VAC surgical smoke evacuator, telescopic smoke evacuation pencils, and related operating room accessories.
The competitive field extends further across both established device manufacturers and workflow-focused innovators. Stryker Corporation, located in Kalamazoo, Michigan, embeds smoke evacuation capabilities within broader electrosurgical and operating room equipment platforms. Erbe Elektromedizin GmbH, from Tübingen, Germany, integrates smoke evacuation functionality directly into electrosurgical generators, aligning plume management with energy device control. Alesi Surgical, operating from the United Kingdom, pursues an alternative technical pathway with its Ultravision electrostatic smoke management system. Aspen Surgical Products, Inc., based in Davisburg, Michigan, supplies smoke evacuation systems and accessories tailored for surgical use, while Medimaxtech, Inc., distributes systems through hospital contracts designed for operating room deployment.
Recent regulatory milestones reveal how quickly product positioning can shift. In August 2024, ConMed Corporation secured FDA 510(k) clearance for the PlumeSafe X5 Smoke Management System, reinforcing its presence in the surgical smoke evacuation segment. In October 2025, KARL STORZ received FDA clearance for the ENDOFLATOR plus insufflator with an integrated surgical smoke evacuation system for laparoscopic procedures, a move that ties plume management directly to insufflation workflow. These clearances do more than validate engineering claims. They alter the comparison criteria that procurement committees use, introducing questions about compatibility with existing laparoscopic towers, service response times, consumable standardization, and the cost impact of adding evacuation functions to instruments already in the procedural pathway. The report examines these competitive moves within a structured vendor evaluation framework, helping readers understand which attributes translate into purchasing leverage and which represent product differentiation that may or may not justify premium positioning.
Report Architecture: From Macro Signals to Procurement-Grade Intelligence
This research is constructed to support execution, not merely observation. While high-level market size and growth trajectories provide the strategic frame, the majority of the analysis is devoted to decision-grade detail. The report maps product categories, application environments, and regional demand patterns in a way that allows procurement, clinical engineering, and commercial strategy teams to align their internal models with external market behavior. Instead of presenting isolated percentages or fragmented figures, the analysis connects product segmentation to workflow realities, links application environments to procedure volume dynamics, and ties regional variation to procurement cadence, regulatory exposure, and reimbursement readiness.
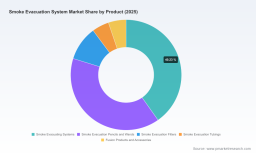
Readers will find practical structures designed for immediate use. The segmentation discussion clarifies how smoke evacuating systems, evacuation pencils and wands, filters, tubings, and fusion products and accessories relate to one another in real operating room settings, enabling more accurate forecasting of consumable burn rates, service intervals, and replacement cycles. The application analysis situates smoke evacuation demand within the procedural contexts that generate the highest plume exposure, including laparoscopic, orthopedic, and medical aesthetic surgeries, alongside other clinical environments, supporting volume-based purchasing logic and case-mix planning. The regional dimension is evaluated through the lens of adoption maturity, policy intensity, and capital deployment patterns, helping organizations gauge where demand is consolidating, where it is expanding, and where competitive pressure is most likely to intensify.
Beyond segmentation, the report integrates regulatory tracking, reimbursement pathway analysis, and cost-structure evaluation into a unified decision framework. Hospital administrators and ambulatory surgery center operators can use these sections to model per-room investment thresholds, compare recurring disposable economics, and identify the documentation requirements that determine whether reimbursement or compliance objectives are achievable. Commercial teams can use the same material to anticipate purchasing committee priorities, align product positioning with integration expectations, and time launches or contract renewals to match procurement cycles. The analysis is deliberately built to bridge clinical safety objectives and financial discipline, ensuring that recommendations can be defended in both operational and budget-review settings.
Translating 2026 Intelligence into Operational Advantage
The value of this research lies in its ability to convert market motion into decision timing. For hospital and surgery center leaders, the 2026 planning window is not simply a budget cycle. It is the moment when regulatory momentum, reimbursement pathways, and product clearance activity converge to reshape equipment standardization. Facilities that treat smoke evacuation as a discrete accessory purchase risk underpricing the total lifecycle impact and overestimating the flexibility of future procurement. Organizations that instead evaluate evacuation performance alongside workflow compatibility, consumable economics, and state-level reimbursement exposure are better positioned to negotiate service terms, consolidate vendor relationships, and protect perioperative throughput.
For medical device and equipment strategists, the same intelligence clarifies where competitive pressure is likely to concentrate. The combination of elevated market concentration, recurring regulatory clearances, and reimbursement-driven purchasing creates a landscape in which feature parity alone is insufficient. Differentiation increasingly depends on demonstrable integration with existing electrosurgical or laparoscopic platforms, predictable disposable cost structures, and compliance support that reduces administrative friction for hospital buyers. The report provides the context needed to test product positioning against these expectations, anticipate procurement committee objections, and calibrate go-to-market timing against the rhythm of hospital capital planning.
The dataset and analytical structure behind this overview extend far beyond the summary framing. Detailed segmentation logic, competitive benchmarking, procurement sensitivity considerations, and policy-linked demand drivers are developed in full within the complete study. Readers seeking the operational figures, scenario models, and vendor evaluation detail required to finalize 2026 capital plans, contract strategies, or commercial positioning will find the complete intelligence package structured for that purpose. The macro trajectory outlined here is intended as a strategic preview: enough depth to validate the analytical rigor, while preserving the precise segmentation and scenario detail that decision-makers need before committing budget or negotiating terms.
Conclusion: Positioning for a Compliance-Driven Growth Cycle
The smoke evacuation system market is moving from niche consideration to structured procurement priority. Historical expansion, regulatory mandates, reimbursement mechanisms, and concentrated competitive activity are combining to create a purchasing environment where timing, integration, and total cost discipline determine outcomes. PW Consulting's research translates these forces into a single decision framework, linking market growth signals to the practical requirements of hospital procurement, clinical engineering, and device strategy. For executives entering 2026, the objective is no longer to determine whether smoke evacuation matters. The objective is to decide how to buy, when to standardize, and which vendor attributes will deliver measurable value under the next cycle of regulatory and reimbursement pressure. The full report is structured to support those decisions with the depth, clarity, and procurement-grade detail required for confident action.
For detailed analysis of this topic, please visit the official page: Smoke Evacuation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


