



PW Consulting: Musical Instrument Market Hits $137.5M in 2025, Projects 6.46% CAGR to 2032

Strategic Intel for 2026: Navigating the Musical Instrument Market Landscape
The global musical instrument market stands at a critical inflection point in 2026. Beyond the romanticism of melody and performance, the sector is a complex commercial ecosystem shaped by supply chain friction, shifting consumer demographics, and technological convergence. For executives, investors, and product leaders, understanding the structural forces driving this industry is no longer optional—it is a prerequisite for sustainable growth and risk mitigation.
At PW Consulting, we have just released our comprehensive Musical Instrument Market research report, a definitive intelligence asset designed specifically for enterprise decision-making in the 2026-2032 horizon. This article serves as a strategic preview, outlining the market's foundational mechanics, the competitive architecture, and the pressing operational challenges that define the current landscape. While we invite you to explore the full methodology and granular breakdowns in our complete publication, this overview establishes why this research is a vital compass for your next strategic moves.
Market Trajectory and Growth Architecture
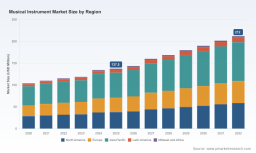
The musical instrument sector has demonstrated remarkable resilience through recent macroeconomic volatility. Drawing on historical performance from 2020 through 2025, the industry has consistently expanded its revenue base, transitioning from a post-pandemic recovery phase into a period of steady, demand-driven growth. Our models project the total market valuation to reach approximately 143.59 million USD in 2026, with a clear upward trajectory continuing through 2032, where the market is anticipated to breach the 212.0 million USD threshold. This expansion is underpinned by a compound annual growth rate of 6.46 percent, a figure that translates into meaningful opportunities for market participants who can correctly position their portfolios against evolving demand centers.
It is crucial to recognize that these macro-level projections are not a uniform tide. Growth is unevenly distributed across product categories, use cases, and geographic territories. The interplay between traditional acoustic craftsmanship and modern electronic integration is reshaping consumption patterns, while infrastructure investment in music education and professional performance ecosystems continues to inject fresh capital into the supply chain. Our research dissects these currents with precision, identifying the specific demand nodes where commercial value is concentrating and where saturation risks are emerging.
The Competitive Ecosystem: Incumbents and Innovation Drivers
The competitive architecture of the musical instrument market is characterized by a blend of heritage manufacturing powerhouses and agile technology innovators. Concentration among the top tier remains significant, with the three largest players commanding a combined market share of approximately fifty percent, while the top five entities collectively account for sixty percent of total revenue. This oligopolistic structure does not stifle innovation; rather, it creates a highly stratified landscape where market leaders defend their positions through technological differentiation, global distribution networks, and deep brand equity, while mid-tier and niche players compete through specialization and targeted consumer engagement.
Yamaha Corporation, headquartered in Japan, continues to set the benchmark for comprehensive portfolio coverage. Its dominance spans guitars, pianos, keyboards, wind instruments, and digital music products, giving it unparalleled leverage across both beginner and professional segments. Roland Corporation, also based in Japan, has carved out a formidable identity in digital synthesizers, electric guitars, pianos, and integrated music technology solutions, positioning itself at the intersection of hardware craftsmanship and software-driven sound design. On the American side, Fender Musical Instruments Corporation remains synonymous with electric guitars, basses, amplifiers, and acoustic instruments, maintaining a cultural relevance that transcends mere product functionality. Steinway & Sons and Kawai Musical Instruments Mfg. Co., Ltd. compete in the premium piano segment, catering to conservatory-level professionals and discerning homeowners who prioritize acoustic fidelity. C.F. Martin & Co., Inc. and Eastman Music Company have built enduring reputations around acoustic guitars, mandolins, and banjos, anchoring the heritage segment with meticulous craftsmanship. In the wind and percussion domains, Conn-Selmer Inc., Buffet Crampon Group, and Meinl percussion reinforce the ecosystem's breadth, while D'Addario & Company, Inc. sustains a critical upstream position through strings, accessories, and maintenance products that support instrument lifecycles across categories.
Recent 움직임을 underscore the intensity of competitive signaling. In January 2026, Epiphone revived the cult-classic Gibson RD guitar as part of its Futura series lineup, introducing fresh designs, new pickups, and varied tonal options to reengage legacy enthusiasts. Ibanez simultaneously debuted updated TOD nylon models featuring new finishes, refined ergonomics, and upgraded Fishman acoustic imaging, explicitly targeting shred-friendly playability. Roland unveiled flagship updates including new digital instruments and music technology solutions at NAMM 2026, reinforcing its technology-forward positioning. Meinl percussion returned to the NAMM Show 2026 to showcase innovations and strengthen global network connections, while the Music China Organizing Committee announced that Music China 2026 would launch an inaugural Music Lifestyle & Creative Products Zone targeting Gen Z audiences with new thematic zones. These developments are not isolated product launches; they are strategic bets that signal where incumbents believe the next wave of consumer attention will originate.
Regulatory Frictions and Supply Chain Realities
While demand dynamics continue to drive top-line expansion, the operational environment in 2026 is heavily complicated by regulatory and trade-policy friction. Tariff exposure has emerged as one of the most consequential variables for market participants. In the first quarter of 2026, the average effective tariff rate on musical instrument imports into the United States reached 16.6 percent, a notable increase from the 15.9 percent recorded in 2025. This upward shift has tangible downstream effects: imports of wind instruments in 2025 fell by 27 percent, while piano imports declined by 20 percent, reflecting both price sensitivity among entry-level buyers and procurement recalibration among distributors.
The tariff landscape is not uniform across product categories. Higher effective tariff rates for pianos, acoustic keyboards, strings, and wind instruments more than tripled in 2026 compared to 2024, creating a highly asymmetric cost environment that disproportionately affects categories reliant on cross-border component sourcing and finished-goods importation. Sector-level analyses indicate that tariff-related price increases accounted for the entire 1.9 percent rise in combined revenues for the one hundred largest U.S.-based suppliers of music products, pushing aggregate revenues to approximately 10.5 billion USD in 2025. Beyond consumer-facing pricing dynamics, Section 232 tariffs on metals have elevated domestic input costs for manufacturers that depend on imported raw materials, compressing profit margins and forcing difficult trade-offs between absorption, pass-through, and product redesign.
For strategic planners, these dynamics introduce a new layer of scenario planning. Cost structures are no longer static, procurement pathways are subject to geopolitical recalibration, and margin preservation requires a more sophisticated understanding of regional sourcing alternatives, tariff engineering, and pricing elasticity across customer segments. Our report provides a structured framework to navigate these uncertainties, mapping the exposure points and identifying the operational levers that can insulate profitability without sacrificing market share.
Structural Shifts in Demand and Application
The demand architecture of the musical instrument market is undergoing a quiet but profound restructuring. Educational use remains the dominant application driver, reflecting sustained institutional investment in music programs, afterschool enrichment, and community-based learning initiatives. Professional use continues to represent a high-value segment, anchored by performance venues, recording studios, touring ecosystems, and institutional conservatories that demand reliable, high-fidelity instruments. Personal use, meanwhile, has expanded beyond casual hobbyism, driven by the democratization of music creation, the proliferation of home studio setups, and the growing cultural emphasis on creative self-expression among younger demographics.
These application streams do not operate in isolation. They intersect with regional consumption patterns, product category preferences, and channel dynamics in ways that create both synergies and trade-offs. A product strategy optimized for educational volume may not translate effectively to professional-grade performance expectations. A distribution model built around direct-to-consumer digital channels may underperform in markets where tactile retail experiences and dealer networks remain the primary purchase drivers. Our research maps these intersections systematically, helping organizations avoid the common pitfall of overgeneralizing demand and instead align product roadmaps, pricing architectures, and channel strategies with the specific realities of each application segment.
What the Full Report Delivers: Translating Intelligence into Execution
The complete PW Consulting Musical Instrument Market report is built for practitioners who require more than high-level trends. It delivers an integrated intelligence platform that connects market sizing, segmentation, competitive profiling, and regulatory scenario analysis into a single, actionable reference. Readers will gain access to historical performance baselines spanning 2020 to 2025, forward-looking projections through 2032, and a detailed dissection of the structural forces that will shape revenue allocation across the forecast window.
Musical Instrument Market
Flutes Instrument Market
The report provides deep operational coverage across multiple dimensions. It examines how demand is distributed across product categories and use cases, identifies the geographic territories where growth momentum is strongest, and unpacks the competitive maneuvers that market leaders are deploying to defend and expand their positions. It also delivers a close reading of the trade-policy environment, translating tariff shifts and input-cost pressures into practical guidance for procurement, pricing, and geographic footprint decisions. Throughout, the analysis is anchored in real-world signals, including recent product launches, trade-show innovations, and event-level strategic announcements that reveal how incumbents are repositioning themselves in response to evolving consumer expectations.
Beyond descriptive analysis, the report is structured to support decision-making. It highlights where concentration risk is building, where white-space opportunities exist for targeted product introductions or regional expansion, and where margin compression is most likely to intensify under current regulatory trajectories. For organizations planning capital allocation, product portfolio adjustments, or market-entry initiatives, the report provides the contextual depth required to move from intuition to evidence-based strategy.
Strategic Imperatives for 2026 Decision-Makers
As the market moves through 2026, several strategic imperatives are coming into focus. First, tariff environment resilience must be embedded into product planning and sourcing architecture. Organizations that rely on single-source cross-border supply chains face heightened vulnerability, while those that have diversified input pathways and built flexible pricing models are better positioned to preserve margins without alienating price-sensitive customers. Second, the convergence of acoustic heritage and digital functionality is accelerating, and product roadmaps that treat these domains as separate silos risk missing the integrated experiences that modern consumers increasingly expect. Third, the generational shift in music consumption is reshaping not only what instruments are purchased, but how they are discovered, evaluated, and integrated into broader lifestyle and creative ecosystems. Engagement strategies that fail to account for this shift will struggle to build durable brand affinity.
Finally, competitive intelligence is no longer a periodic exercise. The cadence of product launches, technology unveilings, and regional event strategies is intensifying, and organizations that monitor these signals systematically will be better equipped to anticipate shifts in consumer attention and competitor positioning. The recent activity at NAMM 2026, the revival of legacy guitar designs, the expansion of creative product zones targeting younger audiences, and the ongoing refinement of digital instrument portfolios all point to a market that is simultaneously honoring its heritage and actively reinventing its value proposition.
Access the Complete Intelligence Package
The musical instrument market in 2026 rewards organizations that combine strategic foresight with operational discipline. Growth is real, but it is unevenly distributed, and the cost environment is increasingly complex. Success will belong to those who can align product portfolios with true demand drivers, manage regulatory exposure proactively, and interpret competitive signals with precision rather than assumption.
This article has outlined the structural contours of the market and the strategic questions that matter most. However, the full resolution of these questions requires deeper data, segmented analysis, and scenario-grade modeling that only the complete PW Consulting Musical Instrument Market report can provide. We invite you to access the full publication to obtain the comprehensive breakdowns, competitive assessments, and forward-looking projections necessary to inform your 2026 decisions with confidence. The detailed intelligence is available at the source page, where the complete research architecture, methodology, and actionable insights await your review.
For detailed analysis of this topic, please visit the official page: Musical Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


