



PW Consulting: Eyeglass Edging Machines Market Hits $1,056 Million in 2025, Projected 5.8% CAGR to 2032

Strategic Intelligence for 2026: Navigating the Global Eyeglass Edging Machines Market
The global ophthalmic equipment landscape is undergoing a period of deliberate, technology-driven expansion. As optical retailers, manufacturing labs, and healthcare procurement teams plan capital expenditures through 2032, the Eyeglass Edging Machines Market stands at a structural inflection point. Drawing on our latest Eyeglass Edging Machines Market research, this analysis outlines how industry participants can translate macro trajectories, competitive dynamics, and regulatory shifts into executable 2026 strategies. The report is built to move beyond headline growth figures and deliver the granular, decision-grade intelligence that operations leaders, product managers, and M&A strategists require.
Market Trajectory and the Strategic Case for 2026 Investment
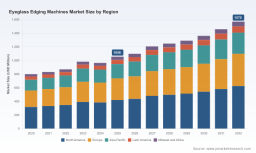
Historical performance through 2025 demonstrates a market that has matured past early-cycle volatility and is now anchored by sustained demand for precision finishing systems. From a base of 800 million USD in 2020, the market advanced through middle-single-digit year-over-year gains, crossing the 1 billion USD threshold in 2025 at a valuation of 1,056.0 million USD. Looking forward, the forecast period from 2026 to 2032 maps a clear acceleration path, beginning at 1,097.54 million USD in 2026 and advancing steadily toward 1,570.0 million USD by 2032. This trajectory reflects a compound annual growth rate of 5.8 percent, a figure that looks modest in isolation but hides meaningful operational implications: product cycle timing, regional capacity reallocation, and the marginal economics of automation adoption will increasingly separate performance leaders from the pack.
For 2026 decision-makers, the immediate takeaway is that growth is no longer a uniform tide. The market is bifurcating between high-throughput, fully integrated finishing lines and specialized systems tailored to in-office, boutique, or specialty-lens workflows. Companies that treat this as a monolithic opportunity risk over-indexing on the wrong system class, overpaying for capacity that does not match their patient or retail volumes, or underestimating the consumable economics that define total cost of ownership. Our research frames the market around this operational reality, so that investment decisions are calibrated to deployment context rather than headline valuation alone.
Operational Landscape: What the Report Delivers
The Eyeglass Edging Machines Market research is structured to support parallel workstreams, from product roadmap planning to supplier evaluation and channel strategy. Rather than presenting static market sizing, the report delivers an operational playbook built around the following components, each designed to feed directly into 2026 planning cycles:
- Deployment and investment mapping by machine architecture. The study evaluates how automatic, semi-automatic, and manual edging platforms are allocated across installation environments. This breakdown helps buyers and manufacturers gauge where throughput, labor substitution, and consistency advantages concentrate, and where flexibility, footprint, or capital constraints still justify lower-automation configurations.
- Application-driven demand analysis. Revenue concentration in optical retail labs, optical manufacturing, and other end-use channels is examined in the context of workflow differences, turnaround expectations, and service models. The goal is to clarify which customer segments are expanding fastest in volume, which are demanding higher precision or faster changeover, and how machine specifications should align with those expectations.
- Regional deployment intelligence. The report assesses how installed base, procurement patterns, and service infrastructure vary across major geographic markets. This regional framing supports localization choices for distributors, service partnerships for OEMs, and pricing strategy for new product introductions.
- Consumable and lifecycle economics. A recurring theme throughout the analysis is that edging machine economics are inseparable from the consumables that sustain them. Grinding wheel performance, block compatibility, and abrasive replacement cycles shape not only operating cost but also service attachment rates. The report connects machine selection to recurring consumable demand so that buyers can model total cost over a realistic service life.
- Competitive benchmarking and positioning. The study maps how leading manufacturers differentiate on throughput, lens compatibility, integration with in-office workflows, and service support. Rather than treating competition as a brand list, the report frames it as a set of design choices and go-to-market models that influence purchasing decisions in different channels.
Each section is built to reduce ambiguity at the point of decision. Procurement teams can use the comparison frameworks to narrow equipment shortlists. Product leaders can use the deployment dynamics to identify where feature investment will generate the strongest differentiation. Executive teams can use the consolidated market view to align capacity expansion, channel investment, and M&A focus with where structural demand is strongest.
Competitive Dynamics: Differentiation, Timing, and Regional Footprints
The competitive set in this market is global, but competitive advantage is increasingly local and application-specific. A diversified group of established optics and ophthalmic equipment manufacturers is competing on machine reliability, lens compatibility, throughput, and integration with surrounding lab or in-office workflows. The companies profiled in the study illustrate how this battlefield is being shaped: Coburn Technologies, headquartered in California, offers in-office optical lens edgers such as the HPE-990 and HPE-910 for precision finishing of standard and specialty lenses, including hydrophobic and high-curve varieties, positioning its equipment around clinical finishing quality and office-friendly deployment. Huvitz Corporation, based in South Korea, manufactures lens edging systems including the HPE-990 lens-over-frame sunglass edging system and related models for optical labs and in-office use, linking product design to both lab productivity and specialized frame-over-lens applications.
In higher-volume finishing environments, Nidek Co., Ltd., headquartered in Japan, produces ophthalmic lens edgers such as the LE-9000SX and ME-1200 for high-volume optical finishing, including models compatible with industrial applications, emphasizing throughput and consistency. Essilor International, from France, provides lens edging systems under the Essilor Instruments brand, including the ES 800 and ES 700 series edgers and Mr. Blue models for ophthalmic lens processing, reflecting a broad-based integration strategy across optical finishing ecosystems. Visionix, operating through its Briot heritage in France, manufactures comprehensive lens finishing systems including the Briot Couture and Emotion series for high-volume and lab optical edging, reinforcing the importance of finishing-line integration and repeatability. MEI Srl, based in Italy, offers compact automatic lens edgers such as the EasyFit Trend and Trend series designed for small optical labs and block-less processing, addressing space-constrained or lower-volume settings where versatility matters. Topcon Corporation, also from Japan, supplies optical lens edgers and related finishing equipment for ophthalmic and lab applications, contributing deeper lab-side equipment depth to the competitive field. Innava Medical Ophthalmics, Inc., in the United States, provides ophthalmic equipment including lens edgers for clinical and lab use, broadening the clinical-to-lab bridge in North American procurement. In Asia, Shanghai Supore Instruments Co., Ltd. manufactures lens edgers and optical lab machinery including automatic models for precision edging, while Ningbo FLO Optical Co., Ltd. produces automatic lens edging machines for optical manufacturing and repair applications, both reflecting expanding domestic manufacturing capabilities and export-oriented capacity.
Recent product activity underscores how quickly competitive positioning can shift around a single platform. In August 2025, Coburn Technologies introduced the HPE-990 Lens Edger, a premium in-office finishing system with enhanced capabilities for standard and specialty lenses including high-curve and hydrophobic types. In May 2025, Huvitz launched the HPE-990 lens-over-frame sunglass edging system, unveiled at MIDO 2025 and planned for expansion in North America. These moves matter because they illustrate a recurring strategic pattern: manufacturers are sharpening differentiation by lens type, workflow setting, and regional rollout timing rather than by competing on broad, undifferentiated hardware specifications alone. The report uses these developments to show where competition is tightening, where regional roll-out windows create first-mover advantages, and where consumables or service attach may become the real margin battleground.
Eyeglass Edging Machines Market
Market Dynamics and the 2026 Operating Environment
Equipment purchases do not happen in isolation; they are shaped by supply-chain behavior, regulatory pressure, and labor economics. Three dynamics in particular are shaping the 2026 decision environment.
First, consumable supply chains are becoming a strategic variable rather than a background cost item. Premium diamond-abrasive wheels used in lens edgers face tight global supply chains, which disproportionately affects precision segments of the market where edge quality, surface integrity, and repeatability are non-negotiable. For buyers, this means machine selection increasingly needs to account for abrasive compatibility and supplier continuity, not only for capital cost. For manufacturers, it means the durability and flexibility of grinding solutions can become a purchase driver in their own right.
Second, regulatory expectations are shifting the specification baseline upward. Stricter dust-emission norms for optical workshops in the EU and North America require modern enclosed systems in lens edger operations, pushing buyers toward equipment that meets tighter environmental and occupational health standards without sacrificing throughput. At the same time, the new EN IEC 60601-2-57:2026 standard sets safety and performance requirements for non-laser light source equipment, with enforcement beginning in 2026. Compliance is not a static checkbox; it can influence design features, service obligations, and buyer risk tolerance, especially for organizations operating across multiple jurisdictions. These requirements increase the value of verified compliance documentation and validated installation support.
Third, labor economics are reshaping the value proposition of automation. Advanced grinding wheel technology and ergonomic improvements in lens edgers reduce reliance on skilled manual operators while improving finish quality on materials such as polycarbonate and Trivex. This does not eliminate the need for skilled oversight, but it changes where that skill is applied. Operations can shift from repetitive finishing labor toward setup optimization, quality control, and machine uptime management. For 2026 planning, that means the business case for automation is increasingly tied to consistency, throughput stability, and training burden, not just labor cost reduction.
Optical Lens Edger Market
Together, these dynamics create a market environment in which the most valuable intelligence is not simply how large the market is, but how it behaves under real operating constraints. The report connects these forces to equipment decisions so that buyers and manufacturers can anticipate where specifications, service coverage, and consumable strategy will matter most.
Why This Research Supports Better 2026 Decisions
In a market growing at a 5.8 percent CAGR over a seven-year forecast horizon, the competitive advantage lies in timing, targeting, and specification discipline. The difference between generic market awareness and decision-ready intelligence is the ability to answer practical questions: Which machine class fits a given deployment profile? Where are regional procurement and service dynamics likely to support or constrain a rollout? How should product roadmaps respond to regulatory and consumable supply pressures? Where are the competitive white spaces that a new launch or channel investment can exploit?
The Eyeglass Edging Machines Market research is built to answer those questions without forcing every buyer into the same conclusion. It preserves enough segmentation depth for operational use while keeping the analysis focused on strategic implications. The report is intended for executives, category managers, product planners, and investors who need to convert a multi-year growth narrative into a coherent 2026 action plan.
The full study contains the detailed market sizing, segmentation breakdowns, regional deployment context, competitive profiles, and forward-looking scenario framing needed to support investment, procurement, and product strategy decisions. Readers seeking complete data tables, segment comparisons, and the full set of company and regulatory analyses are encouraged to explore the full report on the source page for comprehensive intelligence tailored to 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Eyeglass Edging Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


